Categories
Learn

Is wine a wasting asset for capital gains tax?

  • Whether wine is a wasting asset for capital gains tax depends on the bottle, not the category, because HMRC applies a predictable life test of under 50 years.
  • HMRC’s manual states it would normally contend that fine wine kept for periods well in excess of 50 years is not a wasting asset.
  • Where the exemption does not apply, the chattels rules and the £3,000 annual exempt amount still limit exposure, with gains taxed at 18% or 24% (HMRC, 2026/27).

Fine wine’s reputation as a capital gains tax free asset rests on one narrow statutory rule, and that rule does not cover every bottle. HMRC treats wine as a wasting asset only where its predictable life at acquisition falls under 50 years, and its own guidance singles out long-lived fine wine as the category most likely to fail that test. This article sets out how the rule works, where investment-grade wine sits within it, and which capital gains tax rules apply when the exemption falls away.

What counts as a wasting asset for capital gains tax

HMRC’s wasting asset rule turns on a single number: fifty years. Section 44 of the Taxation of Chargeable Gains Act 1992 defines a wasting asset as one with a predictable life not exceeding 50 years at the time of acquisition. Where an asset is both a wasting asset and a chattel (tangible movable property), section 45 removes the gain from capital gains tax altogether.

That combination explains the attention fine wine receives from private investors. A bottle is tangible, it is movable, and most wine is drunk long before its fiftieth birthday. The exemption applies to the asset in front of HMRC, though, not to wine as a category.

HMRC accepts in its Capital Gains Manual that most wine is consumed well below the age of 50 years, and frames the practical question as whether a wine has turned to vinegar or has merely matured (HMRC, Capital Gains Manual CG76901). Cheap table wine passes that test comfortably. Investment-grade wine is a harder case, and the difference matters at the point of sale rather than the point of purchase.

Two further points frame everything that follows. The exemption is tested at disposal, using facts fixed at the date of acquisition, and the taxpayer carries the burden of establishing those facts. Neither point is obvious from the way the rule is usually summarised in marketing material.

Treatment depends on individual circumstances and may change, so the sections that follow describe how the rules are applied rather than what any particular portfolio will owe.

Why HMRC treats fine wine differently from table wine

Fine wine sits awkwardly inside the wasting asset rule, and HMRC says so directly. The Capital Gains Manual states that, where the facts justify it, HMRC would normally contend that wine is not a wasting asset if it appears to be fine wine which is not unusually kept for substantial periods sometimes well in excess of 50 years (HMRC, CG76901). The wines most likely to be bought as investments are therefore the wines most likely to sit outside the exemption.

Everyday wine faces no real argument in the other direction. A supermarket case will not survive 50 years in bottle, so its predictable life is plainly shorter than the threshold. The problem is that such wine rarely produces a chargeable gain worth arguing about, which leaves the exemption most secure exactly where it is least useful.

Certain investment-grade wines built for long ageing may not qualify for the exemption at all. Investors should take independent tax advice on their own holdings rather than treating the wasting asset rule as automatic.

Fortified wines and other bottles that may not be exempt

Several categories carry an obvious longevity problem, and HMRC identifies them readily. Each is defined by a storage life that a valuer would put beyond 50 years without much hesitation, which is the same evidence an investor would need to argue the opposite.

  • Vintage Port, Madeira and Sherry. Fortification extends life dramatically, and Madeira in particular is drunk at ages measured in centuries rather than decades.
  • Cognac, Armagnac and other long-lived spirits. Bottled spirits are stable almost indefinitely, so a sub-50-year predictable life is difficult to sustain.
  • Sauternes and other sweet wines. Château d’Yquem is routinely cellared for 50 years or more, and its published drinking windows reflect that.
  • Classified Bordeaux and top Burgundy in strong vintages. Critics’ drinking windows for leading estates frequently extend beyond half a century, and those windows are evidence HMRC can read as easily as an investor can.
  • Prestige Champagne. Late-disgorged and vintage cuvees from the leading houses age far longer than the category’s reputation suggests.

Inclusion on this list does not settle the question. An investor holding these wines needs a documented, wine-specific case for a shorter predictable life rather than a general argument about wine as a category.

Predictable life is measured from when you buy, not the vintage

Predictable life runs from the date of acquisition, not the date on the label. That single point reverses the intuition many investors bring to the question, and it can work in an investor’s favour.

Consider two purchases. A buyer who acquires a mature 1970 Bordeaux in 2026 is holding a wine with perhaps 15 to 20 years of useful drinking life remaining, which sits comfortably below the threshold. A buyer who acquires a 2020 First Growth on release is holding a wine whose critic-assessed drinking window may extend past 2080, which does not.

The age of the bottle at acquisition therefore does more work than its total lifespan. Mature stock purchased late in its life has a stronger claim to wasting asset treatment than young stock bought on release, even where the two wines carry the same label. Portfolios assembled around back vintages and drinking-window purchases sit differently, for tax purposes, from portfolios assembled around En Primeur allocations.

None of this converts an argument into a certainty. HMRC assesses the facts of each disposal, and the burden of showing a predictable life under 50 years sits with the taxpayer.

The chattels exemption when wine is not a wasting asset

A wine that fails the wasting asset test is still a chattel, and the chattels rules limit exposure in their own right. Section 262 of the same Act provides that a gain is not chargeable where the disposal proceeds do not exceed £6,000, with marginal relief above that figure capping the chargeable gain at five thirds of the excess over £6,000 (HMRC, 2026/27).

Several further allowances sit alongside it:

  • The annual exempt amount. Individuals have £3,000 of tax-free gains in the 2026/27 tax year, and trusts have £1,500 (HMRC, 2026/27).
  • Rates on the balance. Gains above the allowance are taxed at 18% within the basic rate band and 24% above it for the 2026/27 tax year (HMRC, 2026/27).
  • Joint ownership. Where a chattel is owned jointly, each owner has their own £6,000 threshold against their share.
  • Allowable costs. Acquisition price, buying and selling commissions and other qualifying costs reduce the gain before any rate applies.

A worked example shows the effect. A case sold for £7,500 that originally cost £3,000 produces a gain of £4,500 before relief, but marginal relief caps the chargeable gain at five thirds of the £1,500 excess over the threshold, or £2,500. The annual exempt amount then absorbs most of that balance for an investor with no other gains in the year.

The practical effect is that a portfolio disposed of in measured steps, with proceeds per asset kept modest, may generate little or no chargeable gain even where the wasting asset argument fails. 

How the sets rule affects cases of wine

The sets rule catches more investors than any other part of wine’s capital gains tax treatment. HMRC can treat items that form a set as a single asset where they are sold to the same person, or to connected persons, so the £6,000 threshold applies once across the whole transaction rather than to each bottle.

Bottles of the same wine and vintage are natural candidates. They are similar, they are complementary, and a complete case is generally worth more than the sum of its bottles, which is the test HMRC applies. A 12-bottle case sold intact to one buyer is one disposal against one £6,000 threshold, not twelve disposals against twelve.

Splitting a case across several buyers to stay under the limit is the obvious response, and it carries obvious risk. Where the sales are to connected persons, or form part of a single arrangement, HMRC can aggregate them. Genuine commercial reasons for separate sales are a different matter from timing designed purely to fragment a set.

Format complicates the picture. Magnums, double magnums and mixed formats of the same wine can still be similar and complementary, and an original wooden case sold with its packaging intact makes a strong candidate for set treatment. Investors selling through a merchant or at auction benefit from agreeing how lots will be constructed before the sale, because lot structure often determines how many assets have been disposed of.

Record keeping decides most of these questions in practice. Purchase invoices, storage and rotation records, buyer identities and disposal dates are the evidence that distinguishes a series of independent sales from a divided set.

Further reading from WineCap

These Learn articles cover the surrounding ground in more depth:

Trading in wine and the income tax risk

Trading in wine and investing in wine attract different taxes, and the wasting asset exemption is irrelevant to the first. Where activity amounts to a trade, profits fall within income tax at rates up to 45%, plus National Insurance, rather than within the capital gains regime at all.

HMRC applies the badges of trade to decide which is which. Frequency and volume of transactions, short holding periods, the way purchases are financed, whether stock is actively marketed, and whether the buyer holds any intention of consumption all feed the assessment. An investor who buys allocations and holds them in bond for years looks very different from one who turns stock over monthly at a margin.

Structure matters as much as behaviour. Wine held through a company sits outside the chattels and wasting asset reliefs available to individuals, because those provisions apply to chargeable gains on chattels rather than to corporate trading stock. Wine is also treated as taxable property for self-invested personal pensions, so holding it inside a pension wrapper attracts punitive charges rather than shelter.

The distinction is not always clean, and no single badge decides it. Investors running high-frequency activity, or operating through a company, should take specialist advice before assuming capital treatment applies.

The evidence that supports a wasting asset position

A wasting asset position is only as strong as the evidence recorded behind it. HMRC assesses predictable life on the facts as they stood at acquisition, which means the supporting material needs to exist at that point rather than being assembled after a disposal.

Investors in this position typically keep:

  • Acquisition records showing the date, price and the age of the wine when bought, since predictable life runs from that date.
  • Drinking window evidence from named critics or merchants for the specific wine and vintage, dated at or near acquisition.
  • Storage and condition records, including bonded warehouse documentation, ullage checks and any condition reports.
  • Disposal records identifying the buyer, the date, the quantity and whether the sale formed part of a set.

Professional valuations carry more weight than an investor’s own assessment. Where the wine sits near the boundary, a written opinion from a specialist merchant or valuer, obtained before disposal, is materially more useful than a retrospective argument.

Timing of the evidence matters more than volume. A drinking window retrieved years after purchase is weaker than a dated merchant assessment held from the outset, and HMRC enquiries typically follow a disposal rather than precede it. Recording the position annually costs little and answers the question that arrives later.

Tax treatment depends on individual circumstances and may change. Nothing in this article is tax advice, and readers should consult a qualified adviser on their own position before relying on any exemption.

How fine wine’s tax treatment compares with other investments

Wine’s position looks favourable against most alternative assets and unremarkable against a few. The comparison matters because the wasting asset argument is often part of the reason wine enters a portfolio, and the alternatives carry reliefs of their own.

  • Listed equities and funds. Gains are chargeable at 18% or 24% for 2026/27 unless held inside an ISA or pension, and those wrappers are unavailable to wine (HMRC, 2026/27).
  • Gold. UK legal tender coins such as Britannias and Sovereigns are exempt from capital gains tax, while bars and foreign coins are chargeable in the ordinary way (HMRC, 2026/27).
  • Classic cars. Private motor cars are specifically exempt, which gives them a clarity wine’s position lacks.
  • Art and antiques. These are chattels with long lives, so they attract no wasting asset exemption and rely on the £6,000 threshold alone.
  • Whisky casks. Spirits in cask raise similar wasting asset arguments, though the category has drawn increasing regulatory scrutiny over valuation and ownership practices.

Treating the exemption as a question, not a feature

The wasting asset rule is best understood as a question HMRC asks about a specific bottle on a specific date. That framing changes how a portfolio is built. Acquisition age, disposal sequencing, buyer identity and documentation all shape the answer, and each of them is a decision an investor makes rather than a rule handed down.

The wines most attractive for their ageing potential are the wines least likely to satisfy a sub-50-year predictable life. Investors who understand that tension early can plan around it, using the chattels rules, the annual exempt amount and disposal timing where the exemption itself is doubtful. Those who assume the exemption applies across a cellar may find the assumption tested only once a disposal has already happened, when the options have narrowed considerably.

FAQ: Wine and capital gains tax

Is wine exempt from capital gains tax in the UK?

Wine is exempt only where it qualifies as a wasting asset, meaning a predictable life of under 50 years at the date of acquisition, under sections 44 and 45 of the Taxation of Chargeable Gains Act 1992. HMRC’s guidance states it would normally contend that fine wine kept for periods well in excess of 50 years does not qualify (HMRC, CG76901). Treatment depends on individual circumstances and may change, so independent tax advice is essential.

Does the wasting asset exemption apply to vintage Port?

Fortified wines including vintage Port, Madeira and Sherry have recognised storage lives well beyond 50 years, which places them outside the wasting asset exemption in most cases. A gain on those wines is assessed under the ordinary chattels rules instead, with the £6,000 per asset threshold and the £3,000 annual exempt amount available (HMRC, 2026/27).

How much capital gains tax would I pay on a wine sale?

Where a gain is chargeable, the rate is 18% within the basic rate band and 24% above it for the 2026/27 tax year, after deducting the £3,000 annual exempt amount and any allowable costs (HMRC, 2026/27). A single chattel sold for £6,000 or less produces no chargeable gain at all, and marginal relief limits the gain on proceeds slightly above that figure.

Does selling a case of wine count as one disposal or twelve?

A case sold intact to a single buyer is generally treated as one asset, because bottles of the same wine and vintage are similar, complementary and worth more together than separately. That means one £6,000 threshold applies to the whole case. Selling bottles separately to connected persons, or as part of a single arrangement, can still be aggregated by HMRC.

What records should an investor keep to support a wasting asset claim?

Acquisition invoices showing the date, price and age of the wine at purchase are the foundation, since predictable life is measured from acquisition rather than vintage. Dated drinking window assessments from named critics, bonded storage documentation and full disposal records covering buyer and quantity complete the picture. A written valuation from a specialist merchant obtained before sale carries more weight than a retrospective argument.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.
Categories
News

Bordeaux’s commemorative bottles: Does the gold label pay off?

  • Bordeaux’s 2025 vintage arrives alongside anniversary bottles from Gruaud Larose (300 years) and Brane-Cantenac (100 years), pairing an exceptional harvest with collectable packaging.
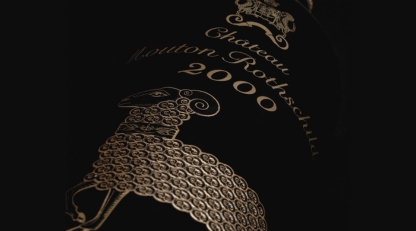
  • Mouton Rothschild’s golden 2000 vintage, Bordeaux’s best-known commemorative bottle, has appreciated close to 750% since release.
  • Charity auction results for artist bottles, such as Ornellaia’s Vendemmia d’Artista, reflect philanthropy and uniqueness rather than a reliable secondary market benchmark.

Bordeaux has a habit of marking its anniversaries in gold, and 2025 gives it plenty to celebrate. Chateau Gruaud Larose turns 300, Chateau Brane-Cantenac marks a century under the Lurton family, and both have used the vintage to release decorated bottles alongside a harvest that produced limited yields but genuine quality. The pattern is not new. For decades, Bordeaux estates have paired milestone years with special packaging, and some of those bottles, most famously Mouton Rothschild’s 2000 vintage, have gone on to outperform their standard-issue counterparts by a wide margin. This piece works through the current crop of anniversary releases, what the data says about whether a decorated bottle is worth paying up for, and how two of Italy’s best-known names, Sassicaia and Ornellaia, approach collectability in very different ways.

Bordeaux’s 2025 vintage arrives wrapped in anniversaries

Gruaud Larose, the Saint-Julien Second Growth founded in 1725 by Joseph-Stanislas Gruaud, marks 300 years of history with its 2025 release. The bottle is etched and screen-printed with golden leaves from the Cabernet Sauvignon vine, the grape that makes up 77% of this year’s blend. It is available across the full range of formats, from standard bottle through to jeroboam, and buying En Primeur (purchasing wine before it is bottled, based on cask samples) allows collectors to select and even customise larger formats for their own celebrations.

Chateau Brane-Cantenac, in Margaux, marks 100 years under the Lurton family with a golden label for 2025. Leonce Recapet acquired the property in 1925, and it has passed through five generations to reach Henri Lurton, who has overseen the estate since 1992 and handed ownership to his children in 2022. The embossed sun on the new label was inspired by a medallion found on a 19th-century Brane-Cantenac bottle, and it doubles as a nod to Henri’s father Lucien, whose name translates loosely as “bringer of light.”

Not every 2025 anniversary bottle looks backwards. Chateau Grand-Puy-Lacoste, the Pauillac classified growth, used the vintage to christen a new gravity-fed cellar, the result of a decade-long renovation led by Francois-Xavier Borie and his daughter Emeline. The bottle carries a screen-printed image of the chateau itself, available in everything from 75cl to imperial format.

The timing matters for investors weighing up whether to buy in. Exceptional weather across 2025 produced limited yields but genuinely strong quality, yet the En Primeur market did not respond enthusiastically across the board. That gap between the quality in the glass and the market’s muted reaction is the setting in which a well-chosen anniversary bottle, from an estate with a track record of translating milestones into price appreciation, tends to stand out from the pack.

Golden bottles carry Bordeaux’s most collectable history

The tradition of decorating the bottle itself, rather than just the label, runs deeper than any single vintage. A handful of releases have become genuine collector benchmarks:

  • Mouton Rothschild 2000 features a golden Augsburg Ram relief-enamelled directly onto the glass, inspired by a 16th-century silver-gilt drinking vessel in the chateau’s own museum. Since 1945, Mouton has commissioned a different artist for its label every year, a roll call that includes Dali, Picasso, Miro, Warhol and Hockney, but the millennium vintage is the one time the bottle itself became the artwork.
  • Chateau Angelus 2012 received a golden version of its bell emblem to mark both its promotion to Premier Grand Cru Classe A and the 230th anniversary of the Bouard de Laforest family’s arrival in Saint-Emilion. The gold, 21.7 carats of it, was enamelled onto the glass and fired at 500 degrees Celsius.
  • Chateau Margaux 2015 replaced its label entirely with a screen-printed image of the Palladian chateau, marking the building’s bicentenary, the completion of Norman Foster’s new facilities, and the final vintage overseen by longstanding managing director Paul Pontallier.
  • Chateau Cos d’Estournel 2020 marked 200 years of the estate and 20 years under owner Michel Reybier with a golden bottle depicting its distinctive Asian-inspired architecture.
  • Chateau Ducru-Beaucaillou and Chateau Smith Haut Lafitte, both releasing 2020 vintages for their own 300th and 30th anniversaries respectively, took a lighter touch, redesigning the label rather than decorating the glass.

Family anniversary collections extend beyond a single vintage

Some estates mark their milestones with a collection spanning several vintages rather than one decorated bottle, and these sets carry their own logic for a collector. Chateau Rauzan-Gassies, the Margaux Second Growth, is marking the 90th anniversary of the Quie family’s purchase of the property with a wooden case holding six bottles across three vintages, two each of 1966, 1996 and 2016. The 1966 honours grandfather Paul Quie, who bought the estate in 1946. The 1996 marks the era of his son Jean-Michel Quie. The 2016 represents today’s owners, twins Anne-Francoise and Jean-Philippe Quie, who have run the property since 2000.

The Barton family, owners of Chateau Leoville Barton and Chateau Langoa Barton, have built a similar tribute around consecutive anniversaries. The 2021 vintage of Langoa Barton marked 200 years since the family bought the estate, arriving in Saint-Julien in 1821, with a hand-drawn label by Anne-Lise Yandell built around four themes: origin, heritage, nature and evolution. A limited coffret, of which only 200 were produced, paired individual bottles from 1994, 2000, 2009 and 2016 with a magnum of the 2021 vintage bringing all four images together. Chateau Leoville Barton follows in 2026 with its own 200th anniversary, reviving an Art Deco label the estate used between the 1930s and 1960s.

Chateau Talbot, also in Saint-Julien, marked a century of Cordier family ownership with its 2018 vintage, using a silk-screened image representing a pillar of the estate’s barrel cellar. Chateau Leoville Poyferre’s 2020 vintage celebrated 100 years of Cuvelier family ownership, now in its fourth generation under Sarah Lecompte Cuvelier, with a gold-inlaid bottle depicting the property’s terroir.

Multi-vintage collections matter to investors for a different reason than single decorated bottles:

  • A complete, unbroken set from a single family’s anniversary collection tends to hold together at resale, since buyers value completeness as much as any individual vintage inside it.
  • Provenance matters more here than usual. A case is only worth its full premium if every bottle inside carries the same documented history, ideally held in bond throughout.
  • These releases are typically produced in far smaller numbers than a standard vintage, which supports scarcity value but also means liquidity is thinner than for a widely traded standard case.

Do commemorative labels actually add investment value?

Investors reasonably ask whether a decorated bottle is worth a premium over the standard release, or whether it is simply good marketing. The evidence from Mouton Rothschild, the estate with the longest and most closely tracked history of special editions, suggests the premium is real and measurable.

Prices of the last ten Mouton vintages have risen by an average of 5% in the month following each year’s artist label announcement. The 2012 vintage, labelled by Miquel Barcelo, rose 14.9% in that window, and the 2018 vintage, labelled by Xu Bing, rose 12.6%. Over the same decade, Mouton’s index has risen 44% on average, a run that has outpaced many of its Bordeaux peers.

The 2000 vintage remains the clearest case study. Released at a negociant price (the price at which a wine merchant first sells the wine) of around 250 euros, it now trades at roughly 1,550 euros, and its total appreciation since release is close to 750%. The bottle weathered the Bordeaux downturn of 2011 to 2014, when other First Growths fell sharply, partly because Asian demand for the golden ram design held firm, and partly because 2015, the Chinese zodiac year of the sheep, gave collectors a fresh reason to buy.

Angelus 2012 shows the same effect, albeit at a smaller scale. It trades at more than double its release price today, a solid return but well short of Mouton’s, and a reminder that the anniversary story and the underlying vintage quality both matter to how far a commemorative bottle’s price will travel. Mouton’s advantage is structural as much as sentimental: eight decades of consistent artist commissions have trained the market to treat each new label as a genuine event, which is precisely why a bump of this size shows up so reliably in the trading data rather than in a single standout year.

Charity auction prices are not a secondary market signal

Not every headline-grabbing result for a decorated bottle tells investors what they think it tells them. Ornellaia’s annual Vendemmia d’Artista auction, now in its 18th year, invites a contemporary artist to reinterpret each vintage, then sells a small run of large-format and one-off bottles for charity. The 2023 edition, featuring performance artist Marina Abramovic’s interpretation of the vintage, raised 128,216 euros for the Solomon R. Guggenheim Foundation, with a unique nine-litre bottle signed by Abramovic and paired with a vinyl record and a private dinner selling for 23,560 euros against a presale estimate of 20,000 to 40,000 euros.

Results like that are genuinely impressive, but they price a one-off collectable and a philanthropic donation as much as a wine. A buyer cannot purchase a second signed nine-litre bottle at that price, cannot easily resell it against a known benchmark, and is paying in part for the artist’s name and the cause attached to the sale. That makes it a poor proxy for what a standard case of Ornellaia is worth on the open secondary market, where pricing is set by ordinary supply, demand and vintage quality rather than by auction theatre.

What this means for a fine wine portfolio

A commemorative bottle is worth buying for the story, the packaging and the occasion it marks. Whether it is worth buying as an investment depends entirely on which part of the equation is doing the work. Mouton’s 2000 vintage shows that decorated glass attached to a genuinely great vintage, from an estate with decades of established artist-label history, can outperform the standard market by a significant margin. However, investors weighing up a commemorative release are better served asking about the vintage quality and the estate’s track record first, and treating the decoration as a bonus rather than the reason to buy.

FAQ: Commemorative wine bottles

Do commemorative or artist-label bottles actually trade at a premium?

Some do. Mouton Rothschild’s 2000 vintage, decorated with a golden Augsburg Ram, has appreciated close to 750% since its release, while Angelus’s 2012 golden bottle trades at more than double its release price. The premium tends to track the underlying vintage quality as much as the packaging itself.

Are charity auction results for artist bottles a reliable price guide?

Not necessarily. Ornellaia’s Vendemmia d’Artista auction, which raised 128,216 euros in its most recent edition, prices unique, signed lots bundled with experiences and a charitable donation. Those figures do not reflect what a standard case trades for on the secondary market.

Should investors pay a premium for a decorated bottle over a standard release?

Only where the underlying wine also stands on its own merits. Sassicaia’s 2018 50th anniversary vintage appreciated from around £1,800 to roughly £1,947 per case with no decorated packaging at all, showing that vintage quality can carry a price on its own.

How liquid are commemorative bottles compared with standard releases?

Standard-format anniversary bottles from established estates, such as Mouton’s 2000 vintage, trade actively through the same merchant and auction channels as any other fine wine. Large-format, hand-signed or one-off pieces, by contrast, are far less liquid and are better treated as collectables than tradeable assets.

Does a golden or decorated bottle affect long-term storage value?

Decoration does not change how a wine ages, but original wooden cases and undisturbed packaging, decorated or not, support provenance, and provenance affects resale value. Wines held in bond in a recognised bonded warehouse retain the strongest documented provenance.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.
Categories
Learn

White Burgundy explained: Appellations, producers and ageing

  • White Burgundy is dry white wine from the Bourgogne region of France, almost exclusively Chardonnay.
  • The region’s whites span four sub-regions, from Chablis in the north to the Maconnais in the south, with sharply different styles and price levels.
  • Ageing potential runs from two years at regional level to over three decades at Grand Cru.

White Burgundy is the dry white wine of France’s Bourgogne region, made almost entirely from Chardonnay and named after the place it comes from rather than the grape in the bottle. It is also the region’s main business: white wine accounts for 61% of Bourgogne production by volume, against 27% for red and rose (BIVB, 2024). This guide covers the grape, the four sub-regions, the classification tiers, the producers who define the category, and how long the wines actually last.

What is white Burgundy?

White Burgundy is any dry white wine produced within the delimited Bourgogne appellations of eastern France, running roughly 230 kilometres from Chablis in the north to the Maconnais in the south. Labels carry the name of a place, not a grape, which is the single biggest source of confusion for anyone new to the category. A bottle marked Meursault, Chablis or Puligny-Montrachet is Chardonnay, but the label will not say so.

Geology defines the style as much as winemaking does. Burgundy sits on a band of Jurassic limestone and marl, and that soil, combined with a cool continental climate, gives Chardonnay higher acidity and more mineral definition than the same grape grown in warmer places.

Chardonnay is the grape, with three exceptions

Chardonnay accounts for 57% of plantings across Bourgogne, ahead of Pinot Noir at 34% (BIVB). It is behind every well-known white appellation in the region, from Petit Chablis to Le Montrachet. Three exceptions explain labels that otherwise look out of place:

  • Aligote, at 6% of plantings, is Burgundy’s second white grape. It appears as Bourgogne Aligote at regional level and as Bouzeron in the Cote Chalonnaise, the only village appellation dedicated to it.
  • Sauvignon Blanc is permitted in Saint-Bris, near Chablis, Burgundy’s only Sauvignon appellation.
  • Cremant de Bourgogne, the region’s traditional-method sparkling wine, accounts for 12% of production (BIVB, 2024).

How Burgundy classifies its white wines

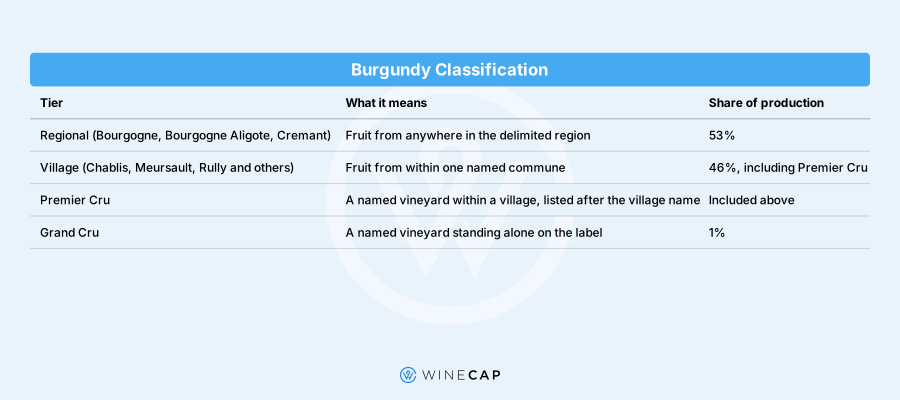
Burgundy classifies wine by vineyard rather than by producer, and the hierarchy is geographical and permanent. A plot carries its classification for good, which is why one producer can offer wines at four tiers from vineyards a few hundred metres apart.

Burgundy Classification

Source: BIVB, September 2024, five-year average 2019 to 2023. 

The white wine regions of Burgundy, north to south

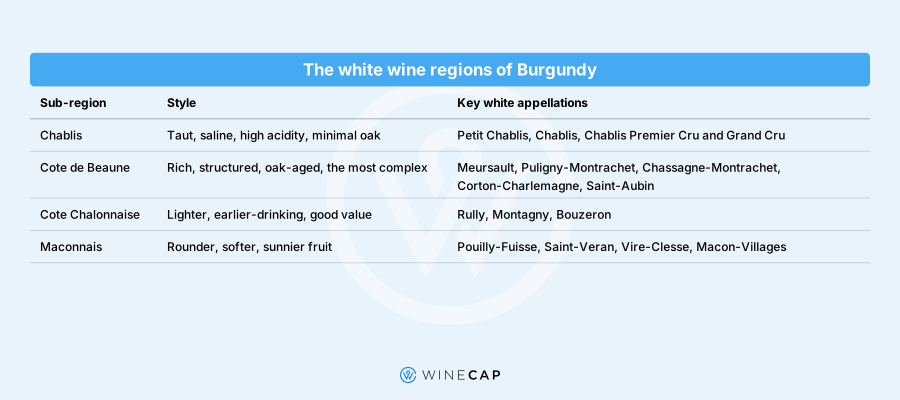
Burgundy’s whites come from four distinct areas, and the differences between them are larger than newcomers expect. Chablis sits closer to Champagne than to Beaune and makes taut, mineral wine with little oak. 

The Cote de Beaune in the middle produces the richest and most expensive whites in the world. 

The Cote Chalonnaise and Maconnais further south offer rounder, earlier-drinking wine at a fraction of the cost.The white wine regions of Burgundy

Chablis owes its character to Kimmeridgian soil, a limestone and marl formation studded with the fossilised oyster shells of Exogyra virgula. Its Premier Cru covers 40 climats across 770 hectares and 13% of Chablis production (BIVB Chablis, 2023). At the southern end, Pouilly-Fuisse gained the Maconnais’s first Premier Crus in September 2020, when INAO approved 22 climats across 194 hectares, the first new Premier Cru tier in any Burgundian appellation since 1943.

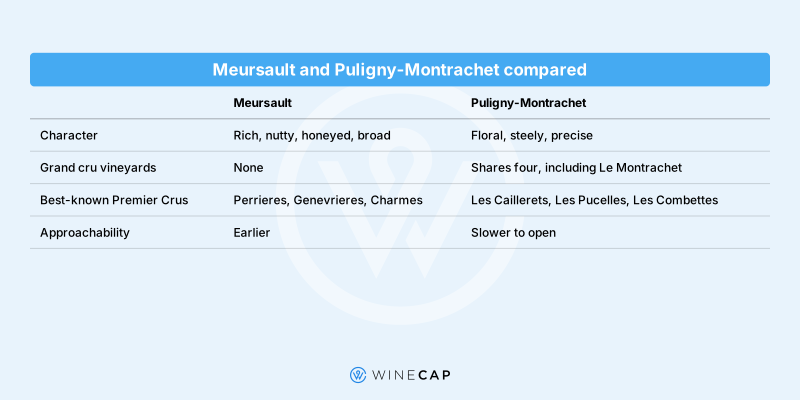
Meursault and Puligny-Montrachet compared

Meursault and Puligny-Montrachet sit side by side on the same limestone slope, and the difference between them is the most useful comparison in white Burgundy.

Meursault is broader, warmer and more forgiving, and drinks well earlier. Puligny is tighter, higher-toned and more mineral, and often needs several more years to show what it has.

Meursault and Puligny-Montrachet compared

The distinction most often credited is drainage. Puligny’s higher water table restricts cellar depth in the village and contributes to the tension in its wines, while Meursault’s deeper, warmer soils give the fuller texture it is known for. Between them sits Chassagne-Montrachet, mineral and succulent with a hazelnut character, and above the slope lies Saint-Aubin, which shares the same limestone at a considerably lower price.

Which producers make the best white Burgundy?

Producer matters more than tier in Burgundy – these are the domaines most often cited as reference points in each area:

  • Chablis: Domaine Francois Raveneau and Domaine Vincent Dauvissat set the benchmark, with William Fevre and Louis Michel recognised for classically styled Premier and Grand Cru wines.
  • Meursault: Coche-Dury, Domaine Roulot, Domaine des Comtes Lafon and Arnaud Ente define the village at the top, alongside Pierre-Yves Colin-Morey.
  • Puligny-Montrachet: Domaine Leflaive is the historical reference point, with Etienne Sauzet long established.
  • Chassagne-Montrachet: Domaine Ramonet is the most cited, and the village is a reliable source of value at Premier Cru level.
  • Corton-Charlemagne: Bonneau du Martray holds the largest single stake and the longest reputation on the hill.
  • Maconnais and Saint-Aubin: Guffens-Heynen, J.A. Ferret and Domaine Hubert Lamy raised expectations for southern Burgundy and for Saint-Aubin respectively.

Allocation rather than availability is the constraint at the very top. Coche-Dury and Raveneau sell to long-standing customers in tiny quantities, which is why their wines surface mainly on the secondary market.

Burgundy’s white Grand Crus

Burgundy’s white Grand Crus are few and very small. Five sit in the Montrachet cluster, straddling Puligny-Montrachet and Chassagne-Montrachet: Le Montrachet itself, Chevalier-Montrachet, Batard-Montrachet, Bienvenues-Batard-Montrachet and Criots-Batard-Montrachet. Le Montrachet covers around eight hectares. Criots-Batard-Montrachet, the smallest, covers 1.57 hectares and yields roughly 8,900 bottles a year (BIVB, five-year average 2017 to 2021).

Corton-Charlemagne, around the hill of Corton to the north, is the largest white Grand Cru and spans three communes: Pernand-Vergelesses, Aloxe-Corton and Ladoix-Serrigny. Chablis has seven Grand Cru climats of its own: Blanchot, Bougros, Les Clos, Grenouilles, Preuses, Valmur and Vaudesir. Together they cover 99 hectares and 1.5% of Chablis production (BIVB Chablis, 2023).

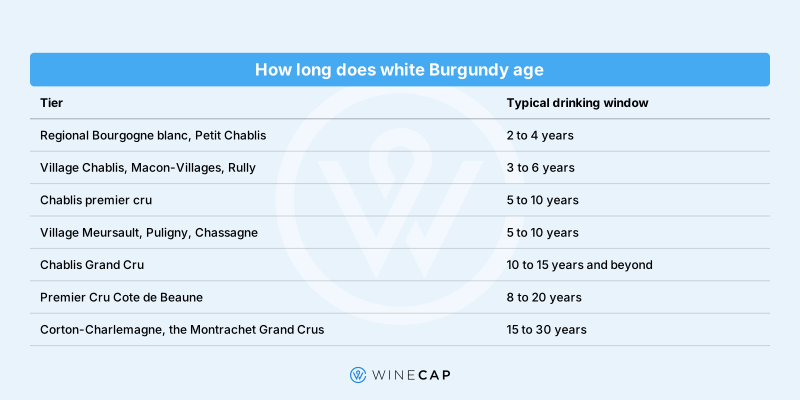
How long does white Burgundy age?

White Burgundy ages for less time than red Burgundy, and considerably less than its reputation suggests. Regional wines are made for early drinking, village wines reward a few years, and the best Cote de Beaune Premier and Grand Crus run for decades.

 How long does white Burgundy age

Premature oxidation and older bottles

Premature oxidation, known as premox, is why experienced buyers treat older white Burgundy with caution. Affected bottles turn deep gold and lose their fruit years before expected, and nothing short of opening one reveals it. The problem became widely apparent in wines from the mid-1990s onwards and dominated discussion of the category for close to two decades.

No single cause was ever established. Reduced sulphur dioxide at bottling, variable cork quality, aggressive lees stirring and changes to pressing have all been implicated. Producers responded by raising sulphur levels, adopting technical closures such as Diam and revising cellar practice, and reported incidence has fallen substantially since the early 2010s. Calling the problem solved would overstate it. For a buyer, the practical conclusion is to favour younger vintages unless a bottle’s storage history is documented.

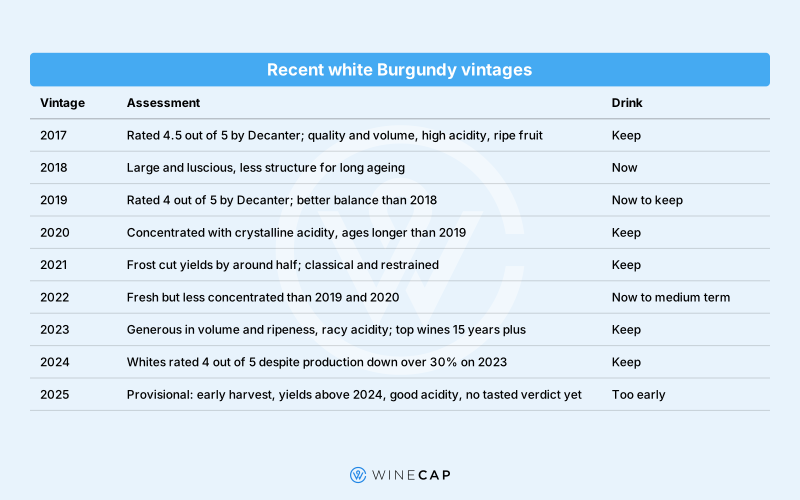
Recent white Burgundy vintages at a glance

Recent vintages have varied more in volume than in quality, with three short harvests in five years. Whites generally fared better than reds through the harder years, notably 2024.

Recent white Burgundy vintages

Sources: Decanter vintage guide and Burgundy 2024 En Primeur report (Charles Curtis MW, updated January 2026), Jancis Robinson vintage notes.

Serving and pairing white Burgundy

Serving temperature matters more for white Burgundy than for almost any other white wine, and most bottles are served too cold. Chablis and village wines show best at 10 to 12 degrees Celsius. Premier and Grand Cru wines need 12 to 14 degrees to open properly, closer to cellar than fridge temperature (BIVB).

Pairing follows the same north-to-south logic as the wines. Chablis and other high-acid whites suit oysters, shellfish and goat’s cheese. Richer Cote de Beaune whites work with lobster, monkfish, veal and poultry in cream and mushroom sauce (BIVB). Mature grand cru handles foie gras and caviar, which is where the region’s reputation for luxury pairings comes from.

Buying and cellaring white Burgundy

Provenance matters more here than for most wine, precisely because oxidation cannot be inspected. Buyers of older bottles study storage history, fill level and closure condition, and discount anything with an unclear past. Wine kept in a bonded warehouse retains a continuous record, which is the main reason collectors buy in bond rather than duty paid.

Burgundy’s whites also attract investor interest, and the region accounted for 69.3% of white wine traded by value on Liv-ex in 2026 to date. Fine wine values fall as well as rise, and past performance is not a guide to future returns, so anyone buying with resale in mind should treat white Burgundy as a long-term holding.

Where to start with white Burgundy

The most useful thing to know about white Burgundy is that its hierarchy of price does not map onto a hierarchy of pleasure. A village Chablis from a careful grower or a Saint-Aubin Premier Cru teaches a drinker more about the region than an expensive bottle from a weak vintage, and the gap between good and indifferent producers at the same address is wider than the gap between adjacent tiers.

That makes producer the first thing to learn and appellation the second. A handful of bottles worked north to south, from names with a track record, will build a clearer picture of the region than any single Grand Cru.

FAQ: White Burgundy

Is Chablis white Burgundy?

Yes. Chablis is the northernmost white wine district of the Bourgogne region and is made entirely from Chardonnay, which makes it white Burgundy in both legal and stylistic terms. It sits closer to Champagne than to Beaune, and its cool climate and Kimmeridgian limestone soil give it a leaner, more mineral style than the richer whites of the Cote de Beaune.

Is white Burgundy the same as Chardonnay?

Almost always. Chardonnay accounts for 57% of plantings across Bourgogne (BIVB) and is the grape behind every well-known white appellation in the region. The exceptions are Bourgogne Aligote and Bouzeron, both made from Aligote, and Saint-Bris, made from Sauvignon Blanc.

Does Meursault have a Grand Cru?

No. Meursault is the only major white wine village of the Cote de Beaune without a grand cru vineyard, despite producing some of Burgundy’s most expensive whites. Its finest sites are premier crus, principally Perrieres, Genevrieres and Charmes, and the best examples reach prices comparable with grand cru wines from neighbouring villages.

What is premox in white Burgundy?

Premox is short for premature oxidation, where a white Burgundy turns deep gold and loses its fruit years before expected. It affected wines from the mid-1990s onwards, and no single cause was established, though low sulphur levels and cork quality were both implicated. Reported incidence has fallen substantially since the early 2010s.

Why is white Burgundy so expensive?

Scarcity explains most of it. Grand Cru accounts for just 1% of Bourgogne production, vineyard boundaries are fixed by appellation law and cannot be extended, and holdings are fragmented among many small growers. Recent short harvests, including a 2024 crop down more than 30% on 2023, have tightened supply further.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.
Categories
Learn

What makes Petrus the world’s most valuable Bordeaux wine?

  • Chateau Petrus has no official classification, yet it commands a higher average price than every Bordeaux First Growth on the secondary market.
  • Liv-ex ranked Petrus fourth in its 2025 Classification at over £31,000 a bottle, ahead of Latour and Lafite by a wide margin.
  • Petrus produces around 30,000 bottles a year from just 11.4 hectares, with no second wine to absorb rejected fruit.

Chateau Petrus sits outside every formal hierarchy in Bordeaux and still outprices all of them. Pomerol has never been classified, so Petrus carries no rank, no growth status, and no crest to justify its position. Its case rests instead on a unique patch of clay, a tiny production run, and seven decades of disciplined ownership under the Moueix family. These ten facts explain why Petrus trades as the most expensive Bordeaux on the secondary market and what that means for an investor weighing it against classified First Growths.

1. The blue clay boutonniere that no other estate can copy

Petrus sits on a geological anomaly rather than a brand story. The Pomerol plateau contains roughly 20 hectares of a raised mound known locally as the boutonniere (buttonhole), where the topsoil and subsoil are packed with iron-rich blue clay unlike anything found in neighbouring vineyards. Petrus occupies 11.4 hectares of that mound, more than half of the entire deposit, at the highest point in the appellation.

The clay behaves differently from the gravel and sand that dominate the rest of Pomerol. It swells and seals when wet, then holds moisture through dry summers, feeding the vines steadily rather than in the stop-start pattern typical of free-draining soils. This cannot be replicated. No amount of capital can buy a second boutonniere; Petrus and its immediate neighbours hold a finite, non-transferable input that underwrites the entire investment case, their excellence, their price point and their growth.

2. No classification, no chateau, and a label that just says Petrus

Pomerol has never been classified, a gap that sets it apart from the rest of Bordeaux. The comparison is stark:

  • Medoc and Sauternes: fixed by the 1855 Classification, unchanged for over a century except for Mouton Rothschild’s 1973 promotion.
  • Saint-Emilion: classified in 1955 and revised periodically, most recently amid legal disputes over methodology.
  • Pomerol: never classified at all, its reputation built entirely after the appellation gained recognition in the mid-20th century, too late to be included in 1855.

Petrus has no grand building either. The estate operates from a modest farmhouse, and the label itself never carries the word “chateau,” reading simply “Petrus, Pomerol.” For investors, this is the clearest possible illustration that price and prestige here rest purely on market consensus and critical reputation.

That reputation is not a recent development. Cocks and Feret, the 19th century’s standard reference guide to Bordeaux still being published today, listed Petrus in 1868 alongside Chateau Trotanoy and just behind Vieux Chateau Certan. A decade later, Petrus won a gold medal at the 1878 Paris Exposition Universelle, an event significant enough at the time to establish a selling price on a par with a Medoc Second Growth, the first Pomerol wine ever to reach that level. The absence of a formal classification has never stopped the market from ranking Petrus among Bordeaux’s elite.

3. From a Libourne hotelier’s widow to a global luxury house

Petrus changed hands slowly and deliberately across the 20th century. The Arnaud family sold up in 1917, and by 1925 Madame Edmond Loubat, who ran a hotel in nearby Libourne, began buying shares. She held full ownership by 1945 and insisted Petrus be priced alongside the First Growths, a conviction that shaped everything that followed.

That same year, negociant Jean-Pierre Moueix secured exclusive selling rights, and the partnership between the two built Petrus into an international name. Following Madame Loubat’s death in 1961, Moueix gradually consolidated control, buying out remaining family shares by 1964 and expanding the vineyard from 7 to 11.4 hectares in 1969 with land purchased from neighbouring Chateau Gazin.

Jean-Francois Moueix now owns the estate with his children. In September 2018, the family sold a 20 percent stake to Colombian-American billionaire Alejandro Santo Domingo, a signal of the kind of institutional capital now willing to buy into Pomerol’s top asset.

Technical continuity has mattered just as much as ownership continuity. Jean-Claude Berrouet served as winemaker for 45 consecutive vintages before retiring in 2008, when his son Olivier Berrouet took over, an unbroken line of stewardship that few Bordeaux estates can match. In 1947, Madame Loubat even presented two magnums of the 1938 vintage to the Lord Mayor of London to mark the wedding of Princess Elizabeth, an early sign of the estate’s ambition to sit among the wines fit for royal occasions.

4. A single grape variety, only since 2010

Petrus is 100 percent Merlot, but that purity is recent. Earlier vintages carried a small proportion of Cabernet Franc, and the shift to a pure Merlot blend only became permanent at the end of 2010. 

The average vine age across the vineyard now exceeds 45 years. Old vines produce lower yields and smaller berries, concentrating flavour and structure in ways young vines cannot replicate regardless of technique in the cellar. For an investor comparing Petrus with Cabernet-dominant Left Bank First Growths, the single-variety approach removes one common source of vintage variation and puts the burden of consistency squarely on terroir and vine age instead.

5. The frost that built a tradition

A severe winter frost in 1956 destroyed roughly two-thirds of the Petrus vineyard. Rather than replanting, Madame Loubat chose to coppice (recepage), cutting the surviving vines back hard to force new growth from established root systems, a technique untried in the region at the time. Her gamble worked, and the practice became the house method whenever vines need renewal.

That single decision is why Petrus has such old vines and a reminder that scarcity value is often the product of specific historical choices rather than an inherent, permanent feature of a vineyard.

6. The vintages that define Petrus

Petrus has a settled list of legendary vintages that recur across critical assessments and auction records: 1929, 1945, 1947, 1961, 1964, 1982, 1989, 1990, 2000, 2005, 2009, and 2010. Robert Parker awarded a perfect 100-point score to nine of these, including 1921, 1929, 1947, 1961, 1989, 1990, 2000, 2009, and 2010.

Just as notable is what does not exist. In 1956, 1965, and 1991, the estate judged the harvest unfit for release and declared no wine at all under the Petrus name, a decision made easier by the absence of a second label to absorb the shortfall.

  • 1947 and 1961: among the most sought-after vintages in Bordeaux, commanding auction prices as high as £12,500 a bottle for exceptional examples.
  • 1990 and 2000: modern benchmark vintages combining critical acclaim with more available stock than the pre-war years.
  • 2009 and 2010: back-to-back perfect-score vintages that remain the most liquid entry points into top-tier Petrus today.

7. Petrus has no second wine

Petrus produces an average of just 30,000 bottles a year, roughly 2,500 cases, from a stringent pre-assemblage selection process. Parcels that fail to meet the required standard are simply rejected from the Grand Vin. Unlike most Bordeaux estates, there is no second label to catch that declassified fruit and sell it under a different name.

The consequence is a permanently constrained supply that cannot expand even in generous vintages, because quality control operates as a hard ceiling rather than a sorting exercise. Total annual output stays essentially fixed regardless of vineyard conditions.

8. Priced above every First Growth

Petrus does not need classified status to command the highest price in Bordeaux. In the 2025 Liv-ex Classification, which ranks wines by trading value over the preceding year, Petrus placed fourth overall at an average price above £31,000 a bottle, the highest of any Bordeaux wine included.

  • Petrus: fourth in the 2025 Liv-ex Classification, ahead of every First Growth.
  • Chateau Latour: ranked 36th in the same table.
  • Chateau Lafite Rothschild: ranked 39th, despite its own strong brand recognition.

Alongside neighbouring Le Pin, whose own production runs to just a few thousand bottles a year, Petrus leads a small group of Pomerol wines that consistently outprice the classified Medoc estates. Wine-Searcher has separately placed Petrus around sixth among the world’s most expensive wines across all producing countries, behind only a handful of ultra-rare Burgundies, proof that in this corner of Bordeaux, reputation has entirely decoupled from official rank.

9. Petrus skips En Primeur

Most Bordeaux estates release new vintages as futures during the En Primeur campaign each spring, selling wine still ageing in barrel. Petrus, through the Moueix negociant house, has repeatedly declined to show at the standard early tastings, presenting its wines later once fermentation and ageing have progressed further.

This mirrors Chateau Latour’s 2012 decision to withdraw from En Primeur entirely and release only when a wine is ready to drink. For investors, the practical effect is that positions in Petrus are built on the post-release secondary market through merchants, brokers, or auction.

10. From Le Pavillon’s corner table to the International Space Station

Petrus became a status symbol in New York during the 1960s, largely through restaurateur Henri Soule, whose Le Pavillon served it to a clientele that reportedly included shipping magnate Aristotle Onassis. Wine writer Alexis Lichine observed at the time that ordering Petrus had become as much about signalling status as appreciating the wine itself.

That cultural pull has never really faded. In 2021, a bottle of Petrus 2000 that had spent 14 months aboard the International Space Station as part of a scientific ageing study sold privately through Christie’s for approximately $1 million, far above the price of an identical bottle that stayed on earth. A reminder if one were needed that Petrus’s mythology now carries its own commercial weight, separate from any single vintage’s technical merits.

Where Petrus sits in a fine wine portfolio

Petrus makes the case that reputation, not classification, ultimately sets price in Bordeaux. Its combination of unrepeatable terroir, permanently capped output, and disciplined ownership has produced a wine that trades above every First Growth without holding any official rank at all. That is a powerful signal for long-term value, but it comes paired with genuine concentration risk: a market this thin, built around roughly 30,000 bottles a year, can move sharply in either direction on comparatively modest shifts in demand.

For most portfolios, Petrus works best as a concentrated, high-conviction position rather than a core holding, sitting alongside broader exposure to classified Bordeaux, Burgundy, and other Pomerol names such as Le Pin. Its scarcity is precisely what makes it valuable, and precisely why it should never carry outsized weight on its own.

FAQ: Investing in Chateau Petrus

Is Chateau Petrus a good wine investment? 

Petrus has a strong long-term track record and currently trades as the highest-priced Bordeaux on Liv-ex, ranking fourth in the 2025 Classification ahead of every First Growth. Its appeal rests on genuine scarcity, roughly 30,000 bottles a year with no second wine, but that same scarcity means thinner trading volumes than more widely available First Growths.

How much does a bottle of Petrus cost? 

Prices vary enormously by vintage and condition. Its current average Market Price on Wine Track sits at £29,700 per 12×75 case.

Is Petrus easy to buy and sell?

Petrus trades less frequently than the classified First Growths simply because so little of it exists, but strong global demand and its position in the Liv-ex Classification indicate a functioning, active secondary market. Investors should expect wider bid-offer spreads than for higher-volume Bordeaux names.

What is the best Petrus vintage to buy?

The 2009 and 2010 vintages, both awarded perfect scores by Robert Parker, are generally seen as the most accessible entry points into top-tier Petrus today, combining critical acclaim with comparatively more available stock than pre-war legends like 1947 or 1961.

How does Petrus compare to Le Pin as an investment?

Petrus and Le Pin are the two Pomerol wines that consistently outprice the classified Medoc estates, though Le Pin’s production is smaller still, around 6,000 to 12,000 bottles a year depending on vintage. Petrus offers a longer track record and slightly deeper trading history, while Le Pin trades on even greater rarity.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.
Categories
News

Harvest 2026: Europe’s earliest picking on record as heat reshapes the vintage

Champagne, Bordeaux and Burgundy are all tracking towards record-early picking dates, while Italy and Spain report similar acceleration. Growers are weighing smaller yields against a scramble to preserve freshness in the fruit.

  • Champagne is on course for the earliest harvest start in its recorded history, with picking expected from 15 August.
  • The wine harvest 2026 will be smaller across France, with Bordeaux facing losses of 20% or more and Champagne capping output at 250 million bottles.
  • Italy and Spain entered the summer with stronger water reserves, and currently report better fruit condition than their French counterparts.

Europe is picking its earliest harvest on record, and the calendar shift matters to collectors for one reason above all: it comes attached to a materially smaller crop. Three heatwaves between May and July 2026 compressed the growing season across almost every major appellation, pulling picking forward by a week to a fortnight. This piece sets out what each region is reporting, and what a short vintage does and does not tell a buyer at this stage.

A summer of three heatwaves reset the calendar

France recorded its hottest day since records began on 24 June 2026, when the national average temperature reached 30°C, beating the 29.4°C set in July 2019 (Meteo-France, June 2026). Individual towns passed 43°C. That was the most severe of three heatwaves to cross the country between May and July, the third of which began on 6 July and pushed the southwest to 38-40°C.

The relevant consequence is supply. Compressed growing seasons concentrate sugars quickly, and they tend to arrive alongside reduced volume, which is the pattern every French region is now reporting.

Champagne: The earliest harvest on record

Champagne expects picking to begin around 15 August, with warmer sites such as Montgueux potentially starting as early as 10 August. That would eclipse the previous record of 17 August, set in 2020. The 2003 season, shortened by both April frost and the August heatwave, began on 18 August. Before the modern era, Champagne’s earliest documented harvest was 20 August 1822.

Jean-Baptiste Lecaillon of Louis Roederer attributed the Montgueux timing to site conditions, describing it as “an exceptionally sunny site”.

The acceleration follows spring frosts that cut early buds by around 40% region-wide, with losses ranging from 25% in the least affected areas to 85% in the Aisne. Summer heat then drove a rapid burst of ripening.

The Comite Champagne has responded by capping the 2026 yield at 8,800 kg/ha, equivalent to roughly 250 million bottles. Key figures:

  • 8,800 kg/ha, a 2.2% reduction on 2025’s 9,000 kg/ha limit.
  • Approximately 250 million bottles, against 266 million bottles of global Champagne shipments in 2025.
  • The tightest cap since 2020, when the Covid-disrupted vintage was held to 8,000 kg/ha, or fewer than 230 million bottles.
  • Actual crop volume is expected to fall by around 10% year on year, a separate measure from the appellation cap.

The Comite Champagne said the decision “aims to gradually rebalance stock, while preserving the economic viability of the vineyards and maintaining quality standards.” Growers now face a balancing act in the final weeks: ensuring sugar accumulation does not outpace flavour development in the berries.

Bordeaux: Comparisons to the searing 2003 vintage

Bordeaux is running hot enough that merchants are reaching for 2003 as a benchmark. Ground temperatures in some vineyards have approached 50°C, and industry estimates point to yield reductions of 20% or more.

Cremant grapes destined for sparkling wine may be picked from the beginning of August, with the main harvest expected mid-August, well ahead of the historical September norm.

Not every parcel is under equal stress. Sylvie Cazes, owner of Chateau Chauvin and president of St-Emilion Grand Cru Classe, reported that blue clay parcels retained deep water reserves from a wet winter. Producers on those soils expect smaller yields accompanied by concentrated fruit, provided the vines avoid further drought stress before picking.

Burgundy: Water is the primary concern

Burgundy’s harvest is pencilled in for around 20 August, a marked shift from the region’s traditional early-to-mid September start. Growers there frame the challenge differently to their counterparts further south.

“Our biggest concern isn’t the heat itself, but the lack of water,” said Laurent Delaunay, chairman of the Bourgogne wine board (BIVB). No official yield forecast has been released. Significant declines are widely anticipated across the Cote d’Or, which matters given the region’s existing undersupply in Premier Cru and Grand Cru white wines.

Italy: An early, broadly promising vendemmia

Italy’s 2026 vendemmia is arriving ahead of schedule in nearly every major region, and the quality picture reads more encouraging than in France. That distinction matters to buyers, because volume and quality are diverging between the two countries this year. Reports collected in early August (Italia a Tavola) show:

  • Piedmont: Fontanafredda has begun picking base wine for Alta Langa, roughly 7-10 days earlier than 2025, following abundant winter and spring rainfall.
  • Franciacorta: Montina expects to harvest between 10 and 13 August, with south-eastern sites starting 5-6 August. Hail has cut expected yields there by 10-18%.
  • Friuli: Le Vigne di Zamo is targeting the week of 10-16 August, starting with Sauvignon, and reports volumes in line with average. Le Monde and La Ponca report good balance across sugar ripeness, acidity and aromatics.
  • Tuscany: in Chianti Classico, early veraison has pulled timing forward by 7-10 days, with volumes in line with recent vintages.

Most Italian regions benefited from strong winter and spring rainfall, which built the water reserves needed to carry vines through summer heat without the acute stress seen in parts of France.

Spain: A centenarian estate’s earliest picking on record

Spain produced the summer’s most striking single data point. In Catalonia’s Penedes, sparkling wine producer Juve & Camps began harvesting on 27 July at its Espiells estate, the first time in the winery’s hundred-year-plus history that picking has started in July. Winter rainfall of 630mm had replenished soil moisture ahead of the summer heat. The estate also introduced night harvesting for the first time, keeping fruit cooler in transport to reduce oxidation and protect acidity and aromatics.

What a short vintage does and does not tell buyers

The throughline across regions is lower volume with quality still genuinely undecided. Champagne’s tightened cap, Bordeaux’s potential 20%-plus shortfall and Burgundy’s likely reduction all point towards less 2026 wine reaching the market. Whether that translates into anything at the price level is a separate question, and one this early in the season nobody can answer honestly.

The more useful signal for buyers is where the quality is likely to land. Rainfall across France in the final weeks before picking will do most of the deciding. Italy and Spain, carrying stronger winter water reserves into August, currently look better placed to convert an early harvest into a fine one.

WineCap will continue to track harvest reports as picking gets underway across Europe’s fine wine regions over the coming weeks.

FAQ: The 2026 wine harvest

When does the 2026 Champagne harvest start?

Picking is expected to begin around 15 August 2026, with warmer sites such as Montgueux potentially starting on 10 August. That would make it the earliest start in Champagne’s recorded history, beating 17 August 2020. Before the modern era, the earliest documented Champagne harvest was 20 August 1822.

Why is the 2026 European wine harvest so early?

Three heatwaves crossed France between May and July 2026, including the country’s hottest day on record on 24 June, when the national average reached 30°C. Sustained heat accelerates ripening and compresses the growing season. Across most major appellations, picking has moved forward by a week to a fortnight against recent averages.

How much smaller is the 2026 crop?

Champagne has capped output at 8,800 kg/ha, roughly 250 million bottles, with actual volume expected to fall around 10% year-on-year. Bordeaux estimates point to reductions of 20% or more. Burgundy has issued no official forecast, though declines are widely anticipated.

Will 2026 be a good vintage?

Too early to say, and any confident answer at this stage should be treated with caution. Italian producers report balanced sugar, acidity and aromatics after strong winter and spring rainfall (Italia a Tavola, August 2026), while French regions face drought stress that rainfall in the final weeks before picking may or may not relieve. Quality assessments will not be meaningful until fruit is in the cellar.

Does a smaller harvest mean prices will rise?

Not necessarily, and the two are not directly linked. Reduced supply is only one input into secondary market pricing, alongside demand, currency, existing stock levels and broader market conditions. The fine wine market fell roughly 30% from its October 2022 peak over nearly three years, so a short crop is arriving into a market still working through that adjustment.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.
Categories
News

Champagne caps 2026 harvest at its lowest yield since the pandemic

  • Champagne’s marketable yield for 2026 has been set at 8,800kg/ha, equivalent to around 250 million bottles, its lowest level bar 2020’s Covid-affected harvest.
  • This is the fourth consecutive annual reduction, down from 11,400kg/ha in 2023, as growers and houses work to rebalance stock built up during the post-pandemic slowdown.
  • The cut lands just as Champagne’s prestige cuvee segment shows early signs of stabilising, with the Liv-ex Champagne 50 index up 1.7% from its August 2025 low.

Champagne’s growers and houses have agreed to cap the region’s 2026 marketable yield at 8,800kg per hectare, equivalent to roughly 250 million bottles once pressed and bottled. Set annually by the Comite Champagne (CIVC), the region’s joint body for growers and houses, the figure is the lowest since 2020, when Covid-related demand shock forced a cap of 8,000kg/ha. It confirms a fourth straight year of tightening supply, and it arrives at a moment when the region’s secondary market, particularly for prestige cuvees, is showing its first tentative signs of finding a floor after three difficult years.

A fourth straight year of tighter yields

The 2026 figure continues a steady decline from the 12,000kg/ha permitted in 2022. Growers were capped at 11,400kg/ha for 2023, 10,000kg/ha for 2024, a reduction of more than 12%, and 9,000kg/ha for 2025. This year’s 8,800kg/ha marks a smaller step down, but the direction of travel has been consistent for half a decade.

The decision was reached collectively by Champagne’s more than 16,000 growers and 350 houses at their annual meeting with the Comite Champagne in Epernay. David Chatillon, co-president of the Comite Champagne, described the model as one built to adapt to “market realities without losing sight of what matters most: preserving the appellation’s value over the long term.” His co-president Maxime Toubart called the figure “a measured decision, mindful of both the reality of the vineyards and the future of the industry.”

The 2026 growing season has itself been a difficult one, marked by spring frost, an extreme June heatwave and, more recently, drought, with conditions varying sharply across the appellation’s vineyards. Harvest is expected to run from 20 to 25 August, some 10 to 15 days earlier than usual, putting 2026 on course to be among the earliest starts in the region’s history.

Why growers and houses are constraining supply

Champagne’s yield system exists precisely to avoid the kind of oversupply that has weighed on other wine regions. Shipments reached 107.1 million bottles in the first half of 2026, up 1.2% year-on-year and driven by exports, which would put the region on course for roughly 269 million bottles by year-end if the trend holds, slightly ahead of 2025’s 266 million but still below the 271 million shipped in 2024.

That modest shipment growth follows several years in which the market absorbed less Champagne than houses had produced, leaving stock levels elevated. Cutting the marketable yield is the CIVC’s mechanism for bringing future supply back in line with realistic demand, rather than allowing surplus wine to accumulate and pressure prices downward.

What tighter yields could mean for Champagne prices

The cut lands at a delicate moment for the region’s fine wine segment. Prestige cuvee export shipments fell 17% in 2025 to 7 million bottles, a million below the 10-year average, while UK volumes of prestige cuvees dropped to just 480,000 bottles, their lowest level in a decade. Release prices for the latest cycle of major prestige cuvees, including Cristal, Dom Perignon, Krug Vintage and Salon, came in an average of 16.2% below their previous release, with Salon down 39% and Cristal down 23.8%.

That correction has weighed on the secondary market too. The Liv-ex Champagne 50 index fell 4.2% in 2025 and remains 33.1% below its September 2022 peak. But there are early signs of a turn. The index has risen 1.7% since its August 2025 low, driven by Taittinger Comtes de Champagne Blanc de Blancs Grand Cru 2011, Louis Roederer Cristal 2014 and Krug Vintage Brut 2004.

A shrinking future harvest does not change prices overnight, since 2026’s grapes will not reach the market as finished wine for several years. But a fourth consecutive supply cut reinforces the scarcity argument for Champagne just as demand appears to be stabilising.

FAQ: Champagne’s 2026 yield cut

How much has Champagne’s 2026 yield been cut by?

The 2026 marketable yield was set at 8,800kg/ha, down slightly from 9,000kg/ha in 2025 and more than 22% below the 11,400kg/ha permitted in 2023. It is the lowest yield since the pandemic-affected 2020 harvest.

Why does Champagne limit its yield each year?

The Comite Champagne sets a marketable yield annually to match future supply to realistic demand, avoiding the stock overhang that can pressure prices. The decision is made jointly by growers and houses rather than by any single producer.

Does a lower harvest mean higher Champagne prices now?

Not immediately. Grapes from the 2026 harvest will not reach the market as finished Champagne for several years, so the near-term effect is limited. The cut instead reinforces the longer-term scarcity case for the region.

How has the Champagne secondary market performed recently?

The Liv-ex Champagne 50 index fell 4.2% in 2025 and remains well below its September 2022 peak, but it has risen 1.7% since an August 2025 low, and mature vintages such as Dom Perignon 2015 have begun trading above their release price again.

Is prestige Champagne still a reasonable investment category?

Prestige cuvee shipments and release prices both fell sharply through 2025, reflecting a genuine correction rather than a temporary dip. Investors considering the category should focus on scarce, mature vintages with an established trading history rather than the newest releases.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.
Categories
News

Louis Roederer’s Burgundy deal points to where fine wine capital is heading

  • Louis Roederer has completed its first-ever Burgundy acquisition, buying Domaine Pierre Damoy and its nearly eight hectares of Grand Cru Gevrey-Chambertin vineyards.
  • The deal lands as Burgundy Grand Cru land hits record prices even as the region’s secondary bottle market has cooled.
  • It also reinforces a wider trend of Champagne houses diversifying into fine wine estates elsewhere.

Louis Roederer has completed its acquisition of Domaine Pierre Damoy, giving the family-owned Champagne house a foothold in Burgundy for the first time in its 250-year history. The deal, first flagged in April and finalised this month, brings nearly eight hectares of Grand Cru vineyard – primarily in Chambertin, Chambertin-Clos de Beze and Chapelle-Chambertin – into the Roederer Collection. Financial terms were not disclosed.

CEO Frederic Rouzaud called the timing – Roederer’s 250th anniversary year – meaningful, and pledged to preserve Domaine Pierre Damoy’s identity rather than fold it into a house style. The estate also brings Clos Tamisot, a Gevrey-Chambertin monopole, into the group.

Grand Cru land: a scarcer, richer asset

The transaction lands at a moment when Burgundy vineyard land is setting records. Investors paid up to €30m per hectare for the very best individual parcels in 2025, while Premier Cru Chardonnay averaged €2.7m per hectare and Premier Cru Pinot Noir climbed 11% to €1.15m. Grand Cru land is effectively a closed asset class: every hectare is fully planted and no new Grand Cru can be created, so ownership changes are the only way in.

That scarcity is worth separating from the bottle market. Burgundy prices in the secondary market have fallen 15% on average over the past year – the sharpest pullback of any major region. Roederer’s purchase is a reminder that land and bottles can move on different clocks: even as short-term secondary pricing softens, buyers with a long horizon are paying up for irreplaceable terroir.

A hedge against a cooling Champagne market

The deal also fits a broader diversification pattern among Champagne’s leading houses. Global Champagne shipments fell to 266 million bottles in 2025, a third consecutive annual decline, and the Comite Champagne has cut the 2026 harvest cap to 250 million bottles to manage oversupply amid what it calls an “unstable and unpredictable” market. First-half 2026 shipments ticked up 1.2%, but the broader trend remains one of a maturing, cyclical market.

Roederer already spreads its risk across Bordeaux (Chateau Pichon Longueville Comtesse de Lalande), the Rhone (Delas Freres), Provence (Domaines Ott), Portugal (Ramos Pinto) and California. Burgundy was the conspicuous gap in that portfolio, and closing it now reads as much like capital rotation as it does anniversary sentiment.

Two boom-bust regions, two different portfolio roles

Zoom out to the secondary market and Burgundy and Champagne have followed a strikingly similar arc: both rode the 2020–2022 bull run to record highs, and both have since given much of it back. The Liv-ex Burgundy 150 fell 34% from its September 2022 peak to its low in August 2025; the Liv-ex Champagne 50 fell 33.1% over almost the same window.. Both have since edged up from their lows, suggesting the correction has moved into a steadier consolidation phase across both regions.

The similarity in magnitude masks a difference in character. Burgundy’s swings are driven by extreme scarcity: tiny production, fragmented ownership and critic-led demand for specific parcels, which is exactly why Grand Cru land keeps setting price records even as bottle prices correct. That makes it the higher-return, higher-volatility end of a fine wine portfolio – closer to a concentrated bet on irreplaceable terroir than a diversified holding. 

Champagne, by contrast, draws its resilience from brand equity and genuine end-consumer consumption rather than collector speculation; Liv-ex has pointed to strong liquidity and real drinking demand as reasons the Champagne 50 has held up better than the broader market through the downturn. That makes Champagne the more defensive, liquid allocation – prized for stability and brand strength rather than outsized upside.

Roederer’s move captures both roles in one transaction: a Champagne house whose own brand equity (built on Cristal) throws off the capital to buy into Burgundy’s scarcer, more volatile upside, at a moment when both regions are still working through the same correction.

What it means for investors

For fine wine investors, the deal reinforces two things: Burgundy Grand Cru remains one of the few genuinely scarce assets in the wine world, attracting strategic capital even as short-term bottle pricing corrects; and Champagne houses with balance sheets to deploy are treating estate acquisitions elsewhere as a way to diversify away from a shipment cycle that has now turned down three years running. A pullback in Burgundy’s secondary market, paired with rising institutional appetite for the region’s land, is the kind of divergence worth watching for entry points – and a reminder that a well-built portfolio typically holds both: Burgundy for scarcity-driven upside, Champagne for brand-backed stability.

WineCap’s Wine Track data shows the scale of Burgundy’s recent price correction alongside the region’s enduring scarcity value. Speak to one of our wine investment experts to see how this fits into a diversified portfolio. Schedule your free consultation today

Categories
News

Fine wine’s price correction meets a new generation of collectors

  • 97% of UK and US wealth managers expect demand for fine wine to remain strong, the highest result among other collectibles.
  • Fine wine prices have fallen around 25% since their 2022 peak but have outperformed several rival luxury collectibles over the past decade.
  • Independent research from Areni Global and Chubb points to younger, digitally engaged collectors as the main source of future demand growth.

Fine wine has spent the past three years in correction, with prices well below their 2022 peak and trading activity increasingly selective. One measure has not followed prices down: expected demand compared to other collectibles.

WineCap’s Wealth Report shows fine wine continues to rank as the collectible category for which wealth managers continue to expect the most client demand, in both the UK and US, through every year of the downturn. New research from Knight Frank, Areni Global and insurer Chubb may suggest why – the market’s buyer base is changing, and its demand cycle is becoming increasingly detached from its price cycle.

Prices down, but the decade record holds

Knight Frank’s Wealth Report 2026 captures both sides of the current market. Over the past decade, the Liv-ex 100 rose 34.1%, ahead of classic cars (31.3%) and well ahead of coloured diamonds (3.1%). Regional performance within that measure was stronger still: Burgundy gained almost 106% and Italy nearly 61% over the past ten years. 

However, the shorter-term picture reverses that ranking. Since its 2022 peak, the Liv-ex 100 has fallen 24.7%, including a 2.5% decline in 2025 alone, while cars, diamonds and watches all delivered better five-year returns. Knight Frank’s broader gauge, the Knight Frank Luxury Investment Index (KFLII) – a weighted basket of ten collectible classes – closed 2025 down just 0.4% and remains up 38.6% over the decade, meaning wine underperformed the composite on both timeframes even as it beat individual rivals over ten years.

Knight Frank singles out Tuscany as one of the market’s clearer value opportunities: labels such as Sassicaia and Tignanello continue to trade at roughly half the price of comparable Burgundy and Bordeaux despite similar critic scores. The report expects the gap to keep shaping demand into 2026, alongside uncertainty over US tariff policy given America’s weight as a buyer base. Elsewhere in the KFLII basket, 2025 was a stronger year: the WatchCharts Overall Market rose 5.1% (Patek Philippe’s index up 12.1% against Rolex’s 4.6%), fancy colour diamonds held broadly stable against a struggling wider diamond trade, and Hermes Birkin and Kelly bags slipped just 0.2%, with demand rotating toward worn “beater” bags in the US$6,000-US$9,000 range favoured by younger buyers – a demand-side pattern that somewhat mirrors what’s happening in fine wine.

Wealth managers still rank wine the top demand story

WineCap’s Wealth Report has tracked wealth managers’ expectations for client demand across major collectible categories since 2023. Fine wine has led every year. In the UK, between 94% and 97% of wealth managers surveyed have expected demand for fine wine to increase each year since 2023, ahead of watches (78–90%) and classic cars (22–70%, the most volatile reading in the set). 

The US shows the same pattern: after dipping to 84% in 2024, expected demand for fine wine climbed to 97% in 2026, again the highest-ranked category, with classic cars at 71% and categories such as stamps (69%) and antique furniture (60%) trailing well behind. Falling prices would typically be expected to soften that kind of forward-looking confidence; instead, wine’s demand score sits at or near a four-year high in both markets heading into 2026.

A younger, digitally native buyer base

Areni Global, the wine-focused think tank, has offered a likely explanation. Its February 2026 study, “The New Fine Wine Consumer: How people under 40 find their way into fine wine” — produced with Berry Bros & Rudd, 67 Pall Mall, Vinophiles Society and the Young Members Circle of the International Wine and Food Society – found strikingly consistent collecting behaviour among under-40s across London, Paris, New York, Hong Kong, Shanghai and Singapore.

The research identified a “collector’s spark” window between ages 26 and 35: those who enter the market in this window are far more likely to keep collecting for decades, while those who haven’t entered by 40 largely never do. Discovery increasingly runs through peer networks and digital communities rather than family inheritance. “Horizontal discovery,” in co-founder Pauline Vicard’s terms, supported by wine-tech platforms, blockchain provenance tools and a generation that expects the same real-time feedback loops from a wine portfolio that they get from other alternative-asset apps.

Investing in wine, but not insuring it

Chubb’s newly released research into younger affluent consumers reinforced the same generational shift. Surveying “HENRYs” – high earners not yet rich, typically in their 20s to mid-40s with incomes of $250,000 to over $1 million – Chubb found 78% weigh an item’s future value as a top purchasing factor. 

Wine collectors were the most engaged group measured: 81% actively drink from their collections, the highest hands-on rate of any category in the survey, and 45% cited status, prestige and expertise-building as a motivation. Close to half have collected for five years or more, and 21% for a decade-plus – tenure that lines up closely with Areni Global’s 26-to-35 “spark” window.

That conviction, nevertheless, hasn’t translated into cover. More than half of young collectors overall remain uninsured, chiefly because 46% of the uninsured wrongly believe their homeowners’ policy already protects their valuables, while 34% simply don’t see their collection as at risk. 

Fine wine outlook in 2026 and beyond

Taken together, the research points to a fine wine market that is evolving in ways price indices alone cannot fully explain.

Knight Frank’s data shows a market still around 25% below its 2022 peak. Yet WineCap’s Wealth Report shows wealth managers continue to expect stronger demand for fine wine than for any other collectible. Areni Global identifies a growing pipeline of collectors entering the market before the age of 40, while Chubb’s research suggests these buyers are digitally engaged, investment-minded and building collections with a long-term perspective.

None of this means the market is immune to further volatility. Interest rates, currency movements, geopolitical developments and US trade policy will continue to influence prices in the near term.

What the research does suggest is that today’s correction differs from many previous market downturns. Rather than driving buyers away, it has coincided with a generational shift in demand. Fine wine is attracting a new cohort of collectors who view it not simply as a luxury product, but as a long-term alternative asset.

For investors, that may prove to be the more significant trend. Market cycles come and go, but the long-term outlook for any collectible ultimately depends on whether new buyers replace those leaving the market. The combined evidence from WineCap, Knight Frank, Areni Global and Chubb suggests that transition is already underway.

FAQ: Fine wine collecting and investing

Is fine wine an alternative investment?

Yes. Fine wine is considered an alternative investment because it sits outside traditional asset classes such as equities, bonds and cash. Investors buy investment-grade wines with the expectation that their value will appreciate over time, driven by scarcity, global demand and limited production. Unlike financial securities, fine wine is a tangible asset with an established secondary market.

What is a collectible investment?

A collectible investment is a physical asset purchased with the expectation that it will increase in value over time. Examples include fine wine, classic cars, watches, art, rare whisky, coins and stamps. Collectibles typically derive their value from scarcity, provenance, condition and demand among collectors.

Which collectibles are considered investable?

The most established investment-grade collectibles include fine wine, fine art, classic cars, luxury watches, rare whisky, coloured diamonds and certain handbags. These markets benefit from active secondary trading, transparent pricing and strong global demand, although liquidity and risk vary significantly between categories.

Why is fine wine considered an attractive investment?

Fine wine combines several characteristics investors value: limited supply, global demand, transparent pricing, long-term performance and relatively low correlation with traditional financial markets. Because investment-grade wines are consumed over time, supply naturally declines, increasing scarcity for the remaining bottles.

Why do wealth managers recommend fine wine?

Many wealth managers view fine wine as a portfolio diversifier rather than a replacement for traditional investments. It can help reduce concentration risk because its performance is influenced by different factors than equities or bonds. Wine is also a tangible asset with a long history of global collector demand.

What is portfolio diversification?

Portfolio diversification means spreading investments across different asset classes to reduce overall risk. Rather than relying on a single investment, diversified portfolios combine assets such as shares, bonds, property, cash and alternatives like fine wine. If one asset class performs poorly, others may help offset losses.

How does fine wine diversify an investment portfolio?

Fine wine has historically shown relatively low correlation with traditional financial markets. Its value is driven by factors such as production volumes, vintage quality, critic scores and collector demand rather than corporate earnings or interest rates. As a result, many investors use fine wine to complement broader portfolios.

What makes a wine investment-grade?

Investment-grade wines typically come from established producers with proven secondary market demand, limited production and long ageing potential. Regions such as Bordeaux, Burgundy, Champagne, Tuscany and Piedmont dominate the market, although investment opportunities also exist elsewhere.

Why do fine wine prices increase over time?

As investment-grade wines are consumed, fewer bottles remain available for future buyers. Combined with strong global demand and limited annual production, this natural reduction in supply can support prices over the long term. However, values are also influenced by broader economic conditions and collector sentiment.

How does fine wine compare with other collectibles?

Fine wine shares many characteristics with other luxury collectibles, including scarcity and provenance, but differs in having an increasingly transparent global trading market. Unlike watches or art, wine is also a “wasting asset” acting as a tax advantage in the UK.

Who invests in fine wine?

Fine wine attracts a broad range of investors, from private collectors and high-net-worth individuals to family offices and wealth managers. Recent research also suggests younger, digitally engaged collectors are entering the market earlier, viewing fine wine as both a passion asset and a long-term investment.

What risks should fine wine investors consider?

Like any investment, fine wine carries risks. Prices can fluctuate, liquidity varies between wines, and returns are not guaranteed. Investors should also consider storage costs, insurance, provenance and holding periods. Fine wine is generally viewed as a medium- to long-term investment rather than a short-term trade.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.
Categories
News

Stronger US dollar puts fine wine’s currency independence in focus

  • WineCap’s 2026 Wealth Report found 98% of surveyed US wealth managers see fine wine’s independence from the US dollar as important.
  • The dollar is strengthening again, driven by geopolitical risk, resilient US data and expectations that rates will stay higher for longer.
  • A stronger dollar can lower the acquisition cost for US buyers of euro- and sterling-priced wine, but fine wine’s long-term value still rests on scarcity, provenance and collector demand.

The US dollar has regained momentum amid renewed geopolitical uncertainty, resilient US economic data and expectations that American interest rates could remain elevated for longer.

The Dollar Index, which measures the currency against a basket of major peers, has moved back above 101. Performance has fluctuated day to day, but the dollar has strengthened by around 1% over the past month and just over 3% over the past year. Safe-haven demand linked to tensions in the Middle East has provided further support, alongside relatively high US bond yields and a more cautious outlook for Federal Reserve policy.

A stronger dollar has consequences far beyond foreign exchange markets. It can make imports cheaper for US consumers while making American exports less competitive, potentially placing upward pressure on the US trade deficit. It can also raise the burden of dollar-denominated debt in emerging markets and increase the local cost of commodities and other imports for countries whose currencies are weakening.

For fine wine investors, however, the implications are more nuanced.

Fine wine is not globally priced in dollars the way oil and many other commodities are. Its value is shaped principally by scarcity, producer reputation, vintage quality, provenance and demand from collectors around the world. Currency movements affect what investors pay in their domestic currency, but they don’t automatically determine whether the underlying price of a wine rises or falls.

Our survey for the 2026 US Wealth Report found that wealth managers increasingly see this distinction as a core part of fine wine’s investment appeal.

Conviction about fine wine’s currency independence is growing

WineCap’s 2026 Wealth Report asked wealth managers how important it was that fine wine is not pegged to the US dollar.

In total, 98% described this characteristic as either important or very important – maintaining the exceptionally high level recorded in 2025 and rising from 92% in 2024.

fine wine's currency independence

The more notable development is the growing strength of conviction. The share of respondents who considered fine wine’s independence from the dollar “very important” rose from 28% in 2024 to 32% in 2025 and 42% in 2026 – a 50% increase over two years. Only 2% were neutral on the issue in 2026, and none considered it unimportant.

The findings arrive as currency risk becomes a more visible consideration for global investors. Inflation, divergent central bank policies, geopolitical instability and shifting capital flows have driven significant swings across major currencies. 

Against that backdrop, assets whose fundamental value isn’t tied to the monetary policy or exchange rate of a single country may become increasingly attractive as portfolio diversifiers.

Why a stronger dollar matters globally

The dollar occupies a unique position in the international financial system – widely used in cross-border trade, commodity pricing, foreign exchange reserves and international borrowing. Changes in its value, therefore, have an outsized effect on the global economy.

When the dollar rises, goods imported into the US become cheaper in dollar terms, helping to ease some imported inflation; American consumers and businesses can buy more from overseas for the same money. The opposite holds elsewhere: a weakening domestic currency makes dollar-priced imports more expensive, potentially adding to inflation in economies that depend heavily on imported energy, food or industrial materials.

Emerging markets are particularly exposed. Governments and companies there often borrow in dollars while earning revenue in local currencies, so when the dollar appreciates, the domestic-currency cost of servicing that debt rises. The IMF has found that emerging economies are especially vulnerable given the dollar’s dominant role in both trade invoicing and cross-border debt – roughly 40% of world exports and around half of international debt securities are dollar-denominated, exposing these economies to exchange-rate volatility largely beyond their control.

Commodities can also face downward price pressure when the dollar strengthens, since many are quoted in dollars and become costlier for buyers using other currencies. That said, supply shocks, geopolitics and the economic cycle can outweigh the currency effect – oil’s recent gains amid Middle East tensions, despite a firmer dollar, illustrate why the relationship isn’t mechanical.

The effect on trade is similarly directional. A stronger currency tends to make imports cheaper and exports more expensive, which can widen the US trade deficit – though the actual outcome also depends on domestic demand, global growth, tariffs and how quickly businesses and consumers adjust to exchange-rate changes.

Fine wine follows different fundamentals

Fine wine differs from conventional commodities in several important respects. It isn’t a standardised, interchangeable product – each wine is tied to a particular producer, region and vintage, and available supply shrinks as bottles are consumed. Two wines from the same appellation can perform very differently depending on critical reception, production volumes, age, provenance and collector demand.

The market is also geographically diverse. Many of the most important investment-grade wines are produced in France and Italy, while London remains a key centre for international secondary market trading. Wines may therefore be priced in sterling or euros even when the end buyer is based in the US, Asia or the Middle East.

None of this makes fine wine immune to currency movements – exchange rates can affect demand, merchant margins, international trade and the timing of purchases. However, it does mean a stronger dollar doesn’t automatically push the underlying price of a case of Bordeaux, Burgundy or Champagne in either direction. The wine’s value continues to reflect conditions within its own market.

Does today’s dollar strength create a buying opportunity?

For US investors, a stronger dollar can improve purchasing power when acquiring fine wine priced in sterling or euros. When the dollar rises against the euro, an American buyer needs fewer dollars to purchase the same wine, provided its local market price hasn’t changed. This essentially means a more attractive entry point without requiring the underlying wine price to fall.

The current picture is mixed rather than uniform. The dollar has strengthened broadly over the past month and has recently benefited from safe-haven demand, making clearer gains against the euro, which has been pressured by geopolitical and energy concerns. Sterling has shown greater resilience, recovering some ground against the dollar through early July. 

American buyers may therefore have a more obvious currency advantage sourcing euro-denominated wines than sterling-priced stock right now. The opportunity also depends on the comparison window: the dollar may be stronger over one month but weaker against a particular currency over a shorter period.

Transaction costs, storage, tax, shipping and merchant pricing matter too – a favourable exchange rate alone doesn’t make an individual wine attractive. The more relevant point is that currency strength can give investors added flexibility. US collectors may use periods of dollar appreciation to acquire European stock more efficiently, particularly when underlying wine prices are stable or older vintages offer relative value.

Currency is an entry-point consideration

Fine wine’s independence from the dollar shouldn’t be confused with an expectation that it will rise whenever the dollar strengthens. A favourable exchange rate can lower a US investor’s acquisition cost, but subsequent returns still depend on the wine itself – scarcity, condition, producer demand, market liquidity and the price paid remain the more important long-term considerations.

The same principle applies in reverse: a US investor holding wine priced or traded in sterling may benefit from currency appreciation when converting value back into dollars, but foreign exchange movements can also work against them. Currency represents an additional layer of portfolio performance, not the underlying investment case.

Our Wealth Report findings suggest wealth managers increasingly understand that distinction. Almost all respondents already considered fine wine’s lack of a dollar peg important in 2025; the development in 2026 is the rise in those who regard it as very important. It seems that amid greater uncertainty around inflation, interest rates and international capital flows, wealth managers are placing more weight on assets whose value is supported by their own supply-and-demand dynamics.

A stronger dollar may currently allow some US investors to buy European fine wine more competitively. But the broader appeal lies in the fact that fine wine doesn’t depend on the dollar continuing to rise. Its long-term value remains rooted in something more specific: a finite supply of sought-after wines and sustained demand from a global collector base.

FAQ: Fine wine and US dollar

Is fine wine pegged to the US dollar?

No. Fine wine isn’t a globally dollar-priced commodity like oil. Its value is driven by scarcity, producer reputation, vintage quality, provenance and collector demand, not by a single currency. 

How does a stronger US dollar affect fine wine prices?

A stronger dollar changes what a wine costs a buyer in their home currency and can affect merchant margins and purchase timing, but the wine’s own market – driven by scarcity and demand – still sets its value.

Why do wealth managers care about fine wine’s currency independence?

It offers portfolio diversification away from assets whose value is tied to US monetary policy or the dollar’s exchange rate. The share of wealth managers calling this “very important” rose from 28% in 2024 to 42% in 2026, a 50% increase, as currency volatility has become a bigger concern for global investors.

Is now a good time for US investors to buy European fine wine?

A stronger dollar can lower the acquisition cost of euro- and sterling-priced wine for US buyers. Currency is only an entry-point advantage, though – it doesn’t determine long-term returns.

What currency is fine wine priced in?

Fine wine is most commonly traded in sterling and euros, reflecting London’s role as a secondary-market trading hub and the concentration of top producers in France and Italy, even when the end buyer is based in the US, Asia or the Middle East.

Does currency risk affect fine wine investment returns?

Yes, but as an additional layer on top of the investment case, not the case itself. Exchange-rate moves affect what an investor pays or receives when converting value back to their home currency, while long-term returns depend on scarcity, condition, provenance and collector demand.

What is the WineCap Wealth Report?

It’s WineCap’s annual survey of wealth managers on fine wine as an asset class, tracking sentiment on topics including currency independence, demand outlook and portfolio allocation. The 2026 edition found 98% of respondents view fine wine’s independence from the dollar as important, up from 92% in 2024.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.
Categories
News

The top 20 fine wine performers of H1 2026 reveal a market returning to fundamentals

  • Back-vintage Bordeaux dominated H1 2026, with mature vintages from 2013, 2015, 2016 and 2017 outperforming newer releases as investors prioritised proven quality and value.
  • Sauternes was one of the standout categories of the first half, with three sweet wines ranking among the top six performers.
  • The market rewarded fundamentals over speculation, with iconic producers across Bordeaux, Burgundy, Tuscany, the Rhone, Napa Valley and Chile delivering the strongest returns of H1 2026.

The best-performing fine wines of the first half of 2026 tell a story that extends far beyond individual price movements. While headlines during the first six months of the year focused on macroeconomic uncertainty, the Bordeaux 2025 En Primeur campaign and shifting global trade conditions, the secondary market rewarded a consistent set of characteristics: proven vintages, established producers, attractive pricing and scarcity.

The top 20 performing wines of H1 span Bordeaux, Burgundy, the Rhone, Tuscany, Napa Valley and Chile, demonstrating that opportunities have emerged across the broader market – diversity acting as a reassuring sign of recovery. 

Several of these wines also delivered returns that comfortably exceeded those of many mainstream investments during the same period. While broad equity indices posted solid single-digit gains in H1 2026, seven wines in the top 20 appreciated by more than 25%. The comparison highlights an important distinction: although the fine wine market as a whole remained relatively subdued, careful wine selection generated exceptional returns.

Bordeaux leads H1’s top performers with back vintages

Bordeaux accounted for nine of the top 20 performers, making it comfortably the strongest represented region. More revealing, however, is which Bordeaux wines appeared in the rankings.

The list is dominated by back vintages rather than recent releases. Lafleur 2016 gained 31.8% during H1, Pavie 2016 rose 29.7%, Haut-Bailly 2016 climbed 29.6%, while Grand-Puy-Lacoste 2013 and Pavillon Rouge 2013 each posted gains of  25% or above. Elsewhere, Clarence Haut-Brion 2015, La Conseillante 2017 and Haut-Bailly 2017 also ranked among the year’s strongest performers.

This is the same trend that became increasingly apparent throughout the Bordeaux 2025 En Primeur campaign. Although the vintage received widespread critical acclaim and was released at historically attractive prices, buyers repeatedly compared new releases with outstanding back vintages already available on the secondary market. Where price differences were insufficient, investors often chose the mature alternative.

Recent Liv-ex data suggests this preference has continued beyond En Primeur. In June, almost every Bordeaux 2016 included in the Fine Wine 100 index rose in value, making 2016 the strongest-performing Bordeaux vintage year-to-date.

Top performing wines H1 2026

Sauternes quietly became one of the year’s standout performers

Perhaps the biggest surprise in the rankings is the dominance of sweet Bordeaux.

Chateau Climens 2012 topped the entire list after rising an exceptional 66.1% during the first half of the year, while Chateau Coutet 2019 followed in second place with a gain of 33.3%. Chateau Rieussec 2018 also appeared in sixth place with a 28.5% increase in value.

Although Sauternes represents only a small segment of the secondary market, its presence at the very top of the rankings reflects a broader improvement in demand for wines that have long traded below their intrinsic quality. Many leading Sauternes estates remain available at prices that compare favourably with similarly-rated dry wines from Bordeaux or Burgundy, while production volumes and long ageing potential continue to underpin scarcity.

The Liv-ex Sauternes 50 is the best-performing index so far this year, up 2.3%.

Diversification returns across the market

Although Bordeaux dominated numerically, the rankings demonstrated that the list of best performers has broadened considerably compared with recent years during the market’s most prolonged downturn.

Georges Roumier Bonnes Mares 2018 led the Burgundy rankings 25.0%, while Tuscany featured with Soldera Case Basse twice, with the 2011 vintage gaining 28.4% and the 2014 vintage adding 12.9%.

The Rhone contributed three wines: Chapoutier Ermitage Le Pavillon 2015 (+21.1%), Beaucastel Châteauneuf-du-Pape 2017 (+13.3%) and Clos des Papes Chateauneuf-du-Pape 2020 (+13.2%).

Meanwhile, the New World also made a strong showing through Dominus 2017 (+24.3%) and Chile’s Almaviva 2021 (+19.5%).

The diversity of the rankings suggests that recovery is broad-based and the market is increasingly selective rather than simply favouring one region over another. Buyers are allocating capital across multiple geographies, provided individual wines offer compelling combinations of quality, scarcity and relative value.

Top performing wines H1 2026

Producer strength continues to matter

Another recurring feature is the appearance of multiple vintages from the same estates.

Both Haut-Bailly and Soldera appeared twice in the top 20 list. Rather than rotating rapidly between fashionable names, the market appears to be concentrating on producers with consistent international demand and proven secondary market liquidity.

A market rewarding discipline

Taken together, the H1 rankings paint a picture of a market that has become increasingly rational following the correction of the past three years.

The top-performing wines are not speculative releases or newly discovered producers. Instead, they are established labels whose prices have reached attractive entry points relative to their long-term quality and reputation.

During market recoveries, demand first concentrates on wines where value is most apparent. During the first half of 2026, those opportunities were found in mature Bordeaux, overlooked Sauternes, iconic producers from Tuscany and the Rhone, and a select group of blue-chip New World estates.

If the first six months of the year demonstrated anything, it is that investors are once again rewarding fundamentals. Proven quality, scarcity, liquidity and sensible pricing have emerged as the defining characteristics of the market’s strongest performers. For long-term investors, that may prove to be the most encouraging signal of all.

FAQ: Top-performing wines in 2026 so far

Are fine wine prices recovering?

The first half of 2026 showed encouraging signs of improving market sentiment. While gains have been selective rather than broad-based, investors increasingly favoured mature vintages, established producers and wines offering strong relative value, resulting in significant price appreciation for a number of blue-chip labels.

How did Sauternes perform as an investment?

Sauternes combined relative value with increasing investor demand during the first half of 2026. Chateau Climens 2012 was the year’s best-performing wine, while Chateau Coutet 2019 and Chateau Rieussec 2018 also ranked among the top performers, highlighting renewed interest in sweet Bordeaux.

What does the H1 2026 ranking suggest about the fine wine market?

The rankings indicate that investors are prioritising established producers, mature vintages and relative value over speculative buying. Rather than chasing new releases, buyers have focused on wines with proven quality, strong liquidity and attractive entry prices.

Which producers appeared more than once among the top performers?

Several leading estates featured multiple times, including Chateau Haut-Bailly and Soldera (Case Basse). Their repeated appearances suggest that investors continue to favour producers with long-term reputations, consistent quality and strong secondary-market demand.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.