Categories
Learn

Wine investment: The complete 2026 guide

  • Wine investment means buying investment-grade wine, stored in bond, to sell later at a higher price: a long-term, unregulated alternative asset, not a savings product.
  • The Liv-ex 100 index fell 2.5% in 2025 after a three-year correction, and posted signs of stabilisation through the first half of 2026.
  • Realistic planning assumes a five to ten year hold, annual storage and management costs, and full awareness that prices fall as well as rise.

Wine investment is the purchase of a small, tightly defined group of wines with the aim of selling them later at a higher price. This guide explains the full mechanics for UK investors: what qualifies as investment grade, how buying and ownership work, what it costs, what returns the indices actually show, the risks, the tax position, and how to build and eventually exit a first portfolio. 

What wine investment actually is

Wine investment is narrower than wine collecting. An investor buys specific wines, almost always in sealed original cases, stores them professionally, and sells once age and scarcity have moved the price. The wine itself is the asset: there is no dividend, no coupon and no income along the way. Returns come entirely from the difference between purchase and sale price, minus costs.

The market that makes this possible is the secondary market (the trade in wines after their original release), where merchants, brokers and exchanges match sellers with buyers worldwide. London sits at its centre. Liv-ex, the London-based fine wine exchange, provides the price benchmarks the industry works from, and its indices function much like equity indices do for shares.

Scale matters here. This is a boutique market, not a deep one. Fewer than a few hundred wines trade with genuine regularity, and even the most liquid names change hands in cases, not milliseconds. That structure shapes everything that follows: pricing, holding periods, costs and exit routes.

What makes a wine investment grade

Investment-grade wine is defined by demand that outlives supply. A tiny fraction of global production qualifies, and the tests are consistent across regions. WineCap’s article on which types of wine are considered investment-grade treats this in depth; the short version follows.

  • Producer pedigree. The estate has a long record of critic scores and secondary market demand: Bordeaux classed growths, Burgundy’s top domaines, prestige Champagne houses, Tuscany’s leading estates, and a small group of Rhone, Spanish and Californian names.
  • Ageing capacity. The wine improves, or at least holds, for decades. A wine that must be drunk within ten years rarely builds secondary market value, and ageing capacity also matters for tax treatment, covered later in this guide.
  • Scarcity with consumption. Production is limited and bottles are steadily drunk, so supply of any vintage only falls over time.
  • Provenance and format. Original wooden cases, bonded storage history and clean documentation command the strongest prices. Broken cases and unverifiable storage attract discounts or no bid at all.
  • A liquid market. The wine trades often enough for prices to be observable. WineCap’s Wine Track database follows around 3,750 investment-relevant wines for exactly this reason.

A useful mental model: the market pays for predictable excellence. Petrus, the subject of WineCap’s guide to the world’s most valuable Bordeaux wine, commands its prices because roughly six decades of vintages have taught buyers what a bottle is worth. New names enter the investment grade slowly, over many vintages, not on one good review.

Why investors put money into fine wine

The investment case rests on structural features of the market rather than any promise about returns. Investors typically cite four.

Supply falls while demand can grow. Each investment-grade vintage is fixed at bottling, and consumption removes stock every year. A 2005 Bordeaux First Growth becomes scarcer every time a bottle is opened, and no producer can make more of it. Few asset classes have supply that mechanically shrinks.

Low correlation with financial markets. Fine wine prices respond to their own supply and demand cycle, critic reassessments and collector wealth rather than to quarterly earnings. Wine still fell in the 2022 to 2025 downturn, so low correlation never means immunity, but drivers differ from equities and bonds, which is why some investors use wine as a diversifier within a broader portfolio. WineCap’s overview of the wine investment market covers this dynamic in more detail.

A tangible, insurable asset. Cases in a bonded warehouse are physical property in the investor’s name, insured at replacement value. Tangibility carries its own obligations, storage and insurance among them, but many investors value owning something that cannot be diluted, delisted or rehypothecated.

An enjoyable subject. Wine rewards study in a way few asset classes do. The 70/30 rule applies to portfolios as well as prose: the investment case leads, and the pleasure of following producers, vintages and regions is a genuine, secondary benefit.

None of these features guarantees an outcome. The market’s own recent history, covered in the returns section below, is the clearest evidence of that.

How fine wine prices are set

Price formation in fine wine follows a logic every investor should understand before buying, because it explains both the opportunities and the traps. Three forces do most of the work: critical assessment, vintage quality and the arithmetic of shrinking supply.

Critics move markets. A high score from an influential reviewer at release, or a favourable rescore years later, changes what buyers will pay, sometimes within days. The effect is strongest in Bordeaux and Burgundy, where a wine’s score history is part of its trading identity. Rescoring works in both directions: a downgrade on retasting can mark a wine down as surely as an upgrade lifts it.

Vintage quality sets the starting terms. Growing-season weather determines whether a year produces wines built for decades or for early drinking, and the market prices the difference from the outset. Great vintages (2005, 2009, 2010 and 2016 in Bordeaux are commonly cited examples) carry premiums at release and typically hold demand longest. Lesser vintages from great producers can offer value, but they age out of the market sooner.

Scarcity then does the slow work. Once a vintage is bottled, every case opened anywhere in the world tightens the remaining supply. A wine entering its drinking window sits in a narrowing corridor: consumption accelerates just as the wine becomes most desirable. That corridor is where much of fine wine’s historical appreciation has occurred, and it is why holding periods matter so much.

Observable prices knit these forces together. Databases such as Wine Track track them daily across thousands of wines. An investor no longer needs to take a seller’s word for what a case is worth, which is precisely why any firm reluctant to benchmark its prices deserves suspicion.

How wine investment works in practice

The mechanics are simpler than most newcomers expect, and WineCap’s explainer on how wine investment works walks through them step by step. Money follows this path: an investor funds an account, wines are bought on the secondary market or at release, the cases move into bonded storage in the investor’s name, they rest there for years, and eventually they are sold back into the trade.

Four buying routes dominate the UK market.

  • Through a specialist platform or merchant. The investor sets a budget and criteria; the firm sources, stores and later sells the wine, charging fees for the service. This is WineCap’s model, with portfolios starting at a £5,000 minimum investment.
  • En Primeur. Buying Bordeaux (and increasingly other regions) as futures, one to two years before bottling, at the release price. WineCap’s short guide to En Primeur for wine investors explains the mechanics and the risks: paying early does not always mean paying less. 
  • At auction. Auction houses offer mature and rare bottles, with buyer’s premiums that routinely add 20% or more to the hammer price, and provenance that varies lot by lot.
  • Peer-to-peer and exchange trading. Experienced investors with trade accounts can deal via exchanges, taking on sourcing, verification and settlement themselves.

En Primeur deserves a closer look because its mechanics differ from every other route. The buyer pays for the wine while it is still in barrel, takes delivery into bond one to two years later, and carries counterparty risk on the producer and merchant chain in between. The historical bargain, release prices below eventual market prices, has not held reliably in recent campaigns, and several vintages released in the early 2020s later traded below their release prices on the secondary market. The route still offers first access to scarce wines and pristine provenance from day one; it simply has to be judged release by release, against secondary market prices for comparable back vintages, rather than bought on tradition.

Ownership is the detail to verify before any money moves, whichever route an investor takes. Reputable firms hold wine in the client’s name, segregated from company assets, in a recognised bonded warehouse. If the paperwork shows anything else, walk away. The collapse of poorly run wine firms has historically hurt clients whose wine was never truly theirs.

What it costs: minimums, fees and charges

Costs decide whether a paper gain becomes a real one, so they deserve the same attention as the wines themselves. A wine that rises 30% over five years, sold through a channel that takes 25% in combined charges, has enriched everyone except its owner.

Typical cost lines across the UK industry:

  • Entry minimums. Managed portfolios commonly start between £3,000 and £25,000 across the industry; WineCap’s minimum is £5,000.
  • Purchase spread or sourcing margin. The difference between the price paid and the wine’s prevailing market level. Ask any firm how its buy prices compare with market benchmarks.
  • Annual management and storage. Bonded storage and insurance are usually charged per case per year, with management fees a percentage of portfolio value.
  • Exit costs. Selling through a merchant or broker involves a commission or margin; auctions add seller’s fees. Factor the exit charge in before buying, not when selling.

Transparency is the test that matters. An investor should be able to see, in writing, every charge between deposit and eventual sale proceeds. Full fee details for WineCap portfolios are available on request and through a free consultation.

Storage, insurance and provenance

Professional storage is not optional at investment grade. The market pays for perfect condition, and perfect condition is only believable when a wine’s whole life is documented. UK investors use bonded warehouses (HMRC-approved facilities where duty and VAT are suspended), which solve three problems at once.

Condition is the first. Bonded facilities hold wine at stable temperature and humidity, in darkness, with minimal movement: the conditions critics and buyers assume when they price a mature case. WineCap clients’ wines are held at London City Bond’s Drakelow facility and insured at replacement value through Zurich.

Tax efficiency is the second. Wine held in bond has not cleared UK customs, so no duty or VAT falls due while it stays there, and a case can pass from seller to buyer within the bond without either charge crystallising. Most investment wine spends its entire life in bond for this reason.

Provenance is the third. An unbroken bonded history is the strongest evidence a buyer can ask for, and it feeds directly into resale value. Cases that leave bond for a private cellar can return, but the gap in the record usually costs money at sale.

Insurance completes the arrangement, and the details matter more than the headline. Cover should be at replacement value rather than purchase price, so a case that has appreciated is insured for what it would cost to replace today, and valuations should update as market prices move. Investors should also confirm whose policy applies: a warehouse’s blanket cover, the platform’s client policy, or their own. Photographic condition reports at intake, now standard at serious facilities, settle disputes before they start and add another layer to the provenance file that future buyers will pay for.

Returns: what the data actually shows

Honest data serves investors better than selective success stories, so this section reports the full cycle. Over the 20 years to 2022, the Liv-ex 100 index (the industry’s benchmark for the most traded fine wines) rose just over 300%. The market then corrected hard: from its October 2022 peak, the broad market fell roughly 30% over the following three years.

The recent numbers are sobering and specific. The Liv-ex 100 declined 2.5% in 2025, a year in which the Knight Frank Luxury Investment Index as a whole closed down just 0.4% (Knight Frank Luxury Investment Index, April 2026). Trade patterns shifted sharply too: US purchase value fell 43.6% year on year in 2025 under tariff pressure, while European purchases rose 48.2%.

The first half of 2026 has looked different. Liv-ex reported broadly stable indices in the first quarter, and US buying recovered to 26.9% of global purchase value in the second quarter, up from 23.3% in the first. WineCap’s own market coverage reached a similar reading in fine wine market starts 2026 on firmer footing.

Individual wines can diverge a long way from the index in both directions. Dom Ruinart Blanc de Blancs, a selected example rather than a representative one, shows a rise of 135% over ten years, a period across which the broad market first climbed steeply and then gave back a substantial part of those gains. Selection, in other words, is where managed research earns its keep, and it can subtract value as easily as add it when done badly.

Holding period shapes the outcome as much as selection does. Fine wine’s appreciation, where it occurs, accrues over the years in which scarcity tightens and a wine approaches its drinking window, and the market’s cycles run long: the recent correction alone lasted roughly three years. An investor with a five to ten year horizon can ride a full cycle; one who may need the money in two years is speculating on timing, in an asset that punishes forced sales. The industry convention of quoting five years as a minimum hold reflects this arithmetic rather than any promise about what five years will deliver.

Two disciplines keep return expectations honest. Measure any wine against the index over the same period, so a strong performer is seen in context. And treat every historical figure, including all of the above, as description rather than prediction: past performance is not a guide to future returns. WineCap’s approach to performance measurement is set out on our performance page.

The risks investors must price in

Every genuine investment case survives its risk list. 

  • Prices fall. The 2022 to 2025 drawdown of roughly 30% is the current, lived reminder. 
  • Illiquidity. Selling takes weeks or months, not minutes. In a weak market, bids for even blue-chip wines can be thin, and a forced seller takes whatever the market offers.
  • No regulatory protection. Wine investment is unregulated in the UK. The Financial Conduct Authority does not authorise it, and investors have no access to the Financial Services Compensation Scheme or the Financial Ombudsman Service if a firm fails or a dispute arises.
  • Fraud and mis-selling. The sector has a documented history of scams, from cold-called “guaranteed return” schemes to firms selling wine they never owned. UK Trading Standards has prosecuted wine investment frauds running into tens of millions of pounds.
  • Cost drag. Storage, insurance, management and exit charges accrue every year, in flat and falling markets as well as rising ones.
  • Currency and policy shocks. The 2025 US tariffs moved global demand within months. Sterling investors also carry exchange rate exposure to a market that prices much of its demand in dollars.
  • Condition and provenance failures. A flooded warehouse, a faked case or a broken storage record can impair value regardless of what the index does.

Sizing is the practical defence. Most advisers who cover alternatives suggest they sit as a minority allocation within a diversified portfolio, money whose multi-year absence an investor can tolerate. Fine wine is a long-term investment that rewards patience.

How fine wine is taxed in the UK

Tax treatment is one of fine wine’s most cited attractions and one of its most misunderstood. The rules deserve precision, and WineCap’s detailed guides to the tax benefits of fine wine investment and to whether wine is a wasting asset for capital gains tax cover the full detail, including worked examples against 2026/27 thresholds.

The headline concerns capital gains tax. HMRC treats an asset with a predictable useful life of under 50 years as a “wasting asset”, exempt from CGT, and its Capital Gains Manual (CG76901) discusses how this applies to wine. Many everyday wines clearly qualify. The complication sits exactly where investors operate: investment-grade wines are built for decades of ageing, and HMRC’s guidance contemplates that fine wines capable of lasting beyond 50 years may not qualify for the exemption. The point is judged case by case, on the wine and the facts.

A second relief exists independently. Wine is a chattel (tangible movable property), and disposals of chattels for proceeds of £6,000 or less are exempt from CGT under HMRC’s chattels rules (HMRC, 2026/27), with marginal relief just above that level. Sales structured as separate cases to separate buyers are, however, aggregated where HMRC treats them as a set.

Duty and VAT behave differently again. Wine kept in bond suspends both until the wine clears customs, which is why bonded storage is the default for investment. Inheritance tax offers no special shelter: wine forms part of an estate at market value like any other possession, and estates with significant cellars need valuations and records their executors can rely on.

Pensions close one door investors sometimes ask about. Wine is tangible movable property, which HMRC’s pension rules treat as taxable property inside a SIPP (self-invested personal pension); holding it there triggers tax charges that remove any benefit, so wine investment sits outside pension wrappers in practice. The comparison with regulated, wrapper-eligible investments also restates a point this guide makes elsewhere: wine investment itself is unregulated in the UK, with no FCA authorisation, FSCS cover or FOS recourse.

Every part of this depends on individual circumstances, and the rules can change at any Budget. Treatment that applies to one investor’s cases may not apply to another’s. Independent tax advice, taken before selling rather than after, is the sensible course.

Building a first portfolio: regions and diversification

Diversification works in wine much as it does elsewhere: across regions, producers, vintages and price points, so no single reassessment or regional slump dominates the outcome. The starting map has five main territories, each with a distinct investment character.

Bordeaux remains the market’s backbone and its most liquid region, accounting for 35.5% of secondary market trade by value in 2025. The 1855 classification gives the Left Bank its hierarchy, from the five First Growths (Lafite Rothschild, Latour, Margaux, Mouton Rothschild and Haut-Brion) down through the classed growths, while the Right Bank contributes Petrus, Le Pin and the leading names of Saint-Emilion and Pomerol. Production volumes are large by fine wine standards, often ten to twenty thousand cases per wine per vintage, which is exactly what makes Bordeaux tradeable: price histories run for decades and a seller can usually find a bid. The so-called super seconds (estates such as Pichon Lalande and Lynch-Bages that trade below First Growth prices on comparable quality) are a common first purchase for value-minded investors.

Burgundy sits at the opposite pole. Production at the top domaines of the Cote de Nuits and Cote de Beaune is measured in hundreds of cases, sometimes fewer, and prices reach the market’s summit. Scarcity cuts both ways: it has driven some of the strongest long-run appreciation in the market, and it thins liquidity, widens pricing and raises the stakes on authenticity. Burgundy rewards knowledge and patience more than any other region, which is why most allocators treat it as a later addition rather than a foundation.

Champagne has become a core allocation rather than a satellite, led by prestige cuvees from houses such as Dom Perignon, Krug, Cristal and Salon. Its investment logic is unusually clean: these wines are drunk in celebration around the world, so consumption retires stock quickly, while house branding keeps demand broad. Italy contributes two poles of its own, Piedmont’s Barolo and Tuscany’s Brunello alongside the Super Tuscans (Sassicaia, Tignanello, Ornellaia and peers), and its share of secondary market trade grew through the recent downturn as buyers sought value outside France. The Rhone, Spain’s Vega Sicilia and California’s cult names (Screaming Eagle, Opus One) complete the usual map, adding breadth at various price levels.

Vintage and producer spread complete the diversification picture. Two cases of the same wine from different vintages behave differently: one may sit in its drinking window while the other is still climbing towards it. Producer concentration carries the same lesson. A portfolio built entirely on one estate, however grand, rides every rescore and every release decision that estate makes. Spreading across eight to twelve producers, several vintages and at least three regions gives a first portfolio the shape professionals build towards.

A first portfolio does not need all of them at once. A common approach weights liquid Bordeaux as the foundation, adds Champagne and Italy for balance, and treats Burgundy and cult names as later, selective additions. WineCap’s beginner’s guide to starting a wine investment portfolio in the UK works through allocation examples in detail.

Wine compared with whisky, art and other alternative assets

Fine wine competes for the same allocation as other collectible and passion assets. Structural differences matter more than any one year’s league table. Wine’s advantage over most rivals is market infrastructure: standardised units (the 12x75cl case), published exchange prices, professional bonded storage and a deep merchant network make fine wine unusually easy to value and to sell for a physical asset. Art sits at the opposite extreme, with unique objects, opaque pricing and sale costs that can consume a fifth of proceeds. Cask whisky has boomed on scarcity narratives but lacks wine’s central price benchmarks, which has made it a magnet for mis-selling; its regulatory position, like wine’s, is unregulated in the UK.

Wine’s disadvantages are equally structural. It is consumed rather than displayed, needs specialist storage, and its correction of 2022 to 2025 showed drawdowns can run for years. Watches and art can be enjoyed daily while held; a case in bond cannot, unless its owner is willing to sacrifice provenance. Investors weighing the categories usually conclude they are complements rather than substitutes, and that the honest comparison is less about which asset “wins” than about which risks an investor understands well enough to carry.

Common mistakes first-time wine investors make

Most mistakes in wine investment are avoidable at the point of purchase. Overpaying at entry is the most expensive and least visible mistake. A case bought 15% above its market level starts its life needing years of appreciation just to reach par. This is why correct valuations and price benchmarking against published market data, before every purchase, is the single highest-value habit an investor can build.

Concentration comes next. First-time portfolios built entirely on one region, one famous producer or one celebrated vintage carry risks their owners rarely price: a regional slump, a critical reassessment or a tariff decision lands on the whole portfolio at once. The 2025 trade data showed how quickly regional demand can rotate, with US purchase value down 43.6% while European buying rose 48.2%.

Ignoring costs quietly erodes the rest. Storage, insurance, management and exit charges continue in flat years, and an investor who never totals them can hold a “winning” wine to a losing outcome. Impatience compounds the damage: selling inside two or three years, before scarcity has done any work, frequently returns less than the wine cost once fees are counted.

The final mistake is the oldest: buying from the wrong counterparty. Wine bought from a cold call, at an unverifiable price, held in a warehouse the buyer cannot name, fails every test this guide has set out. 

How to start: a step-by-step path

The process from first research to funded portfolio is short. Care at each step matters more than speed.

  1. Define the budget and the horizon. Decide the sum, confirm it can stay invested for five to ten years, and place it inside a wider plan: fine wine belongs alongside other assets, not instead of them.
  2. Choose the route. Managed platform, self-directed buying through merchants, En Primeur, auction, or a blend. First-time investors usually start managed; the beginner’s guide to fine wine investment compares the options.
  3. Vet the firm. Apply the due-diligence questions in the next section before signing anything or sending money.
  4. Agree the mandate. Budget, regional spread, holding period and fee schedule, all in writing.
  5. Verify ownership and storage. Confirm the wines sit in your name in a recognised bonded warehouse, insured at replacement value, with documentation to prove it.
  6. Monitor without meddling. Track valuations against a benchmark, using tools like Wine Track. Fine wine repays annual reviews, not daily ones.
  7. Plan the exit from day one. Know how sales work, what they cost and how long they take, before the first case is bought.

Questions along the way have a natural home: WineCap’s help and FAQ centre answers the operational ones, from minimums to withdrawals.

How to sell wine and exit an investment

Exits define realised returns, and the secondary market offers several doors out. A managed platform sells on the client’s behalf through its trade network, handling logistics and documentation for its stated commission or margin. Independent owners can consign to a broker or merchant, list on an exchange through an account holder, or enter wines for auction, where seller’s commissions and settlement timescales vary house by house.

Practical selling discipline focuses on what an owner controls: selling from strength rather than necessity, keeping cases in bond with clean records so they are always saleable, spreading disposals rather than dumping a whole portfolio into one market moment, and comparing the net proceeds a route offers after every fee.

Settlement takes patience. From instruction to cash, a typical trade sale runs weeks; auctions can run longer once cataloguing and payment terms are counted. Investors who need money on a fixed date should sell well ahead of it.

Net proceeds are the only number that counts at exit, and they reward a simple habit: before instructing any sale, ask each available route for its all-in figure after commission, storage settlement and delivery charges, then compare that figure with the wine’s current market level. A route offering 95% of market value with two-week settlement often beats one dangling a higher headline through a slower, costlier channel. Sellers who run this comparison once tend to run it every time.

Choosing a wine investment company

The choice of counterparty carries as much risk as the choice of wine, in an industry where anyone can print a brochure. A short interrogation separates serious firms from the rest.

  • Ownership and segregation. Are wines held in the client’s name, segregated from company stock, in a named bonded warehouse? Ask to see a specimen storage account and insurance certificate.
  • Pricing transparency. How do purchase prices compare with market levels, and will the firm show the comparison? Opacity here is where poor outcomes usually begin.
  • The full fee schedule, in writing. Every charge from entry to exit, with nothing “available on request” that never arrives.
  • Track record and people. How long has the firm traded, who runs it, and what does its own published analysis look like? Independent reviews and press coverage add texture.
  • Realism in the sales conversation. A firm that leads with the 2022 to 2025 drawdown as readily as the 20-year rise is describing the same market this guide does. One that promises dependable returns is describing a market that does not exist, and the Advertising Standards Authority has upheld rulings against wine investment firms for exactly such claims (ASA, 2024 to 2025).
  • No pressure. Cold calls, countdown offers and “act now” framing are the classic markers of the sector’s fraud cases. Legitimate wine is still there next week.

WineCap publishes its data, methodology and market analysis precisely so investors can run these checks. A free consultation exists to answer them.

Where fine wine fits in a 2026 portfolio

The fine wine market entering late 2026 is a more honest proposition than the one marketed at the 2022 peak: repriced by a three-year correction, showing measured signs of stabilisation, and stripped of the easy narratives. That honesty suits serious investors. An asset bought with clear eyes, at a £5,000 minimum rather than a fortune, held in bond for years and measured against a public benchmark, can earn a place in a diversified portfolio precisely because its owner knows what it is and what it is not. The investors best positioned for the next cycle are the ones who understand the machinery this guide describes: what qualifies, what it costs, how it is taxed, and how they will one day sell.

FAQ: Wine investment in 2026

Is wine a good investment in 2026?

Fine wine can suit investors seeking a long-term, tangible, diversifying asset, but it is unregulated in the UK and illiquid compared with shares. Suitability depends on an investor’s horizon, existing portfolio and tolerance for drawdowns.

How much money do I need to start investing in wine? 

UK managed wine portfolios commonly start between £3,000 and £25,000; WineCap’s minimum investment is £5,000. Self-directed buying can begin with a single investment-grade case, though diversification across regions and vintages argues for a larger starting sum.

What returns can I expect from wine investment?

No future return can be promised. The Liv-ex 100 rose just over 300% in the 20 years to 2022, then the market fell roughly 30% over the following three years, and the index declined 2.5% in 2025 alone. Past performance is not a guide to future returns.

Is wine investment tax-free in the UK? 

Sometimes, not automatically. HMRC exempts “wasting assets” (predictable life under 50 years) from capital gains tax, and many wines qualify, but investment-grade wines built for long ageing may not; disposals of £6,000 or less may fall under the separate chattels exemption (HMRC, 2026/27). Treatment depends on individual circumstances and may change, so independent tax advice is essential.

How do I sell my wine investment? 

Wine sells through a managed platform’s trade network, via merchants and brokers, on exchanges, or at auction, with commissions and timescales differing by route. A typical trade sale takes weeks from instruction to settlement. Wines kept in bond with unbroken storage records achieve the strongest prices.

How do I avoid wine investment scams? 

Verify that wines are held in your name in a named bonded warehouse, demand the full fee schedule in writing, compare purchase prices with market levels, and treat cold calls, promised returns and pressure tactics as disqualifying. Wine investment is unregulated in the UK, with no FCA, FSCS or FOS protection, so this due diligence replaces the safety net.
Categories
Learn

What is the difference between auction and market prices in fine wine investment

  • Auction prices and market prices for fine wine are intrinsically linked yet understanding the distinction is important for valuations.
  • Buyer’s premiums of 25% are standard at most major wine auction houses, meaning that  the final price a buyer pays is almost always significantly above the hammer price.
  • For older vintages, auctions dominate fine wine trading.

For fine wine investors, a wine price can mean different things depending on where you look. An auction price records what a buyer was willing to pay for a particular wine at a particular moment, through a competitive bidding process. A market price, by contrast, is typically derived from the prices at which sellers are currently offering comparable wines on the secondary market.

The two are closely related, but they are not interchangeable. Auction results provide evidence of completed transactions, while market prices offer a broader view of current availability and seller expectations. Both are useful, and both have limitations. Understanding the difference – and knowing which measure to use when – is an important part of valuing fine wine.

What auction prices and market prices actually measure

In economic theory, the market price is the equilibrium point at which supply and demand meet. In fine wine, however, the term is used more practically.

A fine wine market price is typically a derived value based on the asking prices of multiple sellers active on the secondary market. It draws on dozens, and sometimes hundreds, of listings to establish the best available price for a comparable case in perfect, or reliably assumed to be perfect, condition.

It is therefore not the price at which one transaction has necessarily taken place. Rather, it is an aggregate view of what sellers are asking for the wine at a particular point in time – and, by extension, what a buyer could reasonably expect to pay to acquire it.

Platforms such as WineCap aggregate these listings into benchmark prices that act as reference points across the secondary market. Market prices simplify price discovery and reduce search friction for buyers and make comparison straightforward, particularly for younger wines in standard formats with clear provenance.

In economic theory auction prices are simply a way to ascertain a market price. A competitive bidding process sets the price in real time. The hammer falls at the highest bid, and that bid becomes the market price for whatever asset is being sold. 

In practice, the two are not synonymous and auction prices can be quite different from market prices. Auctions tend to maximise revenue for rare or scarce assets, because it surfaces the most motivated buyer available on that day. Arguably, that makes auction prices a truer expression of what a specific case of wine is worth at the moment of sale, but is less relevant to the price of another case. 

Auction prices tend to be more volatile, are often higher, and are most commonly seen with a narrower set of wines.

The fine wine auction market: who the players are

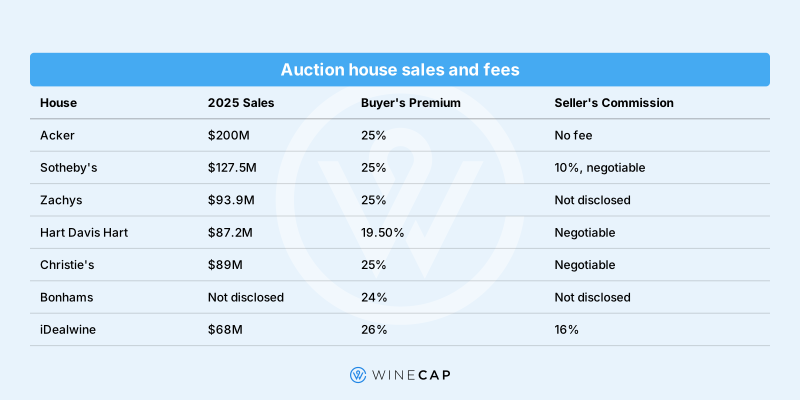
Wine auctions operate across a well-established hierarchy of houses. Sotheby’s and Christie’s lead the global auction market broadly, with significant wine departments. For wine specifically, an additional group of specialist auctioneers accounts for the largest share of trading volume. Most auctioneers announce their sales figures in US dollars.

  • Acker Merell and Condit: $200 million (approximately £157 million) in sales in 2025
  • Sotheby’s $127.5 million (approximately £100 million) in sales in 2025
  • Zachys: $93.9 million (approximately £74 million) in sales in 2025
  • Hart Davis Hart: $87.2 million (approximately £69 million), 19.5% buyer’s premium
  • Christie’s: $89 million (approximately £70 million) in sales in 2025

While Bonhams has a wine department, they do not disclose their total wine sales. Online platforms have also expanded the market. iDealwine, a France-based specialist, generated $68 million (approximately £54 million) in 2025 sales. Bid for Wine, owned by Dreweatts, is a regional British auctioneer and operates a comparable digital model in the UK. 

The cost of buying and selling at auction

Auction prices require careful translation before any comparison with market prices. The hammer price (the final bid at which a lot is sold) is not what the buyer pays, and it is not what the seller nets. Both sides face additional costs that can be very significant.

Buyers must add a premium to the hammer price. At most major wine auction houses, this runs at 25%, though Hart Davis Hart charges 19.5% and iDealwine charges 26%. On a case selling for £10,000 at the hammer, a 25% buyer’s premium means a total cost of £12,500 before any delivery or storage charges.

The picture for sellers is more opaque. Houses rarely disclose their commission rates upfront, and rates are almost always negotiable. Acker has set itself apart by charging no seller’s commission, a large part of the reason that they have grown in popularity and revenue. For attractive collections, auction houses compete actively for consignment, with seller’s fees being the major area of negotiation. A seller with a large holding of attractive wines can negotiate seller’s commission to zero. In the most competitive cases, a seller may even secure a proportion of the buyer’s premium, receiving more than 100% of the hammer price as a net return.

Why auction prices are more volatile than market prices

Auction results for the same wine can vary significantly. Condition and provenance (verifiable storage history and ownership chain) drive much of that variability. In the secondary market, younger wines sold in bond carry implied provenance: the storage record is clean by definition. At auction, bottles of varying age and condition compete for buyers who may hold very different views of the same lot.

For instance, in March 2023, three major auction houses sold Domaine de la Romanee-Conti, La Tache 2009. Including buyers’ fees, Acker achieved a case-price equivalent of £70,000, Zachys achieved £62,500, and Sotheby’s achieved £145,000.

At the time, Liv-ex showed a market price of £69,000 per case for the same wine. Wine quality does not explain the spread: the specification across all three lots was identical. The result reflects the specific bidder composition in each room on each day.

Auction prices to ignore: charity sales and distorted results

Not every auction result belongs in a price analysis. Charity auctions regularly produce figures that bear no relationship to market value. Tax treatment creates a real incentive to bid beyond market rates: in the United States, a donor who bids generously at a charity auction may benefit from a tax deduction that reduces their effective net cost. The psychological premium of supporting a high-profile cause adds a further layer. Charity auction results should be stripped from any serious valuation exercise.

The phenomenon extends well beyond wine. In August 2026, “Chassis Zero”, the first production model of Ferrari’s first electric vehicle, the Ferrari Luce, sold at an RM Sotheby’s charity auction during Monterey Car Week in California for $40 million (approximately £32 million). A standard Luce carries a list price of approximately 550,000 euros (roughly £470,000 at launch). No quality or rarity argument explains that gap.

The same distortion appears within wine. In 2026, Chateau Haut-Brion 1961 sold at Sotheby’s in Hong Kong for a case-price equivalent of £17,500, excluding fees. Ten days earlier, a magnum of the same wine sold at Christie’s in London for a case-price equivalent of £65,000, also excluding fees. The Christie’s sale was a charity event. An investor using that result to value their own bottles would overstate the figure by nearly four times.

When auction is the right marketplace

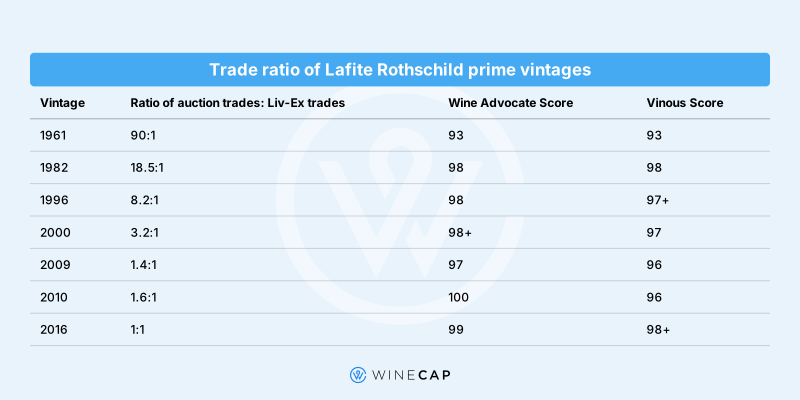
For older wines, auction is the dominant trading mechanism. Analysis of Chateau Lafite Rothschild across seven prime vintages shows how sharply the ratio of auction trades to Liv-ex secondary market trades shifts with age. The older the wine, the more the auction room dominates as the primary marketplace.

The same pattern holds across high-value, long-lived assets generally. Classic cars, watches, and fine art all see the same migration toward auction as the primary trading mechanism as they age and become genuinely rare. Knowing when to use auction prices as a valuation input, when to rely on secondary market benchmarks, and when to discard a result entirely as an outlier or a charity distortion is a genuine source of edge in this market.

FAQ: Auction vs market prices in fine wine investment

How do I know if an auction result is a reliable market reference?

Check three things before using any auction result as a valuation input: whether the sale was a charity event (if so, discard it), the condition and provenance notes on the lot, and whether multiple comparable results support the figure. A single result tells you far less than the range.

Is auction or the secondary market better for selling fine wine?

It depends on the wine and the vintage. Younger wines in bond with clean provenance typically achieve competitive results on the secondary market at lower transaction cost. Older and rarer bottles trade more actively at auction, where specialist buyers concentrate. 

What is the difference between the hammer price and the total cost at auction?

The hammer price is the winning bid, before fees. As a buyer, adding a 25% buyer’s premium to a £10,000 hammer price brings the total to £12,500, before any delivery or storage costs. As a seller, your net return is the hammer price minus any seller’s commission. Sellers of attractive collections can negotiate commissions to zero, or in some cases receive more than the hammer price through a share of buyer fees.

Why are older wines more likely to sell at auction?

As a wine ages, listed secondary market activity falls and auction becomes the primary venue where motivated buyers for rare, old bottles congregate. As our data above shows, that shift is measurable: the 2016 vintage trades equally between auction and Liv-ex, while the 1961 vintage trades at auction 90 times more frequently. Auction provides price discovery for assets with limited comparable transactions, which is precisely what very old fine wine becomes over time.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.

Categories
News

The most expensive fine wines in 2026

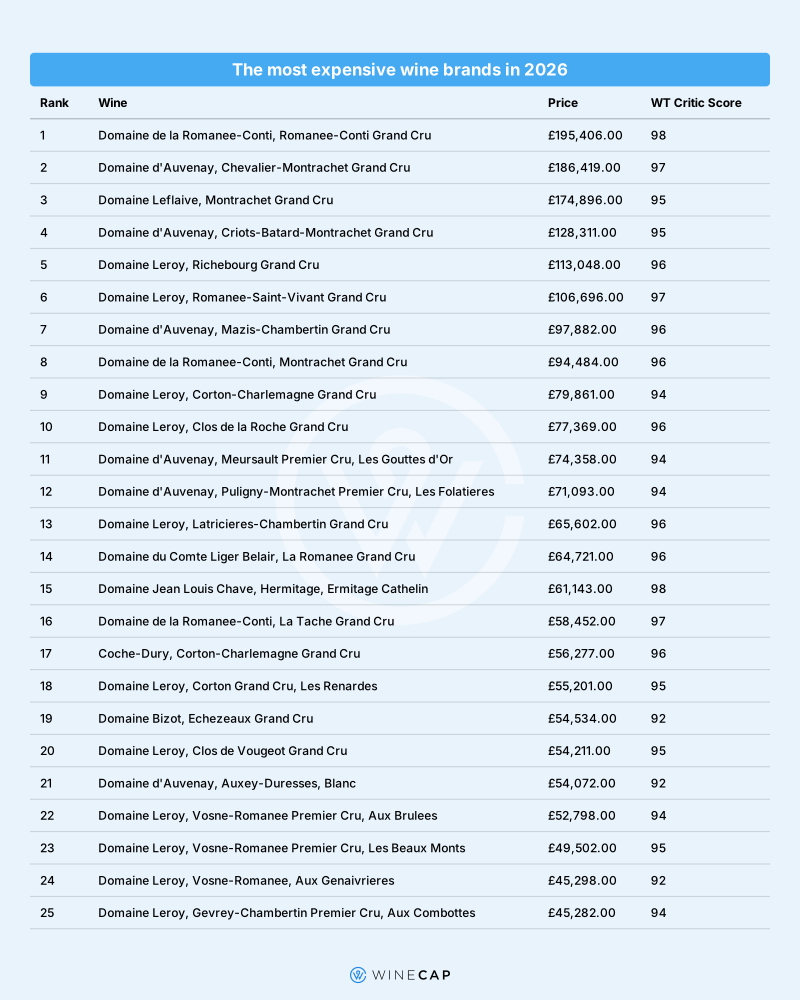
  • Domaine Leroy and Domaine d’Auvenay, both owned by Lalou Bize-Leroy, take 17 of the 25 places in the ranking of the world’s most expensive wine brands and 64.1% of its combined value.
  • Twenty-four of the most expensive fine wine brands in 2026 come from Burgundy, with only Chave’s Ermitage Cathelin, from the northern Rhone, breaking the region’s hold.
  • Romanee-Conti tops the ranking at £195,406 a case but posted the lowest ten-year price move of all 25 wines, at 70.9%.

Burgundy’s rise to the top of the fine wine market has been one of the defining trends of the past decade. Scarce production, growing international demand and a remarkable run-up in prices transformed its leading domaines into some of the world’s most valuable wine brands. Even after the correction that followed the market’s 2022 peak, it is perhaps unsurprising that Burgundy dominates WineCap’s ranking of the most expensive fine wines.

What is more striking is just how concentrated that dominance has become. Twenty-four of the 25 wines on the list come from Burgundy, but 17 come from just two domaines – Domaine Leroy and Domaine d’Auvenay – both owned by Lalou Bize-Leroy. Together, they account for 64.1% of the ranking’s combined value.

At this end of the market, price increasingly tells a story about scarcity as much as quality. The ranking reveals a fine wine summit concentrated around one region, a handful of producers and, above all, one extraordinary owner.

The most expensive wine brands in 2026 critic scores

*Average Case Price – Average market price across basket vintages, per 12×75cl.

*Wine Track Critic Score – Aggregate of published third-party critic scores, normalised to 100 points.

*Methodology: Prices represent the average of the best available market prices across recent vintages, exceptionally rare wines are excluded where there is insufficient reliable market data to establish a comparable price.

Two estates by the same owner dominate the ranking 

The scale of Lalou Bize-Leroy’s presence becomes clearer further down the ranking. Domaine Leroy contributes 11 wines and Domaine d’Auvenay another six, including Chevalier-Montrachet Grand Cru, the second most expensive wine on the list at £186,419 per 12x75cl case equivalent. Because our methodology intentionally excludes wines for which there is very little data, at least four further wines from Leroy and d’Auvenay are not included on our list. By comparison, Domaine de la Romanee-Conti holds three places, while the remaining five producers appear only once each.

Behind those prices is extreme scarcity. Domaine d’Auvenay farms just 3.87 hectares across 16 appellations, with some parcels producing only a few hundred bottles. Its holding in Criots-Batard-Montrachet, for example, extends to just 0.064 hectares. Production at Domaine Leroy is similarly constrained, combining tiny vineyard holdings with some of Burgundy’s lowest yields.

That scarcity is concentrated around one owner. Bize-Leroy, now in her nineties, farms both estates biodynamically and also retains a 25% share of Domaine de la Romanee-Conti. For collectors and investors, the result is unusual: much of the very top of the fine wine price hierarchy is tied to the output, reputation and eventual succession of a single grower.

Burgundy takes 24 of the 25 places

Only one wine breaks Burgundy’s hold on the ranking. Domaine Jean-Louis Chave’s Ermitage Cathelin, from the northern Rhone, sits fifteenth at £61,143 a case. The next non-Burgundy wine does not appear until 28th place, with Screaming Eagle Sauvignon Blanc from Napa Valley.

The gaps become wider from there. Petrus, the highest-ranked Bordeaux, sits 46th, while Krug Clos du Mesnil is Champagne‘s highest entry at 80th. Italy‘s highest-ranked wine, Soldera Case Basse, does not appear until 99th place.

Burgundy’s dominance at the very top comes as the region is also regaining ground in the broader secondary market. In July 2026, it overtook Bordeaux as the most traded region by value on Liv-ex for the first time since 2022, with DRC, Ramonet, Leflaive and d’Auvenay together accounting for roughly a third of Burgundy trade during the month.

The two measures capture different things. Trading share reflects where activity is taking place across the market; this ranking captures the extreme upper end of pricing. But together they underline Burgundy’s unusual position in 2026: it is home to almost every wine at the top of the price hierarchy while once again attracting a growing share of secondary market trade.

For more on Burgundy, read the WineCap Burgundy Regional Report.

White wine sits at the top of a red region

Red wines make up the majority of the ranking, with 16 of the 25 places. Yet white Burgundy is disproportionately represented at the very top: three of the four most expensive wines are white, as are five of the top ten.

The price difference is equally striking:

  • White Burgundy average £102,197 a case, compared with £74,822 for red Burgundy
  • The median white wine costs £79,861, versus £59,798 for red
  • Whites account for 36% of the wines on the list but 43.4% of its combined value

Scarcity helps explain the premium. The great white Grand Cru vineyards of the Cote de Beaune are exceptionally small, and production becomes smaller still when divided between individual domaines and parcels. At the same time, white Burgundy has proved more resilient than red during the recent market correction. Liv-ex has noted an excess of supply over demand for red Burgundy below £5,000 per case, while better-known whites have been an exception.

The most expensive wine has been the slowest riser

Romanee-Conti Grand Cru remains the most expensive wine in the ranking at £195,406 a case, but it has delivered the lowest ten-year price appreciation of all 25 wines, at 70.9%. By contrast, Domaine d’Auvenay’s six wines have risen by an average of 1,178% over the same period, while Domaine Bizot’s Echezeaux Grand Cru recorded the single largest increase, at over 2,000% in the last decade.

The comparison highlights an important distinction between price and performance. Romanee-Conti began the period from an already exceptional valuation, while some of the wines that have risen fastest were starting from much lower bases. These are also exceptionally scarce wines, where relatively few transactions can produce large percentage movements. The figures therefore describe the performance of a highly selective group rather than Burgundy, or fine wine, as a whole.

The recent picture is more subdued. Seventeen of the 25 wines have fallen over the past twelve months, producing an average decline of 2.0%, while their average six-month movement stands at just +0.4%. That follows the wider Burgundy correction: the Liv-ex Burgundy 150 fell 34% between its September 2022 peak and August 2025, before rising 2.2% from September 2025.

Nor does critical acclaim alone explain the price hierarchy. Chave’s Ermitage Cathelin has the highest Wine Track score on the list at 97.6, yet ranks fifteenth by price. Domaine d’Auvenay’s Auxey-Duresses Blanc has the lowest score, at 91.5, but still commands £54,072 a case after rising 494% over five years. Across the 25 wines, the rank correlation between score and price is 0.55, suggesting that critical quality matters, but scarcity, producer reputation and demand play a substantial role in determining price at this end of the market.

What the world’s most expensive wines tell us about the market

WineCap’s ranking is ultimately as much a measure of scarcity as it is of price. Twenty-four of the 25 wines come from Burgundy, 17 come from two domaines controlled by Lalou Bize-Leroy, and many are produced from vineyard holdings measured in fractions of a hectare. At the very top of the fine wine market, supply can be extraordinarily limited.

But the ranking also shows why price alone is an incomplete measure of investment potential. Romanee-Conti is the most expensive wine on the list but has delivered its lowest ten-year appreciation. Critical scores have only a moderate relationship with price, while some wines are so rarely available that establishing a reliable current market value becomes difficult.

That makes the top of the market very different from the broader Burgundy recovery now emerging on the secondary market. Burgundy may have returned to the largest share of Liv-ex trade by value in July, but the wines in this ranking occupy its narrowest and least accessible end. 

Their extraordinary valuations demonstrate the premium the market can place on scarcity and provenance – but also why diversification across producers, regions and price points matters when building a fine wine portfolio.

FAQs: The world’s most expensive wines

What is the most expensive wine in the world in 2026?
Based on WineCap’s Wine Track data as of August 2026, Domaine de la Romanee-Conti’s Romanée-Conti Grand Cru is the most expensive actively traded wine in the ranking, valued at £195,406 per 12x75cl case equivalent.

What are the most expensive wine brands in 2026?
The most expensive fine wine brands are overwhelmingly Burgundian. Domaine Leroy and Domaine d’Auvenay account for 17 of WineCap’s 25 most expensive wines, while Domaine de la Romanee-Conti holds three places.

Why is Domaine Leroy so expensive?
Domaine Leroy combines exceptionally small production with some of Burgundy’s most prestigious vineyard holdings and strong global collector demand. Its wines are produced in very limited quantities, making availability on the secondary market extremely restricted.

Why are Burgundy wines so expensive?
Burgundy’s most sought-after wines come from small, precisely defined vineyards whose production cannot easily be expanded. At the top end, tiny yields, fragmented vineyard ownership and international demand for a handful of producers create significant scarcity premiums.

Is the most expensive wine always the best investment?
No. Romanée-Conti is the most expensive wine in WineCap’s 2026 ranking but recorded the lowest ten-year price appreciation among the 25 wines, at 70.9%. Entry price, liquidity, scarcity and demand all influence investment performance.

What is the most expensive wine outside Burgundy?
Domaine Jean-Louis Chave’s Ermitage Cathelin from the northern Rhone is the only non-Burgundy wine in WineCap’s top 25, ranking fifteenth at £61,143 per case in August 2026.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.

Categories
Learn

Is wine a wasting asset for capital gains tax?

  • Whether wine is a wasting asset for capital gains tax depends on the bottle, not the category, because HMRC applies a predictable life test of under 50 years.
  • HMRC’s manual states it would normally contend that fine wine kept for periods well in excess of 50 years is not a wasting asset.
  • Where the exemption does not apply, the chattels rules and the £3,000 annual exempt amount still limit exposure, with gains taxed at 18% or 24% (HMRC, 2026/27).

Fine wine’s reputation as a capital gains tax free asset rests on one narrow statutory rule, and that rule does not cover every bottle. HMRC treats wine as a wasting asset only where its predictable life at acquisition falls under 50 years, and its own guidance singles out long-lived fine wine as the category most likely to fail that test. This article sets out how the rule works, where investment-grade wine sits within it, and which capital gains tax rules apply when the exemption falls away.

What counts as a wasting asset for capital gains tax

HMRC’s wasting asset rule turns on a single number: fifty years. Section 44 of the Taxation of Chargeable Gains Act 1992 defines a wasting asset as one with a predictable life not exceeding 50 years at the time of acquisition. Where an asset is both a wasting asset and a chattel (tangible movable property), section 45 removes the gain from capital gains tax altogether.

That combination explains the attention fine wine receives from private investors. A bottle is tangible, it is movable, and most wine is drunk long before its fiftieth birthday. The exemption applies to the asset in front of HMRC, though, not to wine as a category.

HMRC accepts in its Capital Gains Manual that most wine is consumed well below the age of 50 years, and frames the practical question as whether a wine has turned to vinegar or has merely matured (HMRC, Capital Gains Manual CG76901). Cheap table wine passes that test comfortably. Investment-grade wine is a harder case, and the difference matters at the point of sale rather than the point of purchase.

Two further points frame everything that follows. The exemption is tested at disposal, using facts fixed at the date of acquisition, and the taxpayer carries the burden of establishing those facts. Neither point is obvious from the way the rule is usually summarised in marketing material.

Treatment depends on individual circumstances and may change, so the sections that follow describe how the rules are applied rather than what any particular portfolio will owe.

Why HMRC treats fine wine differently from table wine

Fine wine sits awkwardly inside the wasting asset rule, and HMRC says so directly. The Capital Gains Manual states that, where the facts justify it, HMRC would normally contend that wine is not a wasting asset if it appears to be fine wine which is not unusually kept for substantial periods sometimes well in excess of 50 years (HMRC, CG76901). The wines most likely to be bought as investments are therefore the wines most likely to sit outside the exemption.

Everyday wine faces no real argument in the other direction. A supermarket case will not survive 50 years in bottle, so its predictable life is plainly shorter than the threshold. The problem is that such wine rarely produces a chargeable gain worth arguing about, which leaves the exemption most secure exactly where it is least useful.

Certain investment-grade wines built for long ageing may not qualify for the exemption at all. Investors should take independent tax advice on their own holdings rather than treating the wasting asset rule as automatic.

Fortified wines and other bottles that may not be exempt

Several categories carry an obvious longevity problem, and HMRC identifies them readily. Each is defined by a storage life that a valuer would put beyond 50 years without much hesitation, which is the same evidence an investor would need to argue the opposite.

  • Vintage Port, Madeira and Sherry. Fortification extends life dramatically, and Madeira in particular is drunk at ages measured in centuries rather than decades.
  • Cognac, Armagnac and other long-lived spirits. Bottled spirits are stable almost indefinitely, so a sub-50-year predictable life is difficult to sustain.
  • Sauternes and other sweet wines. Château d’Yquem is routinely cellared for 50 years or more, and its published drinking windows reflect that.
  • Classified Bordeaux and top Burgundy in strong vintages. Critics’ drinking windows for leading estates frequently extend beyond half a century, and those windows are evidence HMRC can read as easily as an investor can.
  • Prestige Champagne. Late-disgorged and vintage cuvees from the leading houses age far longer than the category’s reputation suggests.

Inclusion on this list does not settle the question. An investor holding these wines needs a documented, wine-specific case for a shorter predictable life rather than a general argument about wine as a category.

Predictable life is measured from when you buy, not the vintage

Predictable life runs from the date of acquisition, not the date on the label. That single point reverses the intuition many investors bring to the question, and it can work in an investor’s favour.

Consider two purchases. A buyer who acquires a mature 1970 Bordeaux in 2026 is holding a wine with perhaps 15 to 20 years of useful drinking life remaining, which sits comfortably below the threshold. A buyer who acquires a 2020 First Growth on release is holding a wine whose critic-assessed drinking window may extend past 2080, which does not.

The age of the bottle at acquisition therefore does more work than its total lifespan. Mature stock purchased late in its life has a stronger claim to wasting asset treatment than young stock bought on release, even where the two wines carry the same label. Portfolios assembled around back vintages and drinking-window purchases sit differently, for tax purposes, from portfolios assembled around En Primeur allocations.

None of this converts an argument into a certainty. HMRC assesses the facts of each disposal, and the burden of showing a predictable life under 50 years sits with the taxpayer.

The chattels exemption when wine is not a wasting asset

A wine that fails the wasting asset test is still a chattel, and the chattels rules limit exposure in their own right. Section 262 of the same Act provides that a gain is not chargeable where the disposal proceeds do not exceed £6,000, with marginal relief above that figure capping the chargeable gain at five thirds of the excess over £6,000 (HMRC, 2026/27).

Several further allowances sit alongside it:

  • The annual exempt amount. Individuals have £3,000 of tax-free gains in the 2026/27 tax year, and trusts have £1,500 (HMRC, 2026/27).
  • Rates on the balance. Gains above the allowance are taxed at 18% within the basic rate band and 24% above it for the 2026/27 tax year (HMRC, 2026/27).
  • Joint ownership. Where a chattel is owned jointly, each owner has their own £6,000 threshold against their share.
  • Allowable costs. Acquisition price, buying and selling commissions and other qualifying costs reduce the gain before any rate applies.

A worked example shows the effect. A case sold for £7,500 that originally cost £3,000 produces a gain of £4,500 before relief, but marginal relief caps the chargeable gain at five thirds of the £1,500 excess over the threshold, or £2,500. The annual exempt amount then absorbs most of that balance for an investor with no other gains in the year.

The practical effect is that a portfolio disposed of in measured steps, with proceeds per asset kept modest, may generate little or no chargeable gain even where the wasting asset argument fails. 

How the sets rule affects cases of wine

The sets rule catches more investors than any other part of wine’s capital gains tax treatment. HMRC can treat items that form a set as a single asset where they are sold to the same person, or to connected persons, so the £6,000 threshold applies once across the whole transaction rather than to each bottle.

Bottles of the same wine and vintage are natural candidates. They are similar, they are complementary, and a complete case is generally worth more than the sum of its bottles, which is the test HMRC applies. A 12-bottle case sold intact to one buyer is one disposal against one £6,000 threshold, not twelve disposals against twelve.

Splitting a case across several buyers to stay under the limit is the obvious response, and it carries obvious risk. Where the sales are to connected persons, or form part of a single arrangement, HMRC can aggregate them. Genuine commercial reasons for separate sales are a different matter from timing designed purely to fragment a set.

Format complicates the picture. Magnums, double magnums and mixed formats of the same wine can still be similar and complementary, and an original wooden case sold with its packaging intact makes a strong candidate for set treatment. Investors selling through a merchant or at auction benefit from agreeing how lots will be constructed before the sale, because lot structure often determines how many assets have been disposed of.

Record keeping decides most of these questions in practice. Purchase invoices, storage and rotation records, buyer identities and disposal dates are the evidence that distinguishes a series of independent sales from a divided set.

Further reading from WineCap

These Learn articles cover the surrounding ground in more depth:

Trading in wine and the income tax risk

Trading in wine and investing in wine attract different taxes, and the wasting asset exemption is irrelevant to the first. Where activity amounts to a trade, profits fall within income tax at rates up to 45%, plus National Insurance, rather than within the capital gains regime at all.

HMRC applies the badges of trade to decide which is which. Frequency and volume of transactions, short holding periods, the way purchases are financed, whether stock is actively marketed, and whether the buyer holds any intention of consumption all feed the assessment. An investor who buys allocations and holds them in bond for years looks very different from one who turns stock over monthly at a margin.

Structure matters as much as behaviour. Wine held through a company sits outside the chattels and wasting asset reliefs available to individuals, because those provisions apply to chargeable gains on chattels rather than to corporate trading stock. Wine is also treated as taxable property for self-invested personal pensions, so holding it inside a pension wrapper attracts punitive charges rather than shelter.

The distinction is not always clean, and no single badge decides it. Investors running high-frequency activity, or operating through a company, should take specialist advice before assuming capital treatment applies.

The evidence that supports a wasting asset position

A wasting asset position is only as strong as the evidence recorded behind it. HMRC assesses predictable life on the facts as they stood at acquisition, which means the supporting material needs to exist at that point rather than being assembled after a disposal.

Investors in this position typically keep:

  • Acquisition records showing the date, price and the age of the wine when bought, since predictable life runs from that date.
  • Drinking window evidence from named critics or merchants for the specific wine and vintage, dated at or near acquisition.
  • Storage and condition records, including bonded warehouse documentation, ullage checks and any condition reports.
  • Disposal records identifying the buyer, the date, the quantity and whether the sale formed part of a set.

Professional valuations carry more weight than an investor’s own assessment. Where the wine sits near the boundary, a written opinion from a specialist merchant or valuer, obtained before disposal, is materially more useful than a retrospective argument.

Timing of the evidence matters more than volume. A drinking window retrieved years after purchase is weaker than a dated merchant assessment held from the outset, and HMRC enquiries typically follow a disposal rather than precede it. Recording the position annually costs little and answers the question that arrives later.

Tax treatment depends on individual circumstances and may change. Nothing in this article is tax advice, and readers should consult a qualified adviser on their own position before relying on any exemption.

How fine wine’s tax treatment compares with other investments

Wine’s position looks favourable against most alternative assets and unremarkable against a few. The comparison matters because the wasting asset argument is often part of the reason wine enters a portfolio, and the alternatives carry reliefs of their own.

  • Listed equities and funds. Gains are chargeable at 18% or 24% for 2026/27 unless held inside an ISA or pension, and those wrappers are unavailable to wine (HMRC, 2026/27).
  • Gold. UK legal tender coins such as Britannias and Sovereigns are exempt from capital gains tax, while bars and foreign coins are chargeable in the ordinary way (HMRC, 2026/27).
  • Classic cars. Private motor cars are specifically exempt, which gives them a clarity wine’s position lacks.
  • Art and antiques. These are chattels with long lives, so they attract no wasting asset exemption and rely on the £6,000 threshold alone.
  • Whisky casks. Spirits in cask raise similar wasting asset arguments, though the category has drawn increasing regulatory scrutiny over valuation and ownership practices.

Treating the exemption as a question, not a feature

The wasting asset rule is best understood as a question HMRC asks about a specific bottle on a specific date. That framing changes how a portfolio is built. Acquisition age, disposal sequencing, buyer identity and documentation all shape the answer, and each of them is a decision an investor makes rather than a rule handed down.

The wines most attractive for their ageing potential are the wines least likely to satisfy a sub-50-year predictable life. Investors who understand that tension early can plan around it, using the chattels rules, the annual exempt amount and disposal timing where the exemption itself is doubtful. Those who assume the exemption applies across a cellar may find the assumption tested only once a disposal has already happened, when the options have narrowed considerably.

FAQ: Wine and capital gains tax

Is wine exempt from capital gains tax in the UK?

Wine is exempt only where it qualifies as a wasting asset, meaning a predictable life of under 50 years at the date of acquisition, under sections 44 and 45 of the Taxation of Chargeable Gains Act 1992. HMRC’s guidance states it would normally contend that fine wine kept for periods well in excess of 50 years does not qualify (HMRC, CG76901). Treatment depends on individual circumstances and may change, so independent tax advice is essential.

Does the wasting asset exemption apply to vintage Port?

Fortified wines including vintage Port, Madeira and Sherry have recognised storage lives well beyond 50 years, which places them outside the wasting asset exemption in most cases. A gain on those wines is assessed under the ordinary chattels rules instead, with the £6,000 per asset threshold and the £3,000 annual exempt amount available (HMRC, 2026/27).

How much capital gains tax would I pay on a wine sale?

Where a gain is chargeable, the rate is 18% within the basic rate band and 24% above it for the 2026/27 tax year, after deducting the £3,000 annual exempt amount and any allowable costs (HMRC, 2026/27). A single chattel sold for £6,000 or less produces no chargeable gain at all, and marginal relief limits the gain on proceeds slightly above that figure.

Does selling a case of wine count as one disposal or twelve?

A case sold intact to a single buyer is generally treated as one asset, because bottles of the same wine and vintage are similar, complementary and worth more together than separately. That means one £6,000 threshold applies to the whole case. Selling bottles separately to connected persons, or as part of a single arrangement, can still be aggregated by HMRC.

What records should an investor keep to support a wasting asset claim?

Acquisition invoices showing the date, price and age of the wine at purchase are the foundation, since predictable life is measured from acquisition rather than vintage. Dated drinking window assessments from named critics, bonded storage documentation and full disposal records covering buyer and quantity complete the picture. A written valuation from a specialist merchant obtained before sale carries more weight than a retrospective argument.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.

Categories
Learn

Can you invest in fortified wine? Port, Sherry and Madeira explained

  • Fortified wine covers Port, Sherry and Madeira, three categories that share one technique but create scarcity in entirely different ways.
  • You can invest in fortified wine, though only Port has a published index, which keeps most holdings small and slow to sell.
  • Collectable value rests on bottles that cannot be remade: fixed vintage declarations, drawn-down soleras and aged Madeira that is still drinkable.

Fortified wine produces the longest-lived bottles in the wine trade and the least understood by investors. Port, Sherry and Madeira share one technique, the addition of grape spirit, but they are made differently, age differently and trade differently. This guide explains how each one works, sets out the differences that matter, and shows why fortified wine tends to occupy a small corner of a portfolio while producing some of the most collectable bottles in existence.

What fortified wine is, and why three names dominate

Fortified wine is wine with grape spirit added to it. The addition raises alcohol content, usually to somewhere between 15% and 22%, and it transforms how long the wine survives. That longevity is what makes the category interesting to a collector, because it is the reason genuinely old bottles are available to buy at all.

The practice began as preservation. Wine shipped from Portugal and Spain to northern Europe spoiled on the voyage, and added spirit kept it drinkable. Producers then found the additions improved the wine rather than merely protecting it, and three regions built distinct traditions around the technique.

  • Port comes from the Douro valley in northern Portugal. Producers add spirit part-way through fermentation, which stops the yeast and leaves natural grape sugar in the wine.
  • Sherry comes from Jerez in southern Spain. Producers ferment the wine dry first and fortify it afterwards, so the base wine is nothing like Port.
  • Madeira comes from the Atlantic island of the same name. Producers heat the wine deliberately, which sounds destructive and is the reason Madeira outlives everything else.

Those three account for almost all collector interest. Marsala, Vermouth and Commandaria use the same technique, but they trade in negligible volumes and have no established secondary market.

Port depends on the vintage a house chooses to declare

Port has the simplest structure of the three, and that simplicity is why it dominates trading. In years a house judges exceptional, it declares a vintage, meaning it bottles that year on its own rather than blending it away. Declarations happen roughly three times a decade.

The decision fixes supply permanently. Once a house has declared and bottled, no more of that vintage can ever exist, and every bottle opened reduces what remains. Producers declared 2016 and 2017 back to back, an unusual sequence, then declared nothing generally until 2024.

Five houses carry most of the trade: Dow, Fonseca, Graham, Taylor and Warre. Below declared vintages sit Single Quinta Ports, made from one estate in undeclared years and priced lower, and Late Bottled Vintage Port, made in commercial volumes for early drinking. Only the first two have collector relevance.

Aged tawny and colheita Ports sit outside that hierarchy. Producers mature them in cask until they are ready to drink, so they arrive at maturity on release and appeal to drinkers rather than to collectors.

Sherry is aged in a solera, so it has no vintage

Sherry uses a system that makes vintage dating impossible, and that single fact explains most of its market behaviour. A solera is a stack of barrels holding wine of different ages. Producers draw a portion from the oldest barrels, top those up from the next oldest, and repeat down the chain, so every bottle blends many years together.

The result is an average age rather than a date. Two certifications mark the oldest stock: VOS (Vinum Optimum Signatum) for an average age of at least 20 years, and VORS (Vinum Optimum Rare Signatum) for at least 30 (Consejo Regulador). The Consejo verifies both through laboratory analysis and tasting assessment.

Styles vary more widely than in Port or Madeira. Fino and Manzanilla age beneath a film of yeast called flor, which keeps them pale and dry. Amontillado, Oloroso and Palo Cortado age in contact with air and darken as they do. Pedro Ximenez is sweet and intensely concentrated. Only the oxidative styles and Pedro Ximenez carry VOS or VORS certification, which is where collector attention sits.

For a buyer, this creates a comparison problem. A collector can compare two bottles of 1994 Taylor directly. Comparing two VORS Olorosos means comparing two blends nobody can decompose, from bodegas whose reputations differ. Old solera stock is scarce since producers cannot replace what they draw down, but scarcity without comparability makes pricing difficult.

Madeira is heated on purpose and survives almost indefinitely

Madeira’s production would ruin any other wine. Producers either warm it in heated tanks for months, a process called estufagem, or leave it in casks in warm lofts for years or decades, known as canteiro. Both methods expose the wine to heat and oxygen.

Oxidation is what normally kills wine. Madeira has already been through it, so little remains for time to damage. Bottles from the eighteenth century still open sound, which is true of no other wine category.

Grape variety signals style, and older bottles are usually labelled by grape rather than by house style. Sercial is the driest, followed by Verdelho, Bual and Malmsey, which is the sweetest. Tinta Negra accounts for most volume production. Collector attention concentrates on the four noble varieties.

That produces an unusual market. Antique Madeira exists in drinkable condition in a way old Bordeaux does not, so a collector buying a very old bottle can expect it to be alive. Colheita Madeira, from a single year and aged at least five, and vintage Madeira, aged at least twenty, offer the same durability at far lower prices.

How long can fortified wine age

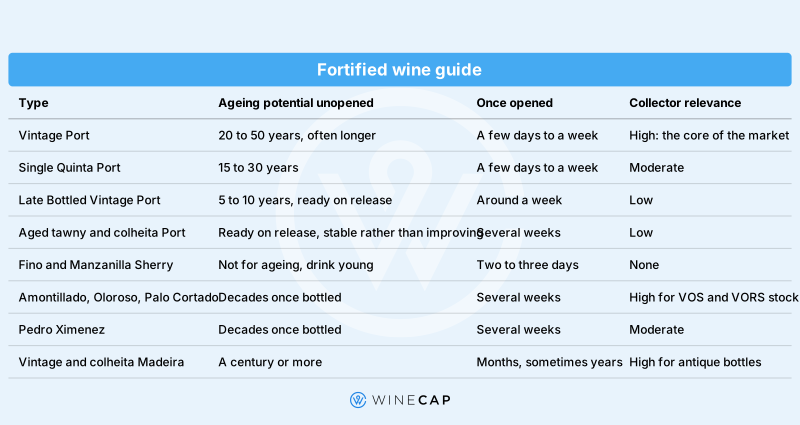
Ageing potential varies more across these three categories than anywhere else in wine. The spans below matter to a buyer for two reasons: they determine how long a bottle can be held before selling, and how quickly it has to be drunk once the cork comes out.

Fortified wine

How fortified wines create scarcity

Scarcity is the common thread, and each category manufactures it differently. Knowing which mechanism applies tells a buyer more than any general view on fortified wine does.

  • Port restricts supply by decision. A house declares or it does not, and once bottled the quantity is fixed. Scarcity is set at the outset and erodes as bottles are drunk.
  • Sherry restricts supply by consumption of the solera. Old stock disappears into bottles and cannot be recreated, because recreating it would require the decades to run again.
  • Madeira restricts supply by survival. Antique bottles are scarce because few were kept rather than because few were made, and the wine’s durability means the survivors remain viable.

Those mechanisms produce different market behaviour. Port has dates, named houses and comparable sales, which supports a functioning secondary market. Sherry has certified ages and reputations, which supports specialist trading. Madeira’s antique tier behaves like an antiques market, moving when a cellar comes to auction rather than with wine prices generally.

Why fortified wine stays a small part of a portfolio

Liquidity is the binding constraint across all three categories. Selling fine wine requires a buyer who wants that specific bottle, and fortified wine has far fewer of them than Bordeaux or Burgundy. Port is the only category with a published index. Liv-ex launched the Port 50 in October 2018, tracking the ten most recent vintages from the five main houses. 

Moreover, HMRC’s Capital Gains Manual states that the wasting-asset exemption, which covers assets with a predictable life of 50 years or less, would not apply to Port and other fortified wines given their long storage life (HMRC, CG76901). The longevity that makes these wines collectable is the reason they fall outside a treatment some still wines can rely on. Treatment depends on individual circumstances and may change, so take independent tax advice.

The collectable case rests on bottles that cannot be remade

Collector demand is where fortified wine looks strongest, and it comes from rarity rather than from market momentum. 

Results at the top of the Madeira market show what that rarity attracts. A bottle dated to around 1715 sold for roughly $39,000 in 2016, and a nineteenth-century Liberty Hall bottling reached close to $16,000 at Christie’s in 2018. These are selected examples from the very top of the market rather than representative Madeira prices.

Condition determines much of what a buyer will pay. Vintage Port is bottled unfiltered and throws heavy sediment, so undisturbed storage matters more here than in most categories. Original cases, intact capsules, legible labels and an unbroken bonded storage record all feed into price, and a bottle without documentation sells at a discount whatever the vintage.

How to buy fortified wine for the long term

Buying well matters more than timing here, because the exit can be slower than more liquid fine wines across all three categories. 

A sensible approach would be:

  • Start with declared vintage Port from one of the five main houses.
  • Treat Single Quinta Port and VORS Sherry as smaller positions.
  • Buy aged Madeira only where provenance and condition are documented.
  • Store everything in bond, with condition records and an unbroken storage history.
  • Take independent tax advice before assuming any particular treatment applies.

Fortified wine complements a core holding in Bordeaux, Burgundy or Champagne rather than substituting for any part of it.

What fortified wine offers

Fortified wine gives a collector access to something the rest of the wine world cannot supply: bottles that are genuinely old and genuinely drinkable. A nineteenth-century Madeira is not a curiosity kept for display. It works, which is why a small group of buyers pursues it regardless of what fine wine indices are doing.

What it asks in return is patience and effort. The research burden falls on the buyer, published pricing barely exists outside Port, tax treatment is less favourable than for some still wines, and selling takes time. Those costs are why fortified wine belongs at the edge of a portfolio rather than the centre, and also why its rarest bottles keep finding buyers.

FAQ: Fortified wine investment

What counts as fortified wine? 

Fortified wine is wine with grape spirit added, which raises alcohol to roughly 15% to 22% and greatly extends how long the bottle lasts. Port, Sherry and Madeira account for almost all collector interest, though Marsala, Vermouth and Commandaria use the same technique. Only the first three have a meaningful secondary market.

Can you invest in fortified wine? 

You can, though the market is small. Most buyers treat fortified wine as a collectable with a modest investment market attached rather than as a core holding. 

Which fortified wine is easiest to sell? 

Declared vintage Port from Dow, Fonseca, Graham, Taylor or Warre is the easiest, because those five houses carry most of the category’s secondary market activity and have comparable sales going back decades. Sherry and Madeira usually require a specialist merchant or an auction consignment, which can take months. Liquidity should shape position size before price does.

Do you pay capital gains tax on Port? 

HMRC’s Capital Gains Manual states that the wasting-asset exemption, which applies to assets with a predictable life of 50 years or less, would certainly not apply to Port and other fortified wines because of their long storage life. Gains may therefore fall within capital gains tax where some still wines would not. Treatment depends on your individual circumstances and may change, so take independent tax advice.

How long can fortified wine be kept? 

Vintage Port typically improves for several decades and lasts far longer in good storage. Madeira outlasts everything, with eighteenth-century bottles still opening sound, because its production already exposes the wine to heat and oxygen. Old Sherry drawn from a solera is similarly durable once bottled, though the bottling date matters rather than a vintage.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.

Categories
News

Bordeaux’s commemorative bottles: Does the gold label pay off?

  • Bordeaux’s 2025 vintage arrives alongside anniversary bottles from Gruaud Larose (300 years) and Brane-Cantenac (100 years), pairing an exceptional harvest with collectable packaging.
  • Mouton Rothschild’s golden 2000 vintage, Bordeaux’s best-known commemorative bottle, has appreciated close to 750% since release.
  • Charity auction results for artist bottles, such as Ornellaia’s Vendemmia d’Artista, reflect philanthropy and uniqueness rather than a reliable secondary market benchmark.

Bordeaux has a habit of marking its anniversaries in gold, and 2025 gives it plenty to celebrate. Chateau Gruaud Larose turns 300, Chateau Brane-Cantenac marks a century under the Lurton family, and both have used the vintage to release decorated bottles alongside a harvest that produced limited yields but genuine quality. The pattern is not new. For decades, Bordeaux estates have paired milestone years with special packaging, and some of those bottles, most famously Mouton Rothschild’s 2000 vintage, have gone on to outperform their standard-issue counterparts by a wide margin. This piece works through the current crop of anniversary releases, what the data says about whether a decorated bottle is worth paying up for, and how two of Italy’s best-known names, Sassicaia and Ornellaia, approach collectability in very different ways.

Bordeaux’s 2025 vintage arrives wrapped in anniversaries

Gruaud Larose, the Saint-Julien Second Growth founded in 1725 by Joseph-Stanislas Gruaud, marks 300 years of history with its 2025 release. The bottle is etched and screen-printed with golden leaves from the Cabernet Sauvignon vine, the grape that makes up 77% of this year’s blend. It is available across the full range of formats, from standard bottle through to jeroboam, and buying En Primeur (purchasing wine before it is bottled, based on cask samples) allows collectors to select and even customise larger formats for their own celebrations.

Chateau Brane-Cantenac, in Margaux, marks 100 years under the Lurton family with a golden label for 2025. Leonce Recapet acquired the property in 1925, and it has passed through five generations to reach Henri Lurton, who has overseen the estate since 1992 and handed ownership to his children in 2022. The embossed sun on the new label was inspired by a medallion found on a 19th-century Brane-Cantenac bottle, and it doubles as a nod to Henri’s father Lucien, whose name translates loosely as “bringer of light.”

Not every 2025 anniversary bottle looks backwards. Chateau Grand-Puy-Lacoste, the Pauillac classified growth, used the vintage to christen a new gravity-fed cellar, the result of a decade-long renovation led by Francois-Xavier Borie and his daughter Emeline. The bottle carries a screen-printed image of the chateau itself, available in everything from 75cl to imperial format.

The timing matters for investors weighing up whether to buy in. Exceptional weather across 2025 produced limited yields but genuinely strong quality, yet the En Primeur market did not respond enthusiastically across the board. That gap between the quality in the glass and the market’s muted reaction is the setting in which a well-chosen anniversary bottle, from an estate with a track record of translating milestones into price appreciation, tends to stand out from the pack.

Golden bottles carry Bordeaux’s most collectable history

The tradition of decorating the bottle itself, rather than just the label, runs deeper than any single vintage. A handful of releases have become genuine collector benchmarks:

  • Mouton Rothschild 2000 features a golden Augsburg Ram relief-enamelled directly onto the glass, inspired by a 16th-century silver-gilt drinking vessel in the chateau’s own museum. Since 1945, Mouton has commissioned a different artist for its label every year, a roll call that includes Dali, Picasso, Miro, Warhol and Hockney, but the millennium vintage is the one time the bottle itself became the artwork.
  • Chateau Angelus 2012 received a golden version of its bell emblem to mark both its promotion to Premier Grand Cru Classe A and the 230th anniversary of the Bouard de Laforest family’s arrival in Saint-Emilion. The gold, 21.7 carats of it, was enamelled onto the glass and fired at 500 degrees Celsius.
  • Chateau Margaux 2015 replaced its label entirely with a screen-printed image of the Palladian chateau, marking the building’s bicentenary, the completion of Norman Foster’s new facilities, and the final vintage overseen by longstanding managing director Paul Pontallier.
  • Chateau Cos d’Estournel 2020 marked 200 years of the estate and 20 years under owner Michel Reybier with a golden bottle depicting its distinctive Asian-inspired architecture.
  • Chateau Ducru-Beaucaillou and Chateau Smith Haut Lafitte, both releasing 2020 vintages for their own 300th and 30th anniversaries respectively, took a lighter touch, redesigning the label rather than decorating the glass.

Family anniversary collections extend beyond a single vintage

Some estates mark their milestones with a collection spanning several vintages rather than one decorated bottle, and these sets carry their own logic for a collector. Chateau Rauzan-Gassies, the Margaux Second Growth, is marking the 90th anniversary of the Quie family’s purchase of the property with a wooden case holding six bottles across three vintages, two each of 1966, 1996 and 2016. The 1966 honours grandfather Paul Quie, who bought the estate in 1946. The 1996 marks the era of his son Jean-Michel Quie. The 2016 represents today’s owners, twins Anne-Francoise and Jean-Philippe Quie, who have run the property since 2000.

The Barton family, owners of Chateau Leoville Barton and Chateau Langoa Barton, have built a similar tribute around consecutive anniversaries. The 2021 vintage of Langoa Barton marked 200 years since the family bought the estate, arriving in Saint-Julien in 1821, with a hand-drawn label by Anne-Lise Yandell built around four themes: origin, heritage, nature and evolution. A limited coffret, of which only 200 were produced, paired individual bottles from 1994, 2000, 2009 and 2016 with a magnum of the 2021 vintage bringing all four images together. Chateau Leoville Barton follows in 2026 with its own 200th anniversary, reviving an Art Deco label the estate used between the 1930s and 1960s.

Chateau Talbot, also in Saint-Julien, marked a century of Cordier family ownership with its 2018 vintage, using a silk-screened image representing a pillar of the estate’s barrel cellar. Chateau Leoville Poyferre’s 2020 vintage celebrated 100 years of Cuvelier family ownership, now in its fourth generation under Sarah Lecompte Cuvelier, with a gold-inlaid bottle depicting the property’s terroir.

Multi-vintage collections matter to investors for a different reason than single decorated bottles:

  • A complete, unbroken set from a single family’s anniversary collection tends to hold together at resale, since buyers value completeness as much as any individual vintage inside it.
  • Provenance matters more here than usual. A case is only worth its full premium if every bottle inside carries the same documented history, ideally held in bond throughout.
  • These releases are typically produced in far smaller numbers than a standard vintage, which supports scarcity value but also means liquidity is thinner than for a widely traded standard case.

Do commemorative labels actually add investment value?

Investors reasonably ask whether a decorated bottle is worth a premium over the standard release, or whether it is simply good marketing. The evidence from Mouton Rothschild, the estate with the longest and most closely tracked history of special editions, suggests the premium is real and measurable.

Prices of the last ten Mouton vintages have risen by an average of 5% in the month following each year’s artist label announcement. The 2012 vintage, labelled by Miquel Barcelo, rose 14.9% in that window, and the 2018 vintage, labelled by Xu Bing, rose 12.6%. Over the same decade, Mouton’s index has risen 44% on average, a run that has outpaced many of its Bordeaux peers.

The 2000 vintage remains the clearest case study. Released at a negociant price (the price at which a wine merchant first sells the wine) of around 250 euros, it now trades at roughly 1,550 euros, and its total appreciation since release is close to 750%. The bottle weathered the Bordeaux downturn of 2011 to 2014, when other First Growths fell sharply, partly because Asian demand for the golden ram design held firm, and partly because 2015, the Chinese zodiac year of the sheep, gave collectors a fresh reason to buy.

Angelus 2012 shows the same effect, albeit at a smaller scale. It trades at more than double its release price today, a solid return but well short of Mouton’s, and a reminder that the anniversary story and the underlying vintage quality both matter to how far a commemorative bottle’s price will travel. Mouton’s advantage is structural as much as sentimental: eight decades of consistent artist commissions have trained the market to treat each new label as a genuine event, which is precisely why a bump of this size shows up so reliably in the trading data rather than in a single standout year.

Charity auction prices are not a secondary market signal

Not every headline-grabbing result for a decorated bottle tells investors what they think it tells them. Ornellaia’s annual Vendemmia d’Artista auction, now in its 18th year, invites a contemporary artist to reinterpret each vintage, then sells a small run of large-format and one-off bottles for charity. The 2023 edition, featuring performance artist Marina Abramovic’s interpretation of the vintage, raised 128,216 euros for the Solomon R. Guggenheim Foundation, with a unique nine-litre bottle signed by Abramovic and paired with a vinyl record and a private dinner selling for 23,560 euros against a presale estimate of 20,000 to 40,000 euros.

Results like that are genuinely impressive, but they price a one-off collectable and a philanthropic donation as much as a wine. A buyer cannot purchase a second signed nine-litre bottle at that price, cannot easily resell it against a known benchmark, and is paying in part for the artist’s name and the cause attached to the sale. That makes it a poor proxy for what a standard case of Ornellaia is worth on the open secondary market, where pricing is set by ordinary supply, demand and vintage quality rather than by auction theatre.

What this means for a fine wine portfolio

A commemorative bottle is worth buying for the story, the packaging and the occasion it marks. Whether it is worth buying as an investment depends entirely on which part of the equation is doing the work. Mouton’s 2000 vintage shows that decorated glass attached to a genuinely great vintage, from an estate with decades of established artist-label history, can outperform the standard market by a significant margin. However, investors weighing up a commemorative release are better served asking about the vintage quality and the estate’s track record first, and treating the decoration as a bonus rather than the reason to buy.

FAQ: Commemorative wine bottles

Do commemorative or artist-label bottles actually trade at a premium?

Some do. Mouton Rothschild’s 2000 vintage, decorated with a golden Augsburg Ram, has appreciated close to 750% since its release, while Angelus’s 2012 golden bottle trades at more than double its release price. The premium tends to track the underlying vintage quality as much as the packaging itself.

Are charity auction results for artist bottles a reliable price guide?

Not necessarily. Ornellaia’s Vendemmia d’Artista auction, which raised 128,216 euros in its most recent edition, prices unique, signed lots bundled with experiences and a charitable donation. Those figures do not reflect what a standard case trades for on the secondary market.

Should investors pay a premium for a decorated bottle over a standard release?

Only where the underlying wine also stands on its own merits. Sassicaia’s 2018 50th anniversary vintage appreciated from around £1,800 to roughly £1,947 per case with no decorated packaging at all, showing that vintage quality can carry a price on its own.

How liquid are commemorative bottles compared with standard releases?

Standard-format anniversary bottles from established estates, such as Mouton’s 2000 vintage, trade actively through the same merchant and auction channels as any other fine wine. Large-format, hand-signed or one-off pieces, by contrast, are far less liquid and are better treated as collectables than tradeable assets.

Does a golden or decorated bottle affect long-term storage value?

Decoration does not change how a wine ages, but original wooden cases and undisturbed packaging, decorated or not, support provenance, and provenance affects resale value. Wines held in bond in a recognised bonded warehouse retain the strongest documented provenance.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.

Categories
Learn

White Burgundy explained: Appellations, producers and ageing

  • White Burgundy is dry white wine from the Bourgogne region of France, almost exclusively Chardonnay.
  • The region’s whites span four sub-regions, from Chablis in the north to the Maconnais in the south, with sharply different styles and price levels.
  • Ageing potential runs from two years at regional level to over three decades at Grand Cru.

White Burgundy is the dry white wine of France’s Bourgogne region, made almost entirely from Chardonnay and named after the place it comes from rather than the grape in the bottle. It is also the region’s main business: white wine accounts for 61% of Bourgogne production by volume, against 27% for red and rose (BIVB, 2024). This guide covers the grape, the four sub-regions, the classification tiers, the producers who define the category, and how long the wines actually last.

What is white Burgundy?

White Burgundy is any dry white wine produced within the delimited Bourgogne appellations of eastern France, running roughly 230 kilometres from Chablis in the north to the Maconnais in the south. Labels carry the name of a place, not a grape, which is the single biggest source of confusion for anyone new to the category. A bottle marked Meursault, Chablis or Puligny-Montrachet is Chardonnay, but the label will not say so.

Geology defines the style as much as winemaking does. Burgundy sits on a band of Jurassic limestone and marl, and that soil, combined with a cool continental climate, gives Chardonnay higher acidity and more mineral definition than the same grape grown in warmer places.

Chardonnay is the grape, with three exceptions

Chardonnay accounts for 57% of plantings across Bourgogne, ahead of Pinot Noir at 34% (BIVB). It is behind every well-known white appellation in the region, from Petit Chablis to Le Montrachet. Three exceptions explain labels that otherwise look out of place:

  • Aligote, at 6% of plantings, is Burgundy’s second white grape. It appears as Bourgogne Aligote at regional level and as Bouzeron in the Cote Chalonnaise, the only village appellation dedicated to it.
  • Sauvignon Blanc is permitted in Saint-Bris, near Chablis, Burgundy’s only Sauvignon appellation.
  • Cremant de Bourgogne, the region’s traditional-method sparkling wine, accounts for 12% of production (BIVB, 2024).

How Burgundy classifies its white wines

Burgundy classifies wine by vineyard rather than by producer, and the hierarchy is geographical and permanent. A plot carries its classification for good, which is why one producer can offer wines at four tiers from vineyards a few hundred metres apart.

Burgundy Classification

Source: BIVB, September 2024, five-year average 2019 to 2023. 

The white wine regions of Burgundy, north to south

Burgundy’s whites come from four distinct areas, and the differences between them are larger than newcomers expect. Chablis sits closer to Champagne than to Beaune and makes taut, mineral wine with little oak. 

The Cote de Beaune in the middle produces the richest and most expensive whites in the world. 

The Cote Chalonnaise and Maconnais further south offer rounder, earlier-drinking wine at a fraction of the cost.The white wine regions of Burgundy

Chablis owes its character to Kimmeridgian soil, a limestone and marl formation studded with the fossilised oyster shells of Exogyra virgula. Its Premier Cru covers 40 climats across 770 hectares and 13% of Chablis production (BIVB Chablis, 2023). At the southern end, Pouilly-Fuisse gained the Maconnais’s first Premier Crus in September 2020, when INAO approved 22 climats across 194 hectares, the first new Premier Cru tier in any Burgundian appellation since 1943.

Meursault and Puligny-Montrachet compared

Meursault and Puligny-Montrachet sit side by side on the same limestone slope, and the difference between them is the most useful comparison in white Burgundy.

Meursault is broader, warmer and more forgiving, and drinks well earlier. Puligny is tighter, higher-toned and more mineral, and often needs several more years to show what it has.

Meursault and Puligny-Montrachet compared

The distinction most often credited is drainage. Puligny’s higher water table restricts cellar depth in the village and contributes to the tension in its wines, while Meursault’s deeper, warmer soils give the fuller texture it is known for. Between them sits Chassagne-Montrachet, mineral and succulent with a hazelnut character, and above the slope lies Saint-Aubin, which shares the same limestone at a considerably lower price.

Which producers make the best white Burgundy?

Producer matters more than tier in Burgundy – these are the domaines most often cited as reference points in each area:

  • Chablis: Domaine Francois Raveneau and Domaine Vincent Dauvissat set the benchmark, with William Fevre and Louis Michel recognised for classically styled Premier and Grand Cru wines.
  • Meursault: Coche-Dury, Domaine Roulot, Domaine des Comtes Lafon and Arnaud Ente define the village at the top, alongside Pierre-Yves Colin-Morey.
  • Puligny-Montrachet: Domaine Leflaive is the historical reference point, with Etienne Sauzet long established.
  • Chassagne-Montrachet: Domaine Ramonet is the most cited, and the village is a reliable source of value at Premier Cru level.
  • Corton-Charlemagne: Bonneau du Martray holds the largest single stake and the longest reputation on the hill.
  • Maconnais and Saint-Aubin: Guffens-Heynen, J.A. Ferret and Domaine Hubert Lamy raised expectations for southern Burgundy and for Saint-Aubin respectively.

Allocation rather than availability is the constraint at the very top. Coche-Dury and Raveneau sell to long-standing customers in tiny quantities, which is why their wines surface mainly on the secondary market.

Burgundy’s white Grand Crus

Burgundy’s white Grand Crus are few and very small. Five sit in the Montrachet cluster, straddling Puligny-Montrachet and Chassagne-Montrachet: Le Montrachet itself, Chevalier-Montrachet, Batard-Montrachet, Bienvenues-Batard-Montrachet and Criots-Batard-Montrachet. Le Montrachet covers around eight hectares. Criots-Batard-Montrachet, the smallest, covers 1.57 hectares and yields roughly 8,900 bottles a year (BIVB, five-year average 2017 to 2021).

Corton-Charlemagne, around the hill of Corton to the north, is the largest white Grand Cru and spans three communes: Pernand-Vergelesses, Aloxe-Corton and Ladoix-Serrigny. Chablis has seven Grand Cru climats of its own: Blanchot, Bougros, Les Clos, Grenouilles, Preuses, Valmur and Vaudesir. Together they cover 99 hectares and 1.5% of Chablis production (BIVB Chablis, 2023).

How long does white Burgundy age?

White Burgundy ages for less time than red Burgundy, and considerably less than its reputation suggests. Regional wines are made for early drinking, village wines reward a few years, and the best Cote de Beaune Premier and Grand Crus run for decades.

 How long does white Burgundy age

Premature oxidation and older bottles

Premature oxidation, known as premox, is why experienced buyers treat older white Burgundy with caution. Affected bottles turn deep gold and lose their fruit years before expected, and nothing short of opening one reveals it. The problem became widely apparent in wines from the mid-1990s onwards and dominated discussion of the category for close to two decades.

No single cause was ever established. Reduced sulphur dioxide at bottling, variable cork quality, aggressive lees stirring and changes to pressing have all been implicated. Producers responded by raising sulphur levels, adopting technical closures such as Diam and revising cellar practice, and reported incidence has fallen substantially since the early 2010s. Calling the problem solved would overstate it. For a buyer, the practical conclusion is to favour younger vintages unless a bottle’s storage history is documented.

Recent white Burgundy vintages at a glance

Recent vintages have varied more in volume than in quality, with three short harvests in five years. Whites generally fared better than reds through the harder years, notably 2024.

Recent white Burgundy vintages

Sources: Decanter vintage guide and Burgundy 2024 En Primeur report (Charles Curtis MW, updated January 2026), Jancis Robinson vintage notes.

Serving and pairing white Burgundy

Serving temperature matters more for white Burgundy than for almost any other white wine, and most bottles are served too cold. Chablis and village wines show best at 10 to 12 degrees Celsius. Premier and Grand Cru wines need 12 to 14 degrees to open properly, closer to cellar than fridge temperature (BIVB).

Pairing follows the same north-to-south logic as the wines. Chablis and other high-acid whites suit oysters, shellfish and goat’s cheese. Richer Cote de Beaune whites work with lobster, monkfish, veal and poultry in cream and mushroom sauce (BIVB). Mature grand cru handles foie gras and caviar, which is where the region’s reputation for luxury pairings comes from.

Buying and cellaring white Burgundy

Provenance matters more here than for most wine, precisely because oxidation cannot be inspected. Buyers of older bottles study storage history, fill level and closure condition, and discount anything with an unclear past. Wine kept in a bonded warehouse retains a continuous record, which is the main reason collectors buy in bond rather than duty paid.

Burgundy’s whites also attract investor interest, and the region accounted for 69.3% of white wine traded by value on Liv-ex in 2026 to date. Fine wine values fall as well as rise, and past performance is not a guide to future returns, so anyone buying with resale in mind should treat white Burgundy as a long-term holding.

Where to start with white Burgundy

The most useful thing to know about white Burgundy is that its hierarchy of price does not map onto a hierarchy of pleasure. A village Chablis from a careful grower or a Saint-Aubin Premier Cru teaches a drinker more about the region than an expensive bottle from a weak vintage, and the gap between good and indifferent producers at the same address is wider than the gap between adjacent tiers.

That makes producer the first thing to learn and appellation the second. A handful of bottles worked north to south, from names with a track record, will build a clearer picture of the region than any single Grand Cru.

FAQ: White Burgundy

Is Chablis white Burgundy?

Yes. Chablis is the northernmost white wine district of the Bourgogne region and is made entirely from Chardonnay, which makes it white Burgundy in both legal and stylistic terms. It sits closer to Champagne than to Beaune, and its cool climate and Kimmeridgian limestone soil give it a leaner, more mineral style than the richer whites of the Cote de Beaune.

Is white Burgundy the same as Chardonnay?

Almost always. Chardonnay accounts for 57% of plantings across Bourgogne (BIVB) and is the grape behind every well-known white appellation in the region. The exceptions are Bourgogne Aligote and Bouzeron, both made from Aligote, and Saint-Bris, made from Sauvignon Blanc.

Does Meursault have a Grand Cru?

No. Meursault is the only major white wine village of the Cote de Beaune without a grand cru vineyard, despite producing some of Burgundy’s most expensive whites. Its finest sites are premier crus, principally Perrieres, Genevrieres and Charmes, and the best examples reach prices comparable with grand cru wines from neighbouring villages.

What is premox in white Burgundy?

Premox is short for premature oxidation, where a white Burgundy turns deep gold and loses its fruit years before expected. It affected wines from the mid-1990s onwards, and no single cause was established, though low sulphur levels and cork quality were both implicated. Reported incidence has fallen substantially since the early 2010s.

Why is white Burgundy so expensive?

Scarcity explains most of it. Grand Cru accounts for just 1% of Bourgogne production, vineyard boundaries are fixed by appellation law and cannot be extended, and holdings are fragmented among many small growers. Recent short harvests, including a 2024 crop down more than 30% on 2023, have tightened supply further.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.

Categories
Learn

What makes Petrus the world’s most valuable Bordeaux wine?

  • Chateau Petrus has no official classification, yet it commands a higher average price than every Bordeaux First Growth on the secondary market.
  • Liv-ex ranked Petrus fourth in its 2025 Classification at over £31,000 a bottle, ahead of Latour and Lafite by a wide margin.
  • Petrus produces around 30,000 bottles a year from just 11.4 hectares, with no second wine to absorb rejected fruit.

Chateau Petrus sits outside every formal hierarchy in Bordeaux and still outprices all of them. Pomerol has never been classified, so Petrus carries no rank, no growth status, and no crest to justify its position. Its case rests instead on a unique patch of clay, a tiny production run, and seven decades of disciplined ownership under the Moueix family. These ten facts explain why Petrus trades as the most expensive Bordeaux on the secondary market and what that means for an investor weighing it against classified First Growths.

1. The blue clay boutonniere that no other estate can copy

Petrus sits on a geological anomaly rather than a brand story. The Pomerol plateau contains roughly 20 hectares of a raised mound known locally as the boutonniere (buttonhole), where the topsoil and subsoil are packed with iron-rich blue clay unlike anything found in neighbouring vineyards. Petrus occupies 11.4 hectares of that mound, more than half of the entire deposit, at the highest point in the appellation.

The clay behaves differently from the gravel and sand that dominate the rest of Pomerol. It swells and seals when wet, then holds moisture through dry summers, feeding the vines steadily rather than in the stop-start pattern typical of free-draining soils. This cannot be replicated. No amount of capital can buy a second boutonniere; Petrus and its immediate neighbours hold a finite, non-transferable input that underwrites the entire investment case, their excellence, their price point and their growth.

2. No classification, no chateau, and a label that just says Petrus

Pomerol has never been classified, a gap that sets it apart from the rest of Bordeaux. The comparison is stark:

  • Medoc and Sauternes: fixed by the 1855 Classification, unchanged for over a century except for Mouton Rothschild’s 1973 promotion.
  • Saint-Emilion: classified in 1955 and revised periodically, most recently amid legal disputes over methodology.
  • Pomerol: never classified at all, its reputation built entirely after the appellation gained recognition in the mid-20th century, too late to be included in 1855.

Petrus has no grand building either. The estate operates from a modest farmhouse, and the label itself never carries the word “chateau,” reading simply “Petrus, Pomerol.” For investors, this is the clearest possible illustration that price and prestige here rest purely on market consensus and critical reputation.

That reputation is not a recent development. Cocks and Feret, the 19th century’s standard reference guide to Bordeaux still being published today, listed Petrus in 1868 alongside Chateau Trotanoy and just behind Vieux Chateau Certan. A decade later, Petrus won a gold medal at the 1878 Paris Exposition Universelle, an event significant enough at the time to establish a selling price on a par with a Medoc Second Growth, the first Pomerol wine ever to reach that level. The absence of a formal classification has never stopped the market from ranking Petrus among Bordeaux’s elite.

3. From a Libourne hotelier’s widow to a global luxury house

Petrus changed hands slowly and deliberately across the 20th century. The Arnaud family sold up in 1917, and by 1925 Madame Edmond Loubat, who ran a hotel in nearby Libourne, began buying shares. She held full ownership by 1945 and insisted Petrus be priced alongside the First Growths, a conviction that shaped everything that followed.

That same year, negociant Jean-Pierre Moueix secured exclusive selling rights, and the partnership between the two built Petrus into an international name. Following Madame Loubat’s death in 1961, Moueix gradually consolidated control, buying out remaining family shares by 1964 and expanding the vineyard from 7 to 11.4 hectares in 1969 with land purchased from neighbouring Chateau Gazin.

Jean-Francois Moueix now owns the estate with his children. In September 2018, the family sold a 20 percent stake to Colombian-American billionaire Alejandro Santo Domingo, a signal of the kind of institutional capital now willing to buy into Pomerol’s top asset.

Technical continuity has mattered just as much as ownership continuity. Jean-Claude Berrouet served as winemaker for 45 consecutive vintages before retiring in 2008, when his son Olivier Berrouet took over, an unbroken line of stewardship that few Bordeaux estates can match. In 1947, Madame Loubat even presented two magnums of the 1938 vintage to the Lord Mayor of London to mark the wedding of Princess Elizabeth, an early sign of the estate’s ambition to sit among the wines fit for royal occasions.

4. A single grape variety, only since 2010

Petrus is 100 percent Merlot, but that purity is recent. Earlier vintages carried a small proportion of Cabernet Franc, and the shift to a pure Merlot blend only became permanent at the end of 2010. 

The average vine age across the vineyard now exceeds 45 years. Old vines produce lower yields and smaller berries, concentrating flavour and structure in ways young vines cannot replicate regardless of technique in the cellar. For an investor comparing Petrus with Cabernet-dominant Left Bank First Growths, the single-variety approach removes one common source of vintage variation and puts the burden of consistency squarely on terroir and vine age instead.

5. The frost that built a tradition

A severe winter frost in 1956 destroyed roughly two-thirds of the Petrus vineyard. Rather than replanting, Madame Loubat chose to coppice (recepage), cutting the surviving vines back hard to force new growth from established root systems, a technique untried in the region at the time. Her gamble worked, and the practice became the house method whenever vines need renewal.

That single decision is why Petrus has such old vines and a reminder that scarcity value is often the product of specific historical choices rather than an inherent, permanent feature of a vineyard.

6. The vintages that define Petrus

Petrus has a settled list of legendary vintages that recur across critical assessments and auction records: 1929, 1945, 1947, 1961, 1964, 1982, 1989, 1990, 2000, 2005, 2009, and 2010. Robert Parker awarded a perfect 100-point score to nine of these, including 1921, 1929, 1947, 1961, 1989, 1990, 2000, 2009, and 2010.

Just as notable is what does not exist. In 1956, 1965, and 1991, the estate judged the harvest unfit for release and declared no wine at all under the Petrus name, a decision made easier by the absence of a second label to absorb the shortfall.

  • 1947 and 1961: among the most sought-after vintages in Bordeaux, commanding auction prices as high as £12,500 a bottle for exceptional examples.
  • 1990 and 2000: modern benchmark vintages combining critical acclaim with more available stock than the pre-war years.
  • 2009 and 2010: back-to-back perfect-score vintages that remain the most liquid entry points into top-tier Petrus today.

7. Petrus has no second wine

Petrus produces an average of just 30,000 bottles a year, roughly 2,500 cases, from a stringent pre-assemblage selection process. Parcels that fail to meet the required standard are simply rejected from the Grand Vin. Unlike most Bordeaux estates, there is no second label to catch that declassified fruit and sell it under a different name.

The consequence is a permanently constrained supply that cannot expand even in generous vintages, because quality control operates as a hard ceiling rather than a sorting exercise. Total annual output stays essentially fixed regardless of vineyard conditions.

8. Priced above every First Growth

Petrus does not need classified status to command the highest price in Bordeaux. In the 2025 Liv-ex Classification, which ranks wines by trading value over the preceding year, Petrus placed fourth overall at an average price above £31,000 a bottle, the highest of any Bordeaux wine included.

  • Petrus: fourth in the 2025 Liv-ex Classification, ahead of every First Growth.
  • Chateau Latour: ranked 36th in the same table.
  • Chateau Lafite Rothschild: ranked 39th, despite its own strong brand recognition.

Alongside neighbouring Le Pin, whose own production runs to just a few thousand bottles a year, Petrus leads a small group of Pomerol wines that consistently outprice the classified Medoc estates. Wine-Searcher has separately placed Petrus around sixth among the world’s most expensive wines across all producing countries, behind only a handful of ultra-rare Burgundies, proof that in this corner of Bordeaux, reputation has entirely decoupled from official rank.

9. Petrus skips En Primeur

Most Bordeaux estates release new vintages as futures during the En Primeur campaign each spring, selling wine still ageing in barrel. Petrus, through the Moueix negociant house, has repeatedly declined to show at the standard early tastings, presenting its wines later once fermentation and ageing have progressed further.

This mirrors Chateau Latour’s 2012 decision to withdraw from En Primeur entirely and release only when a wine is ready to drink. For investors, the practical effect is that positions in Petrus are built on the post-release secondary market through merchants, brokers, or auction.

10. From Le Pavillon’s corner table to the International Space Station

Petrus became a status symbol in New York during the 1960s, largely through restaurateur Henri Soule, whose Le Pavillon served it to a clientele that reportedly included shipping magnate Aristotle Onassis. Wine writer Alexis Lichine observed at the time that ordering Petrus had become as much about signalling status as appreciating the wine itself.

That cultural pull has never really faded. In 2021, a bottle of Petrus 2000 that had spent 14 months aboard the International Space Station as part of a scientific ageing study sold privately through Christie’s for approximately $1 million, far above the price of an identical bottle that stayed on earth. A reminder if one were needed that Petrus’s mythology now carries its own commercial weight, separate from any single vintage’s technical merits.

Where Petrus sits in a fine wine portfolio

Petrus makes the case that reputation, not classification, ultimately sets price in Bordeaux. Its combination of unrepeatable terroir, permanently capped output, and disciplined ownership has produced a wine that trades above every First Growth without holding any official rank at all. That is a powerful signal for long-term value, but it comes paired with genuine concentration risk: a market this thin, built around roughly 30,000 bottles a year, can move sharply in either direction on comparatively modest shifts in demand.

For most portfolios, Petrus works best as a concentrated, high-conviction position rather than a core holding, sitting alongside broader exposure to classified Bordeaux, Burgundy, and other Pomerol names such as Le Pin. Its scarcity is precisely what makes it valuable, and precisely why it should never carry outsized weight on its own.

FAQ: Investing in Chateau Petrus

Is Chateau Petrus a good wine investment? 

Petrus has a strong long-term track record and currently trades as the highest-priced Bordeaux on Liv-ex, ranking fourth in the 2025 Classification ahead of every First Growth. Its appeal rests on genuine scarcity, roughly 30,000 bottles a year with no second wine, but that same scarcity means thinner trading volumes than more widely available First Growths.

How much does a bottle of Petrus cost? 

Prices vary enormously by vintage and condition. Its current average Market Price on Wine Track sits at £29,700 per 12×75 case.

Is Petrus easy to buy and sell?

Petrus trades less frequently than the classified First Growths simply because so little of it exists, but strong global demand and its position in the Liv-ex Classification indicate a functioning, active secondary market. Investors should expect wider bid-offer spreads than for higher-volume Bordeaux names.

What is the best Petrus vintage to buy?

The 2009 and 2010 vintages, both awarded perfect scores by Robert Parker, are generally seen as the most accessible entry points into top-tier Petrus today, combining critical acclaim with comparatively more available stock than pre-war legends like 1947 or 1961.

How does Petrus compare to Le Pin as an investment?

Petrus and Le Pin are the two Pomerol wines that consistently outprice the classified Medoc estates, though Le Pin’s production is smaller still, around 6,000 to 12,000 bottles a year depending on vintage. Petrus offers a longer track record and slightly deeper trading history, while Le Pin trades on even greater rarity.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.

Categories
News

Harvest 2026: Europe’s earliest picking on record as heat reshapes the vintage

Champagne, Bordeaux and Burgundy are all tracking towards record-early picking dates, while Italy and Spain report similar acceleration. Growers are weighing smaller yields against a scramble to preserve freshness in the fruit.

  • Champagne is on course for the earliest harvest start in its recorded history, with picking expected from 15 August.
  • The wine harvest 2026 will be smaller across France, with Bordeaux facing losses of 20% or more and Champagne capping output at 250 million bottles.
  • Italy and Spain entered the summer with stronger water reserves, and currently report better fruit condition than their French counterparts.

Europe is picking its earliest harvest on record, and the calendar shift matters to collectors for one reason above all: it comes attached to a materially smaller crop. Three heatwaves between May and July 2026 compressed the growing season across almost every major appellation, pulling picking forward by a week to a fortnight. This piece sets out what each region is reporting, and what a short vintage does and does not tell a buyer at this stage.

A summer of three heatwaves reset the calendar

France recorded its hottest day since records began on 24 June 2026, when the national average temperature reached 30°C, beating the 29.4°C set in July 2019 (Meteo-France, June 2026). Individual towns passed 43°C. That was the most severe of three heatwaves to cross the country between May and July, the third of which began on 6 July and pushed the southwest to 38-40°C.

The relevant consequence is supply. Compressed growing seasons concentrate sugars quickly, and they tend to arrive alongside reduced volume, which is the pattern every French region is now reporting.

Champagne: The earliest harvest on record

Champagne expects picking to begin around 15 August, with warmer sites such as Montgueux potentially starting as early as 10 August. That would eclipse the previous record of 17 August, set in 2020. The 2003 season, shortened by both April frost and the August heatwave, began on 18 August. Before the modern era, Champagne’s earliest documented harvest was 20 August 1822.

Jean-Baptiste Lecaillon of Louis Roederer attributed the Montgueux timing to site conditions, describing it as “an exceptionally sunny site”.

The acceleration follows spring frosts that cut early buds by around 40% region-wide, with losses ranging from 25% in the least affected areas to 85% in the Aisne. Summer heat then drove a rapid burst of ripening.

The Comite Champagne has responded by capping the 2026 yield at 8,800 kg/ha, equivalent to roughly 250 million bottles. Key figures:

  • 8,800 kg/ha, a 2.2% reduction on 2025’s 9,000 kg/ha limit.
  • Approximately 250 million bottles, against 266 million bottles of global Champagne shipments in 2025.
  • The tightest cap since 2020, when the Covid-disrupted vintage was held to 8,000 kg/ha, or fewer than 230 million bottles.
  • Actual crop volume is expected to fall by around 10% year on year, a separate measure from the appellation cap.

The Comite Champagne said the decision “aims to gradually rebalance stock, while preserving the economic viability of the vineyards and maintaining quality standards.” Growers now face a balancing act in the final weeks: ensuring sugar accumulation does not outpace flavour development in the berries.

Bordeaux: Comparisons to the searing 2003 vintage

Bordeaux is running hot enough that merchants are reaching for 2003 as a benchmark. Ground temperatures in some vineyards have approached 50°C, and industry estimates point to yield reductions of 20% or more.

Cremant grapes destined for sparkling wine may be picked from the beginning of August, with the main harvest expected mid-August, well ahead of the historical September norm.

Not every parcel is under equal stress. Sylvie Cazes, owner of Chateau Chauvin and president of St-Emilion Grand Cru Classe, reported that blue clay parcels retained deep water reserves from a wet winter. Producers on those soils expect smaller yields accompanied by concentrated fruit, provided the vines avoid further drought stress before picking.

Burgundy: Water is the primary concern

Burgundy’s harvest is pencilled in for around 20 August, a marked shift from the region’s traditional early-to-mid September start. Growers there frame the challenge differently to their counterparts further south.

“Our biggest concern isn’t the heat itself, but the lack of water,” said Laurent Delaunay, chairman of the Bourgogne wine board (BIVB). No official yield forecast has been released. Significant declines are widely anticipated across the Cote d’Or, which matters given the region’s existing undersupply in Premier Cru and Grand Cru white wines.

Italy: An early, broadly promising vendemmia

Italy’s 2026 vendemmia is arriving ahead of schedule in nearly every major region, and the quality picture reads more encouraging than in France. That distinction matters to buyers, because volume and quality are diverging between the two countries this year. Reports collected in early August (Italia a Tavola) show:

  • Piedmont: Fontanafredda has begun picking base wine for Alta Langa, roughly 7-10 days earlier than 2025, following abundant winter and spring rainfall.
  • Franciacorta: Montina expects to harvest between 10 and 13 August, with south-eastern sites starting 5-6 August. Hail has cut expected yields there by 10-18%.
  • Friuli: Le Vigne di Zamo is targeting the week of 10-16 August, starting with Sauvignon, and reports volumes in line with average. Le Monde and La Ponca report good balance across sugar ripeness, acidity and aromatics.
  • Tuscany: in Chianti Classico, early veraison has pulled timing forward by 7-10 days, with volumes in line with recent vintages.

Most Italian regions benefited from strong winter and spring rainfall, which built the water reserves needed to carry vines through summer heat without the acute stress seen in parts of France.

Spain: A centenarian estate’s earliest picking on record

Spain produced the summer’s most striking single data point. In Catalonia’s Penedes, sparkling wine producer Juve & Camps began harvesting on 27 July at its Espiells estate, the first time in the winery’s hundred-year-plus history that picking has started in July. Winter rainfall of 630mm had replenished soil moisture ahead of the summer heat. The estate also introduced night harvesting for the first time, keeping fruit cooler in transport to reduce oxidation and protect acidity and aromatics.

What a short vintage does and does not tell buyers

The throughline across regions is lower volume with quality still genuinely undecided. Champagne’s tightened cap, Bordeaux’s potential 20%-plus shortfall and Burgundy’s likely reduction all point towards less 2026 wine reaching the market. Whether that translates into anything at the price level is a separate question, and one this early in the season nobody can answer honestly.

The more useful signal for buyers is where the quality is likely to land. Rainfall across France in the final weeks before picking will do most of the deciding. Italy and Spain, carrying stronger winter water reserves into August, currently look better placed to convert an early harvest into a fine one.

WineCap will continue to track harvest reports as picking gets underway across Europe’s fine wine regions over the coming weeks.

FAQ: The 2026 wine harvest

When does the 2026 Champagne harvest start?

Picking is expected to begin around 15 August 2026, with warmer sites such as Montgueux potentially starting on 10 August. That would make it the earliest start in Champagne’s recorded history, beating 17 August 2020. Before the modern era, the earliest documented Champagne harvest was 20 August 1822.

Why is the 2026 European wine harvest so early?

Three heatwaves crossed France between May and July 2026, including the country’s hottest day on record on 24 June, when the national average reached 30°C. Sustained heat accelerates ripening and compresses the growing season. Across most major appellations, picking has moved forward by a week to a fortnight against recent averages.

How much smaller is the 2026 crop?

Champagne has capped output at 8,800 kg/ha, roughly 250 million bottles, with actual volume expected to fall around 10% year-on-year. Bordeaux estimates point to reductions of 20% or more. Burgundy has issued no official forecast, though declines are widely anticipated.

Will 2026 be a good vintage?

Too early to say, and any confident answer at this stage should be treated with caution. Italian producers report balanced sugar, acidity and aromatics after strong winter and spring rainfall (Italia a Tavola, August 2026), while French regions face drought stress that rainfall in the final weeks before picking may or may not relieve. Quality assessments will not be meaningful until fruit is in the cellar.

Does a smaller harvest mean prices will rise?

Not necessarily, and the two are not directly linked. Reduced supply is only one input into secondary market pricing, alongside demand, currency, existing stock levels and broader market conditions. The fine wine market fell roughly 30% from its October 2022 peak over nearly three years, so a short crop is arriving into a market still working through that adjustment.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.

Categories
Learn

Sancerre and Loire Valley wine guide: Soils, top producers and vintages to know

  • Sancerre and Loire Valley wine quality is more dependent on the producer and soil than the vintage so site knowledge is essential.
  • Three soils divide the appellation: terres blanches gives the longest-lived wines, silex – the smoky character, caillottes – the light bottles meant for drinking young.
  • Most Sancerre is made to drink young: only a narrow group of Loire names, Clos Rougeard, Dagueneau, Edmond Vatan and Huet among them, trade actively.

Sancerre is the Loire Valley’s best-known wine, and also its most misunderstood. The name covers around 3,000 hectares of genuinely different soils, producing everything from simple bistro Sauvignon Blanc to wines that hold and improve for twenty or more years. This guide sets out what separates the two: how Sancerre tastes and why, the three soil types that drive quality, the producers who define the top tier, the vintages worth prioritising, and the neighbouring appellations that share the same limestone at a lower price. 

What is the Loire Valley known for, and what are its main wine regions?

The Loire is France’s longest river and its most stylistically varied wine region. It runs roughly 1,000 kilometres from the Massif Central to the Atlantic, and the vineyards along its final 400 kilometres produce dry white, sweet white, sparkling, rose and red wine in commercial quantity. No other French region covers that range. Around 70,000 hectares are under vine, which makes the Loire France’s third-largest appellation area and its largest producer of white wine.

Four broad zones divide it, and the grape changes as the river runs west:

  • Centre-Loire, the eastern end. Sancerre, Pouilly-Fume, Menetou-Salon, Quincy and Reuilly, all built on Sauvignon Blanc with a minority of Pinot Noir. This is where the region’s best-known wines come from.
  • Touraine, the middle. Vouvray and Montlouis for Chenin Blanc, Chinon and Bourgueil for Cabernet Franc, on tuffeau limestone.
  • Anjou-Saumur, further west. Savennieres for dry Chenin, Coteaux du Layon and Quarts de Chaume for sweet Chenin, Saumur-Champigny for Cabernet Franc, and the bulk of Cremant de Loire.
  • Pays Nantais, at the Atlantic mouth. Muscadet, made from Melon de Bourgogne on gneiss and schist.

That geographic spread matters practically. A buyer who searches on the region name alone will be shown wines with almost nothing in common beyond the river, which is the first reason Loire wine confuses newcomers.

What is Sancerre, and why does the name alone tell you so little?

Sancerre is a place, not a grape. The appellation sits at the eastern end of the Loire Valley, around 200 kilometres south of Paris and closer to Burgundy’s Chablis than to the Atlantic. It covers roughly 3,000 hectares across fourteen communes. White Sancerre comes from Sauvignon Blanc. Red and rose Sancerre come from Pinot Noir.

A buyer who knows only the name knows very little, because the appellation spans three distinct soil types that produce genuinely different wines. Those three soils explain most of the quality variation inside a single AOC:

  • Terres blanches, a Kimmeridgian clay-limestone marl found on the steepest western slopes. The same formation underlies Chablis. It ripens slowly, gives the fullest and most structured wines, and produces the appellation’s longest-lived bottles.
  • Caillottes, shallow limestone gravel over hard rock. It drains fast and warms early, giving lighter, more aromatic, fruit-forward wines that drink best within two or three years of release.
  • Silex, flint, concentrated around the eastern edge near the river. It gives the smoky, struck-match character many drinkers associate with the name, along with real cellaring capacity.

Village names carry the same information in shorthand. Chavignol, Bue, Verdigny, Menetreol and Sancerre town each have their own reputations. Chavignol holds the steepest slopes and the most sought-after sites, Les Monts Damnes and Cul de Beaujeu chief among them. Entry-level Sancerre from a negociant label, blended across communes and soils, rarely repeats what those sites deliver.

How to read a Sancerre label

A Sancerre label carries more information than most buyers use. French appellation law requires only the AOC name, the producer and the vintage, so everything beyond that is a voluntary signal, and voluntary signals cost the producer something to make.

Look first for a soil or site name. Words such as Silex, Les Monts Damnes, Cul de Beaujeu, Le Chene Marchand or Les Romains indicate a single vineyard or a specific soil type, and a producer only prints them when the wine justifies the narrower claim. A cuvee name without a place attached carries less weight.

Check next for the producer category. “Mis en bouteille au domaine” means estate-bottled from the grower’s own fruit. A negociant label, which buys grapes or finished wine from others, may still be good, but it blends across sites and loses the soil signal entirely. Organic and biodynamic certification marks, AB and Demeter, appear increasingly often and correlate with the appellation’s more ambitious growers.

Sancerre rouge and rose: The Pinot Noir side of the appellation

Sancerre made its reputation on red wine, not white. Pinot Noir dominated the slopes until phylloxera destroyed the vineyards in the late nineteenth century, and growers replanted largely to Sauvignon Blanc because it recovered faster on the limestone. Red and rose now account for a minority of production, but the best examples repay attention precisely because so few buyers look for them.

Sancerre rouge is light, high-toned Pinot Noir with red-fruit aromatics and firm acidity, closer in weight to a village-level Burgundy than to anything from the Cote de Nuits. Vacheron’s reds are the appellation’s benchmark and command prices well above the white wines from many of its neighbours. Pinard and Delaporte also make serious reds.

Sancerre rose, made by direct press or short maceration, is a small category and mostly drinks young. It rarely leaves France in volume.

What does Sancerre taste like, and how does it differ from other Sauvignon Blanc?

Sancerre tastes drier, tighter and less overtly fruity than most New World Sauvignon Blanc. The reference points are citrus, white flowers, wet stone, grapefruit pith and a faint smokiness on flinty sites. Cool-climate ripening keeps acidity high, and most producers avoid malolactic fermentation (a secondary conversion that softens acidity into a rounder texture), which preserves that tension. Very few use new oak.

The comparison buyers ask about most often is Marlborough. Three differences matter:

  • Aromatics: New Zealand Sauvignon Blanc leads with passion fruit, gooseberry and cut grass, driven by warmer sites and thiol-forward winemaking. Sancerre leads with citrus and mineral character.
  • Sweetness: Many commercial Marlborough wines carry a few grams of residual sugar. Sancerre is almost always bone dry.
  • Structure: Sancerre rests on acidity and texture rather than aroma, which is why it ages and most Marlborough does not.

Chablis is the other frequent comparison, and the confusion is understandable. Both sit on Kimmeridgian limestone, and both give lean, mineral, unoaked whites with high acidity. The difference is the grape: Chablis is Chardonnay, Sancerre is Sauvignon Blanc. Chablis tends to show citrus and oyster shell, Sancerre a sharper, more herbal edge.

What food goes with Sancerre, and how should you serve it?

Sancerre has one classic pairing above all others, and it comes from inside the appellation. Crottin de Chavignol, the small aged goat cheese made in the Chavignol commune, is a protected AOP product in its own right, and the match with a flinty Sancerre from the same slopes is the reference example of local pairing logic. Goat cheese in general works for the same reason: high acidity cuts through lactic richness.

Beyond that, the wine suits oysters, shellfish, crab, ceviche and sushi, where its salinity and acid do the same job as a squeeze of lemon. It handles asparagus and artichoke, both of which defeat most wines. Herb-driven dishes, particularly anything with dill, chervil, tarragon or sorrel, echo the wine’s own aromatics. Sancerre rouge suits charcuterie, roast poultry and river fish.

Serve white Sancerre at 8 to 10 degrees Celsius. Straight from a fridge is too cold and mutes the aromatics. Older single-vineyard bottlings from terres blanches or silex benefit from a little more warmth, and some reward decanting for twenty minutes. Serve Sancerre rouge at cellar temperature, around 14 to 16 degrees.

Why is Sancerre becoming more expensive?

Sancerre’s pricing reflects a fixed supply meeting global brand recognition. The appellation cannot expand. The INAO fixed its boundaries decades ago, growers identified the best slopes long before that, and vineyard land inside them changes hands rarely and expensively. Demand, meanwhile, comes from restaurant wine lists worldwide, where Sancerre functions as a default by-the-glass white in a way few French appellations manage.

Weather has tightened supply further. Frost and mildew have cut Centre-Loire yields repeatedly over the past decade, with 2021 particularly severe. Trade reporting has put wholesale prices for the appellation on a steep upward path, citing one producer’s case price rising from around 144 to 240 US dollars over roughly a decade, and some sommeliers dropping the AOC from lists over price-to-quality concerns (PUNCH, 2023).

That criticism deserves to be taken seriously, and it points at the real problem. The price rise applies across the appellation, including to wines from flat, warm sites that never justified it. A buyer paying a premium for the name alone gets nothing for the premium.

The practical answer is to buy by producer and site. Two bottles at the same price can differ enormously in structure and ageing potential, and the label tells you which is which if you know what to look for. It also pays to look one appellation sideways, where the same limestone sells for materially less under a name the export market has not yet bid up.

The producers that define Sancerre today

Producer selection matters more in Sancerre than in almost any comparable French appellation. A short list of estates consistently makes wine that critics and the secondary market treat differently from the rest. These are selected examples rather than a complete or representative list.

  • Domaine Vacheron, based in Sancerre town and farmed biodynamically (a method using organic practices plus lunar-cycle timing and preparations, without synthetic chemicals), sets the appellation’s quality benchmark across both colours.
  • Francois Cotat and the related Cotat family estates in Chavignol make small volumes of intensely mineral, age-worthy Sancerre that sells well above standard appellation pricing.
  • Domaine Edmond Vatan, whose Clos la Neore is the single most collected white Sancerre, and Domaine Gerard Boulay, also in Chavignol, both attract buyers who cellar rather than drink on release.
  • Alphonse Mellot and Lucien Crochet are the larger, longer-established houses that built Sancerre’s export reputation and still set the standard for quality at volume.
  • Domaine Vincent Pinard, Claude Riffault, Delaporte and Henri Bourgeois combine consistency with genuine site expression, and are the most straightforward names to buy without chasing allocations.

Henri Bourgeois deserves a specific mention for scale and continuity. The family has made wine across ten generations and remains one of the appellation’s largest quality-focused producers, which gives buyers a dependable route into serious Sancerre. Smaller organically and biodynamically farmed estates, Domaine Fouassier in Bue among them, have built strong critical followings over the past decade. The quality base is widening rather than sitting still around the same half-dozen names.

How long does Sancerre age?

Serious Sancerre ages far longer than most drinkers expect. The common assumption is two to three years, and for caillottes-driven wines from warm, low-lying plots that is accurate. Wines from terres blanches or silex sites, made by the producers named above, routinely improve for eight to ten years. The best go well beyond that.

Three factors drive it. Low pH gives the acid backbone. Kimmeridgian marl slows ripening and builds structure. The widespread avoidance of malolactic fermentation preserves both. Jamie Goode’s tasting of Henri Bourgeois Les Monts Damnes across the 1996, 2006 and 2015 vintages remains the most-cited technical demonstration that top Sancerre can hold for twenty years or more.

Mature Sancerre changes character rather than simply softening. The primary citrus and herb notes recede, and honey, beeswax, dried orchard fruit and a distinct smokiness come forward. The wine surprises anyone who expects an older version of what they tasted on release.

Red Sancerre and the Loire’s Cabernet Franc appellations age on a different and often longer curve. Top Chinon, Bourgueil and Saumur-Champigny from a strong vintage can develop for fifteen years or more under proper cellaring conditions.

Sancerre vs Pouilly-Fume vs Menetou-Salon: The satellite appellations

Across the Loire river from Sancerre sits Pouilly-Fume, a Sauvignon Blanc appellation on comparable Kimmeridgian and flint soils. The wines are equally serious, and tasters typically describe them as smokier and broader than Sancerre, though producer style matters more than the appellation line. The late Didier Dagueneau built the modern reputation for concentration and ageing potential. The domaine, now run by his son Louis-Benjamin, commands prices well above typical Pouilly-Fume for its Silex and Pur Sang cuvees. Baron Patrick de Ladoucette’s Chateau du Nozet is the appellation’s other widely recognised name and a more accessible route into the same soils.

Further east, several smaller appellations sit on the same limestone band without carrying the Sancerre name premium:

  • Menetou-Salon, immediately south-west of Sancerre, produces Sauvignon Blanc from near-identical Kimmeridgian soils and sells at a consistent discount for comparable quality. A minority of the appellation is planted to Pinot Noir. 
  • Quincy, planted on sand and gravel rather than limestone, gives a rounder, softer style and remains among the least expensive routes into Centre-Loire Sauvignon Blanc.
  • Reuilly produces white, red and a distinctive Pinot Gris rose, and sits further from the main export routes. Sommeliers increasingly list both Quincy and Reuilly as genuine substitutes.

For a buyer rather than a collector, the appeal of these appellations is straightforward: exposure to the same terroir at a lower entry price, without concentrating an entire allocation in one increasingly expensive name.

One caution applies. These appellations trade thinly even by Loire standards, and a discount that exists because a name is unfashionable stays a discount for as long as the name stays unfashionable. Menetou-Salon has been described as the next Sancerre for two decades without becoming it. The case for buying these wines rests on what they deliver in the glass against what they cost, not on an expectation that the market will eventually reprice them.

Vouvray, Savennieres and Muscadet extend the Loire well beyond Sauvignon Blanc

The Loire has the widest stylistic range of any French wine region, and Sancerre represents only its eastern edge. Follow the river west and the grape changes twice.

The middle Loire belongs to Chenin Blanc, a white grape capable of dry, off-dry, sparkling and sweet botrytis-affected styles from the same vineyard depending on the vintage. Vouvray grows it on tuffeau, the soft limestone that also gives the region its cave dwellings. Savennieres, further west on schist, makes only dry Chenin, and makes it in a firm, structured style that often needs five years before it opens.

At the Loire’s Atlantic end sits Muscadet. The trade long dismissed it as a simple seafood wine made from Melon de Bourgogne, and that reputation has shifted genuinely over the past fifteen years.

  • Domaine Huet defines Vouvray. Biodynamically farmed since the 1980s, it sets the benchmark for age-worthy Chenin, with bottles from strong vintages drinking well after twenty or thirty years. Domaine du Clos Naudin and Francois Pinon sit alongside it.
  • Nicolas Joly’s Coulee de Serrant is Savennieres’ most famous holding, a monopole and one of very few single-estate appellations in France. Domaine des Baumard offers a more conventional route in.
  • Domaine de la Pepiere and Domaine Luneau-Papin lead Muscadet, where the best wines now come from named crus such as Clisson, Gorges and Le Pallet and spend extended time sur lie (on the spent yeast lees, a technique that adds texture and complexity before bottling). Recent La Place releases have brought Luneau-Papin to a wider international market.

All three categories remain priced well below Sancerre and Pouilly-Fume, despite comparable critical recognition among specialists.

Sweet and sparkling Loire wines are the region’s most overlooked categories

The Loire makes two categories that almost no buyer outside France thinks of first, and both offer better value than the dry whites that carry the region’s name.

Sweet Chenin Blanc from Anjou is the more serious of the two. Botrytis (noble rot, a fungus that dehydrates ripe grapes and concentrates sugar and acid) develops reliably in the Layon valley, and the resulting wines balance high sugar against Chenin’s naturally piercing acidity. That balance is what lets them last. Bottles from strong vintages drink well at fifty years and beyond, which few sweet wines outside Sauternes and Tokaji manage.

Sparkling wine is the volume category. Cremant de Loire and sparkling Vouvray are made by the traditional method, the same second-fermentation-in-bottle process used in Champagne, and sell for a fraction of Champagne prices.

  • Quarts de Chaume holds the Loire’s only Grand Cru status, awarded in 2011, and covers barely 30 hectares. Bonnezeaux and the broader Coteaux du Layon sit alongside it.
  • Domaine des Baumard and Chateau Pierre-Bise are the reference names for sweet Anjou, with Domaine Huet producing outstanding moelleux Vouvray in botrytis-friendly years.

The Loire’s red wines built a collector following around Cabernet Franc

The middle stretch of the valley produces some of France’s most distinctive Cabernet Franc, around Chinon, Bourgueil, Saint-Nicolas-de-Bourgueil and Saumur-Champigny. These wines sit on the same clay-limestone slopes that define quality on Bordeaux’s Right Bank, where Cabernet Franc plays a supporting role. In the Loire it stands alone, giving graphite, red fruit, crushed herb and a distinct pencil-shaving character, with firm tannin and moderate alcohol.

  • Domaine Bernard Baudry in Chinon ranks among the variety’s masters, alongside Charles Joguet, Couly-Dutheil, Olga Raffault and Philippe Alliet.
  • Domaine Catherine and Pierre Breton in Bourgueil helped drive the region’s move toward biodynamic and low-intervention winemaking. Yannick Amirault in neighbouring Saint-Nicolas-de-Bourgueil makes some of its most structured wines.
  • Clos Rougeard in Saumur-Champigny is the cult estate that put the appellation on the collector’s map, alongside Thierry Germain’s biodynamic Domaine des Roches Neuves and the more widely available Domaine Filliatreau.

Clos Rougeard illustrates what happens when a Loire red reaches genuine cult status. Production is small, demand runs ahead of supply, and secondary market prices reflect a scarcity dynamic more often associated with top Burgundy than with the Loire.

Is Sancerre a good investment? What the auction record shows

Sancerre as an appellation is not an investment category, and buyers should be clear about that before anything else. Drinkers consume the overwhelming majority within three years of release. It sells through retail rather than the secondary market, and it has no meaningful resale route.

A narrow tier does trades mostly at auction. In 2025, 58.5% of Loire wine traded by volume was under ten years old (iDealwine, reported June 2026), which indicates a young secondary market rather than an established one with vintage depth. Moreover, a rising Loire auction line reflects a small category growing from a small base.

Anyone weighing the Loire against a regulated asset should also note that wine investment is not regulated in the UK. There is no Financial Conduct Authority oversight, and no recourse to the Financial Services Compensation Scheme or the Financial Ombudsman Service. Liquidity is the practical constraint. Loire trades happen through specialist merchants, auction and direct allocation rather than a continuously quoted market, which means longer holding periods and wider spreads than Bordeaux or Champagne. That is also why barely two dozen Loire wines appear in WineCap’s Wine Track database.

The gap between reputation and market recognition is the Loire’s defining feature

The Loire’s position is unusual among French regions. Its best producers make wine that specialists rate alongside far more expensive bottles from Burgundy and the Rhone, and yet the region has no benchmark index, thin auction depth and a secondary market dominated by wines under ten years old. 

What follows is a straightforward discipline. Buy the producer and the site, not the appellation. Treat Sancerre as a drinking category with a handful of exceptions rather than an asset class with a broad base. Look one appellation beyond the famous name, where Menetou-Salon, Quincy and Saumur offer the same soils at a fraction of the price. Expect to hold anything bought with resale in mind for longer than an equivalent Bordeaux or Champagne, and to sell it through a merchant relationship rather than a screen.

FAQ: Sancerre and Loire Valley wine

What does Sancerre taste like?

Dry, high-acid and mineral, with citrus, white flowers, grapefruit pith and wet stone rather than the tropical fruit of New World Sauvignon Blanc. Wines from flinty silex soils show a smoky, struck-match character. Almost all Sancerre is bone dry and unoaked. Serve it at 8 to 10 degrees Celsius, not straight from the fridge.

How long does Sancerre age?

Sancerre from terres blanches or silex soils, made by a top producer, improves for eight to ten years and sometimes considerably longer. Wines from lighter caillottes soils are built for two to three years. Entry-level negociant Sancerre rarely rewards cellaring.

What is the difference between Sancerre and Pouilly-Fume?

Both are Sauvignon Blanc from Kimmeridgian and flint soils on opposite banks of the Loire, and the quality ceiling is comparable. Tasters typically describe Pouilly-Fume as smokier and broader, Sancerre as tighter and more citrus-driven, though producer style matters more than the appellation line. Pouilly-Fume’s most collected wines come from Domaine Didier Dagueneau.

Is bonded storage necessary for Loire wine bought for resale?

Yes, for any bottle bought with resale in mind. A bonded warehouse holds wine without UK duty and VAT having been paid, provided it stays in bond, which preserves provenance and avoids upfront tax charges. Both matter to a future buyer assessing condition and history. Tax treatment depends on individual circumstances and may change, so take independent tax advice.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.