Categories
Learn

Understanding the fine wine secondary market: Investing, liquidity and valuation

  • While the primary market is the initial sale from the estate, the secondary market is the global trading ecosystem where wine is treated as a financial asset.
  • Secondary market prices are dictated by supply/demand – as bottles are consumed, the rarity of the remaining vintage drives exponential value growth.
  • Secondary market success relies heavily on professional storage and documented history to ensure investment-grade quality.

For centuries, fine wine has been seen as a treasured collectible; over the last twenty years, it has started to be recognised as a sophisticated alternative asset class too. To understand how wine functions as an investment, one must grasp the mechanics of its lifecycle – specifically the transition from the primary market to the secondary market.

This guide provides an in-depth exploration of the fine wine ecosystem, offering clarity for collectors, investors, and enthusiasts looking to navigate the complexities of global wine trading.

What is the primary market for fine wine?

Before diving into the secondary market, we must define its origin. The primary market refers to the first time a bottle of wine is sold after production. In this stage, the transaction occurs directly between the producer (the winery or estate) and the first buyer who could be an individual or a business (i.e. wine merchant).

Key characteristics of the primary market:

  • Direct sourcing: The wine moves from the cellar of the estate to a distributor, importer, or La Place de Bordeaux courtier.
  • Fixed pricing: Prices are typically set by the estate based on production costs, brand equity, and vintage quality.
  • En Primeur (Wine Futures): A hallmark of the primary market, particularly in Bordeaux. Investors purchase wine while it is still aging in barrels, often 12-18 months before bottling. This offers the lowest possible entry price but carries the risk of the wine evolving differently than expected.
  • Allocation systems: For “cult” wines (like Domaine de la Romanée-Conti or Screaming Eagle), primary market access is restricted to exclusive mailing lists or long-standing restaurant partners.

What is the secondary market for fine wine?

The secondary market encompasses all subsequent transactions of a wine after its initial sale in the primary market. Once a bottle leaves the original distribution chain and enters the hands of a private collector, an investment firm, or a specialised retailer, any future sale happens on the secondary market.

Unlike the primary market, where supply is controlled by the winery, the secondary market is driven by supply and demand. As bottles are consumed over time, the remaining supply of a specific vintage diminishes, often driving prices upward – a concept known as “inverse supply elasticity.”

Why the secondary market matters

The secondary market is where “wine” becomes “liquid gold.” It provides:

  1. Liquidity: A platform for collectors to exit their positions and convert wine into cash.
  2. Price discovery: Real-time valuation based on what global buyers are actually willing to pay.
  3. Vintage depth: Access to aged, “library” wines that are no longer available from the producer.

The core components of the secondary market

1. Wine exchanges

The London International Vintners Exchange (Liv-ex) is the “stock exchange” for wine. It provides a standardised platform for merchants to trade, offering price transparency and indices (like the Liv-ex Bordeaux 500) that track market health.

2. Auction houses

Global powerhouses like Sotheby’s, Christie’s, and Zachys dominate the high-end secondary market. Auctions are the primary venue for rare collections and “unicorn” bottles. Online auction platforms have recently democratised this space, allowing smaller collectors to participate.

3. Specialised brokers and investment platforms

Modern fintech platforms allow investors to buy managed portfolios. These entities operate almost entirely within the secondary market, sourcing back vintages with proven provenance.

4. Peer-to-peer and retail re-sales

Specialty retailers often buy back well-cellared collections from private individuals to resell them to other collectors.

Key drivers of secondary market value

What makes a bottle appreciate in the secondary market? It is not just the name on the label.

Provenance and storage

In the secondary market, provenance is everything. A bottle of 1982 Château Lafite Rothschild is worthless if it was stored in a warm kitchen. Buyers look for “ex-cellar” history or professional storage records (bonded warehouses) to ensure the wine has been kept at a constant 12-14°C (55°F) with optimal humidity.

Critic scores

Ratings from “palate-makers” like Robert Parker’s Wine Advocate, Antonio Galloni (Vinous), or Jancis Robinson act as market catalysts. A 100-point score can cause an overnight price surge on the secondary market.

Scarcity and rarity

The secondary market thrives on scarcity. If a producer only makes 500 cases of a particular cuvée, and 200 are consumed in the first five years, the remaining 300 bottles become significantly more valuable to collectors seeking a complete vertical.

Bonded warehouses and “In-Bond” trading

In the secondary market, how you store your wine is as important as the wine itself. Professional investors almost exclusively trade wine “In-Bond” (IB).

In-Bond (IB) vs. Duty Paid (DP)

  • In-Bond (IB): The wine is stored in a government-approved bonded warehouse. It has not yet attracted VAT or Excise Duty. If you sell the wine while it is still “in bond,” you never have to pay these taxes. This increases the profit margin for investors and ensures the wine has never left a temperature-controlled environment.
  • Duty Paid (DP): Taxes have been paid, and the wine has likely been delivered to a private home. In the secondary market, Duty Paid wine often sells at a discount because its storage history is harder to verify.

Expert tip: For maximum resale value, always keep your investment-grade wine “under bond” in a recognized facility like London City Bond.

Secondary fine wine market global trade hubs 

While London remains the historical heart of the wine trade, the secondary market has shifted toward a tri-polar model:

  1. London: The center for technical trading and storage.
  2. Hong Kong: The tax-free gateway to the thirsty Asian market.
  3. Singapore: A growing hub for Southeast Asian high-net-worth individuals.

The “laggard” phenomenon

Fine wine is often described as a “laggard” asset. It does not react instantly to stock market crashes. Usually, there is a 6-to-12-month delay before wine prices reflect broader macroeconomic shifts. This makes it a powerful hedge against inflation and sudden equity volatility.

Secondary market trends: Beyond Bordeaux

Historically, the secondary market was 95% Bordeaux. Today, the landscape is much more diverse:

  • Burgundy: Now represents a massive share of market value due to extreme scarcity and global prestige.
  • Italy: The rise of “Super Tuscans” (Sassicaia, Tignanello) and Barolo has created a robust secondary niche.
  • Champagne: Recently one of the top-performing sectors, as collectors realize the aging potential of prestige cuvées.
  • The New World: Cult Californians (Harlan Estate) and Australian icons (Penfolds Grange) are now staples of global trading.

Risks in the secondary market

Investing in the secondary market is not without peril:

  • Counterfeits: High prices attract fraud. Verification of labels, corks, and glass is essential.
  • Market volatility: Like any asset, wine prices can fluctuate based on global economic conditions.
  • Illiquidity: While more liquid than it used to be, selling a wine collection still typically takes longer than selling a stock.

Primary vs. Secondary Market Comparison
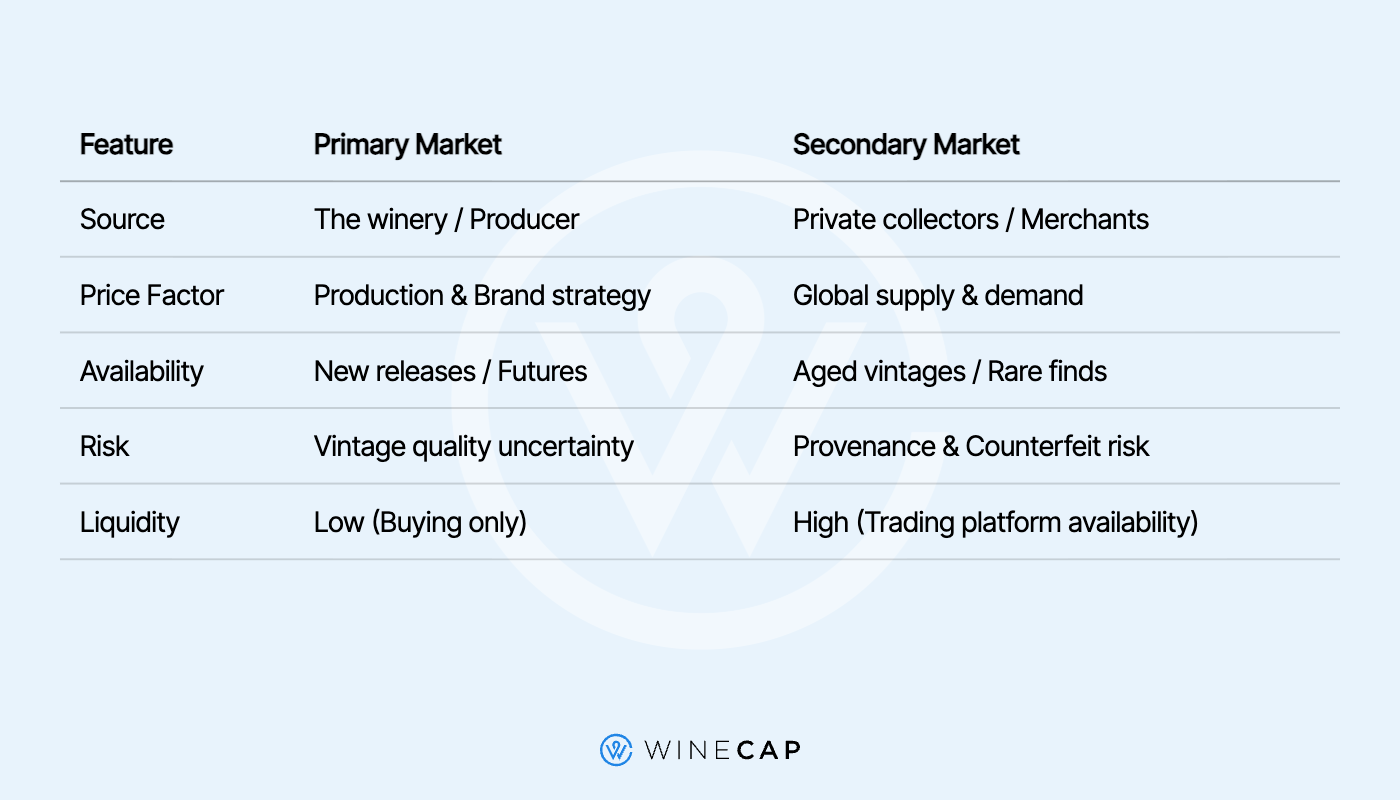
Primary vs Secondary Market Comparison

Frequently asked questions (FAQ)

Is fine wine a good investment?

Fine wine has historically shown low correlation with traditional stock markets, making it an excellent diversifier. It often delivers steady long-term capital appreciation, though it requires patience and proper storage.

What is a “bonded warehouse”?

A bonded warehouse is a tax-secured facility where wine is stored without the owner having to pay Duty or VAT. This is the preferred storage method for the secondary market, as it guarantees professional conditions and makes the wine easier to resell.

How do I check the secondary market price of my wine?

Platforms like Wine-Searcher provide market data. Specialised wine investment companies can provide valuations. Auction hammer prices are also a reliable indicator of current value.

Can individuals sell wine on the secondary market?

Yes, but it is regulated. Most individuals sell through auction houses or brokers who take a commission. Selling directly to another individual often requires specific licensing depending on your jurisdiction.

What is the best way to enter the secondary market?

Most investors start by using a managed platform or a specialised broker. This ensures you are buying wine with perfect provenance and professional storage already in place.

Why do prices fluctuate so much?

Secondary market prices react to critic scores, weather events affecting future crops, and shifts in global currency (the USD/GBP exchange rate is particularly influential).

Can I sell a single bottle?

While possible through online auctions, the secondary market is most liquid for full original wooden cases (OWC). Single bottles often face steeper commissions and lower demand.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.
Categories
Learn

Bubbles & bull markets: Investing in Vintage Champagne

  • Unlike Non-Vintage (NV) bottles, Vintage Champagne is produced only 3-4 times per decade, creating an inherent supply cap that drives long-term price appreciation.
  • Labels such as Dom Pérignon and Louis Roederer (Cristal) act as market benchmarks, offering high liquidity and global brand recognition.
  • Many investors prioritise Champagne magnums due to slower ageing process and higher premiums. 

For the uninitiated, Champagne is the liquid synonym for celebration. However, for the serious collector, it represents one of the most resilient and rewarding asset classes in the alternative investment world. Moving beyond “party bubbles” requires a shift in perspective – from the high-volume non-vintage (NV) bottles found on supermarket shelves to the rare prestige cuvées that dominate the secondary market.

Understanding the liquid gold: Is sparkling wine Champagne?

Before diving into the financials, every novice must master the terminology. A common entry-point question is: is sparkling wine Champagne? The answer is a matter of strict geography and law. Only wine produced in the Champagne region of France, under the stringent rules of the Appellation d’Origine Contrôlée (AOC), can carry the name. While Italian sparkling wine or Spanish sparkling wine like Cava offers excellent drinking, they rarely command the investment-grade premiums of a Grand Cru Champagne.

The scarcity engine: Vintage vs Non-Vintage

The primary driver of value in this market is the distinction between NV and vintage champagne.

  • Non-Vintage (NV): These are the house styles (e.g., standard Moet and Chandon ) blended from multiple years to ensure a consistent brand profile.
  • Vintage Champagne: Produced only in exceptional years, these bottles are a snapshot of a single harvest. Because they are produced in limited quantities and only 3-4 times a decade, they possess the inherent scarcity required for price appreciation.

The titans of the market: Dom Pérignon and Louis Roederer

If you are looking for the “Blue Chips” of the bubbly world, you must look at the prestige cuvées.

  • Dom Pérignon: As a powerhouse brand , the Dom Perignon price is a frequent benchmark for market health. Investors closely watch the Dom Perignon Champagne price for new releases, often holding them for a decade as the supply dwindles.
  • Louis Roederer: Specifically their “Cristal” label, Louis Roederer Champagne is a staple of elite portfolios.
  • Cult favourites: For those looking beyond the famous houses, labels like Jacques Selosse (often referred to simply as Selosse Champagne ) represent the “grower” movement, where limited production meets astronomical demand in the secondary market.

Size and longevity: Why magnums matter

In the world of investment, Champagne bottle sizes are not just about the volume of liquid. The magnum Champagne (1.5L) is the preferred format for investors. Because a magnum has a lower ratio of air-to-liquid than a standard bottle, the wine ages more slowly and gracefully. Rare large formats, such as the Jeroboam bottle or the massive Nebuchadnezzar, often fetch significantly higher premiums at auction due to their sheer rarity.

Storage and spoilage considerations

A common concern for novices is: “Does Champagne go off?” or “Can champagne go bad?” Unlike spirits, wine is a living product. How long does Champagne last? While a standard NV bottle might only stay fresh for a few years, a vintage Champagne can evolve and improve for 20 to 30 years if stored correctly.

To protect the costly Champagne in your portfolio, professional storage is non-negotiable. Light, vibration, and temperature fluctuations are the enemies of value. An investor must know how to store wine in a temperature-controlled environment to ensure that when it comes time to exit the investment, the provenance is impeccable.

The secondary market: Why the boom?

The most expensive champagne is no longer just for drinking; it is for trading. With the rise of global wealth and a fixed supply of the best vintages, the secondary market for labels like Krug, Salon, and Taittinger (check the Taittinger Champagne price for recent spikes) has seen consistent growth. Champagne often acts as a Veblen good – a luxury item where demand increases as the price rises, further fueling the bull market for the world’s finest bubbles.

Grand Cru and the terroir premium

To truly understand why some bottles command five-figure sums while others languish, the novice investor must look at the soil. Champagne is divided into a strict hierarchy of villages. At the pinnacle are the 17 Grand Cru villages, such as Ambonnay, Bouzy, and Le Mesnil-sur-Oger. These sites represent the absolute best terroir in the region, where the chalky soils and microclimates produce grapes with the highest concentration and acidity – the two vital components for long-term aging.

Below the Grand Crus sit the 44 Premier Cru villages. While still exceptional, the market price for a Grand Cru bottle often grows at a significantly higher rate than its Premier Cru counterparts. For the investor, “buying the label” is often secondary to “buying the land.” When you see a label from a producer like Jacques Selosse, you aren’t just paying for the name; you are paying for access to some of the most coveted Grand Cru plots in the Côte des Blancs. Understanding this hierarchy allows an investor to spot “undervalued” producers who may own vines in the same prestigious villages as the famous houses but have not yet reached their peak market valuation.

How long to hold your Champagne?

One of the most frequent questions from novices is how long to hold their Champagne. To answer this with an investment lens, we must discuss “lees aging.” Unlike most red wines, which age primarily in the bottle, Champagne derives its complexity from sitting on its lees (dead yeast cells) during the second fermentation.

A prestige cuvée like Dom Pérignon or Krug may spend seven to fifteen years in the cellar before it is even released to the public. This “pre-aging” by the house is why the Dom Perignon price is so high upon release; the producer has already absorbed the storage costs for a decade. However, the real “Alpha” for investors happens after release. As bottles are consumed globally, the remaining supply of a specific vintage becomes infinitesimally small. This is the “Scarcity Curve.” A vintage Champagne that was released at £150 may double in value over the next five years simply because 90% of the vintage has been drunk, leaving collectors to scramble for the remaining 10%.

Champagne as a defensive asset

In times of economic uncertainty, wine often acts as a “safe haven” asset. Unlike stocks, which can go to zero, a bottle of Louis Roederer Cristal is a tangible asset with intrinsic value. Historically, the fine wine market – and Champagne in particular – has shown a lower correlation to traditional equity markets.

When inflation rises, luxury goods often see a price surge. Champagne is a classic Veblen good in this regard; as it becomes more expensive, its desirability among the ultra-wealthy increases, creating a self-fulfilling prophecy of price growth. Furthermore, the secondary market for Champagne is more liquid than for many other rare wines. Because brand recognition is so high – everyone knows the names Moet, Bollinger, and Taittinger – it is much easier to find a buyer for a case of Champagne than for an obscure Burgundy.

Navigating the risks

No guide would be complete without a word of caution. As the most expensive Champagne prices continue to climb, the risk of counterfeits rises. Investors must ensure they receive “Original Wooden Cases” (OWC) whenever possible and verify the provenance. A bottle that has been kept at room temperature for five years is functionally worthless as an investment, even if the label is pristine. This is why professional, temperature-controlled storage is the “hidden cost” that ensures your liquid assets don’t turn into expensive vinegar.

FAQ

Is sparkling wine the same as Champagne?

No. While all Champagne is sparkling wine, not all sparkling wine is Champagne. Legally, only wine produced in the Champagne region of France under strict AOC regulations can use the name. 

Does Champagne go off or go bad?

Yes, Champagne is a living product and can spoil if not stored correctly. While a standard Non-Vintage bottle is meant for immediate consumption, a Vintage Champagne can age and improve for 20 to 30 years. However, exposure to heat, light, or vibration can turn a prestige cuvée into “expensive vinegar” and render the investment worthless.

Why is the “Dom Pérignon price” used as a market benchmark?

Dom Pérignon is considered a “Blue Chip” asset due to its massive global brand recognition and consistent quality. Because it is widely traded, its price fluctuations often signal the overall health and sentiment of the Champagne secondary market.

How long should I hold my Champagne investment?

Most experts recommend a holding period of 5 to 10 years after the initial release. This allows the “Scarcity Curve” to take effect; as the majority of the vintage is consumed globally, the remaining bottles become rarer and more valuable to collectors.

What is the best way to store investment-grade Champagne?

Professional, temperature-controlled storage is non-negotiable. To maintain its value and ensure “impeccable provenance” for future buyers, Champagne should be kept at a constant temperature (around 10-12°C) in a dark, vibration-free environment, ideally in its Original Wooden Case (OWC).

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.

Categories
Learn

Champagne vs. Prosecco vs. Cava vs. English bubbles: Which sparkling wine should you buy?

  • In the vast world of sparkling wine, Champagne remains the global benchmark for both quality and prestige.
  • The production method creates a divide: Champagne, Cava, and most English sparkling wine use the bottle-fermented “traditional method,” while Prosecco relies on the faster “tank method.”
  • From a financial perspective, Champagne is the only truly investable sparkling wine on the secondary market.

Sparkling wine, fit for any celebration, is more than just a drink for a toast. It is a vast category defined by geography, history, and chemistry. While most people recognise the pop of a cork, the liquid inside that bottle can vary wildly depending on where the grapes have been grown and how it was made.

To understand the difference between Champagne, Prosecco, Cava, and English sparkling wine we have to look at what happens inside the cellar. While they all have bubbles, the way those bubbles are created changes the flavour, the texture, the price tag and the investment reality.

The traditional method: Champagne, Cava and English fizz

Champagne, Cava, and English sparkling wine are all made using the “traditional method.” This is the most expensive and time-consuming way to make wine.

  • First, the winemaker creates a still dry wine. 
  • Then, they put it into a bottle with a little bit of sugar and yeast and seal it with a crown cap like you’d find on a bottle of beer. 
  • A second fermentation happens inside that specific bottle. Because the carbon dioxide cannot escape, it dissolves into the wine, creating the sparkle.

The final stage has the wine sitting on the lees: the dead yeast cells. Over months or years, these cells break down and give the wine flavours of toasted bread, brioche, and nuts. This is what experts call “autolytic” character. It is the reason why a glass of Champagne often smells like a bakery, while a Prosecco smells like a fruit basket.

Champagne: The undisputed king

Champagne is a specific region in northern France. If a sparkling wine is not from there, it is not Champagne. The region is famous for its white, chalky soil. This soil acts like a sponge, holding water but also reflecting sunlight back up to the vines.

The major grapes here are: 

  • Chardonnay 
  • Pinot Noir
  • Pinot Meunier

Four other varieties are also permitted but rarely used:

  • Pinot Blanc
  • Pinot Gris
  • Arbane
  • Pinot Meslier

This combination creates a wine with incredible structure and high acidity. This acidity is the backbone that allows the wine to age for decades.

Indeed, its ageability, decades long reputation and high quality make Champagne one of the most prominent investment players on the secondary market for fine wine. Still, there is a catch. 

Most non-vintage (NV) bottles, which are the standard blends houses produce every year, do not necessarily increase in value. With very few exceptions, only vintage Champagne is investable. These are wines made from grapes harvested in a single year. They are produced in smaller quantities and are built to last.

Vintage Champagnes are the primary targets for collectors and investors looking for a return.

Looking for more? Read our Champagne Regional Report.

English sparkling wine: The rising star

The story of English sparkling wine is one of geology and changing climates. The same chalk seam that runs through Champagne actually dips under the English Channel and pops up again in the South of England.

Counties like Kent, Sussex, and Hampshire have soil that is nearly identical to the best plots in France. As the climate has warmed, these regions have become perfect for growing the same three grapes used in Champagne.

  • Chardonnay
  • Pinot Noir
  • Pinot Meurnier

The style of English sparkling wine is often very lean and crisp. It has a piercing acidity that makes it incredibly refreshing. While the quality is now world class, the market is still catching up.

Search data on Wine-Searcher shows that the most popular English sparkling wines are currently sitting just inside the top 5000 most searched for wines. Interest is growing, but it is still a long way from the global dominance of the famous French houses.

Cava: Spain’s traditional bubble

Cava is Spain’s answer to Champagne. Most of it comes from the Penedès region in Catalonia. While it uses the same traditional method as Champagne, the flavours are different because the grapes are different.

The traditional Cava blend uses:

  • Macabeo
  • Xarel-lo
  • Parellada

These indigenous Spanish grapes often produce wines that are a bit more earthy or floral. They generally have lower acidity than Champagne or English sparkling wine, which makes them feel softer in the mouth.

Despite its long history, Cava struggles on the secondary market. It is often viewed as a value-for-money option rather than a luxury collectible. This is reflected in its search rankings: even the most famous Cavas usually sit outside the top 3000 most searched for wines globally. For an investor, Cava currently lacks the secondary market activity needed to be a viable asset.

The Charmat method: Prosecco

Prosecco is a completely different beast. It comes from the Veneto and Friuli regions of Italy and is made using the “tank method” (also known as the Charmat method).

Instead of the second fermentation happening in a bottle, it happens in a large stainless steel tank. This is much faster and cheaper. The goal here is not to create bread-like flavours from yeast, but to keep the wine tasting like fresh fruit.

Glera must make up 85% of the blend with the rest consisting of:

  • Verdiso 
  • Bianchetta Trevigiana 
  • Perera 
  • Glera Lunga
  • Chardonnay
  • Pinot Bianco 
  • Pinot Grigio
  • Pinot Noir

The Glera grape used in Prosecco is naturally aromatic. It smells of white peach, pear, and honeydew melon. Because it does not spend long on the yeast, the bubbles are often bigger and frothier.

Prosecco is designed to be drunk fresh. It does not improve with age. Because of this, it has almost no presence in the investment world. Like Cava, the most popular Proseccos are found outside the top 3000 most searched for wines. It is a wine for the moment, not for the cellar.

Investing in sparkling wine: a guide

The difference in investment potential between these regions is striking. While you can find a delicious bottle of sparkling wine from any of these four places, the financial world only really cares about one.

Secondary market activity is the engine that drives wine investment. This involves collectors buying and selling bottles through auction houses or private exchanges. This activity requires three main things:

  • Brand power: A name that people all over the world recognise and want.
  • Scarcity: A limited supply that cannot meet the high demand.
  • Longevity: A wine that will actually taste better (and be worth more) in time.

Champagne, specifically Vintage Champagne and “Prestige Cuvées” like Dom Pérignon or Krug, checks all three boxes. English sparkling wine is building the brand power, but it lacks the historical track record and data about its aging potential that investors crave. Cava and Prosecco, meanwhile, are produced in such high volumes that scarcity is rarely an issue, which prevents prices from climbing on the secondary market.Champagne sparkling wine table

Other sparkling wine regions

The world of bubbles does not end with these four. Other regions are also making their mark, though they face similar hurdles regarding investment.

  • Franciacorta: Italy’s premium sparkling wine made in the traditional method. It uses Chardonnay and Pinot Nero, often resulting in a richer, riper style than Champagne.
  • Crémant: These are French sparkling wines made outside of Champagne. Crémant de Bourgogne (Burgundy) and Crémant d’Alsace are excellent value alternatives that use the traditional method.
  • Tasmania: Australia’s cool-climate island is producing some of the most exciting New World bubbles, characterised by high acidity and elegance.
  • California: Areas like the Anderson Valley produce powerful sparkling wines that often show more ripe fruit and oak influence than their European cousins.

While these wines are fantastic for enthusiasts, they currently exist outside the scope of “investment grade” wine. They are brilliant additions to a dinner party, but they are not yet staples of a financial portfolio.

Sparkling wine style: texture and taste

When you are choosing a bottle, the “mousse” or the feel of the bubbles is a great way to tell them apart.

Traditional method wines (Champagne, English, Cava) usually have very fine, tiny bubbles that tingle on the tongue. This is because the carbon dioxide has had a long time to integrate with the liquid during its years in the bottle.

Tank method wines (Prosecco) have larger, more lively bubbles. They feel more “fizzy” and can sometimes be a bit more aggressive. This is why Prosecco is so popular in cocktails like the Aperol Spritz: the bubbles are strong enough to stand up to other ingredients.Champagne styles

Whether you are looking for a bottle to open tonight or one to keep for a decade, the differences between these four regions are significant.

Champagne remains the gold standard and is the only choice for those looking at sparkling wine as an asset.

English sparkling wine is the exciting newcomer, offering a taste of what Champagne used to be before the impact of climate change: high-acid, lean, and intensely fresh. Cava provides a wonderful, earthy alternative for those who love the traditional method but want a different flavour profile. Finally, Prosecco remains the ultimate choice for accessible, fruity fun.

By understanding the production methods and the market data, you can navigate the wine aisle with much more confidence. The world of sparkling wine is diverse, and while only a small slice of it is “investable,” every region offers something unique for the palate.

People Also Ask

What is the main difference between Champagne, Cava, and Prosecco?

The primary difference lies in the production method and region. Champagne (France) and Cava (Spain) use the “traditional method,” where the second fermentation happens in the bottle, creating complex brioche flavors. Prosecco (Italy) uses the “tank method,” which is faster and preserves the fresh, fruity flavors of the Glera grape.

Is English sparkling wine as good as Champagne?

Yes, many critics now consider English sparkling wine to be of world-class quality. Because the South of England shares the same chalky soil seam and a similar (though cooler) climate to Champagne, it produces wines with high acidity and lean, crisp profiles that rival top French houses.

Why is Champagne more expensive than Cava and Prosecco?

Champagne is generally more expensive due to its labor-intensive production, long aging requirements (on the “lees”), and the high cost of land in the Champagne region. Additionally, its global reputation for luxury and high demand on the secondary market keeps prices at a premium compared to high-volume regions.

Which sparkling wines are best for investment?

Currently, Vintage Champagne and Prestige Cuvées (like Dom Pérignon or Krug) are the only sparkling wines with a significant track record for investment. They offer the necessary brand power, scarcity, and longevity to increase in value on the secondary market, whereas Prosecco and Cava are designed for immediate consumption.

Can you age Cava or Prosecco like Champagne?

Generally, no. Prosecco is designed to be drunk fresh to enjoy its floral aromas; it does not improve with age. While some premium Cavas can age, most do not have the same “autolytic” structure or acidity as Vintage Champagne, which is specifically built to evolve over decades.

What does “Traditional Method” mean on a wine label?

The “traditional method” (or Méthode Traditionnelle) indicates that the wine underwent its second fermentation inside the bottle. This process creates finer bubbles and distinct flavors of toast, brioche, and nuts, which are characteristic of Champagne, Cava, and English sparkling wine.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.


Categories
Learn

Which wines are investment grade? The best wines to invest in for 2026

  • Investment-grade wine is characterised by exceptional quality, rarity, and a proven track record of price appreciation.
  • Most investment-grade wines come from regions like Bordeaux, Burgundy, Champagne, Tuscany, Barolo, Napa Valley and the Rhône.
  • Successful wine investing requires a long-term perspective, professional storage and a keen understanding of market trends. 

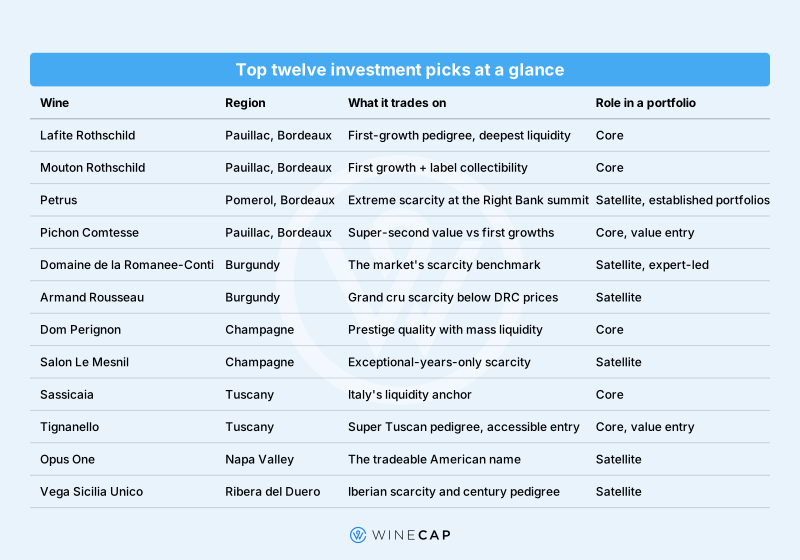
Investment-grade wine is a short list, and knowing it changes how every other wine investment decision gets made. This guide sets out the four tests a wine must pass, then profiles the twelve producers and cuvees that anchor secondary market demand in 2026, region by region, with the data points investors should check before buying any of them. It closes with the honest market context, how to buy each name, and the traps that catch buyers of famous labels. The list is selective by design: in fine wine, what you exclude protects you as much as what you include.

The four tests of an investment-grade wine

Investment quality is observable, not mystical, and every name on this list passes the same four tests. WineCap applies them through Wine Track, our database following around 3,750 investment-relevant wines daily (WineCap, August 2026), and any investor can apply them in principle to any wine they are offered.

  • Producer pedigree. Decades of consistent critical acclaim and, crucially, decades of secondary market demand. Buyers pay for predictable excellence; a single celebrated vintage does not create an investment wine.
  • Ageing capacity. The wine improves or holds for twenty years or more. Ageing is what lets scarcity build before the wine must be drunk, and it also bears on UK tax treatment, covered in our guide to whether wine is a wasting asset for capital gains tax.
  • Scarcity with consumption. Limited production that is steadily drunk, so every vintage’s supply only falls. Volume matters in both directions: too plentiful and prices stay anchored; too scarce and the wine barely trades.
  • Liquidity. Regular trading and observable prices, so the wine can be valued honestly today and sold without heroics later. A wine with no market price is a collectible, not an investment.

The tests also explain what the list excludes, which is most of the fine wine world. Excellent wines fail on liquidity because they trade too rarely to value; celebrated producers fail on scarcity because volumes anchor prices; fashionable names fail on pedigree because their demand has never been tested across a downturn. Exclusion is not a quality judgement. It is the difference between a wine worth drinking and a wine that can do a job in a portfolio.

The regions that reliably produce wines passing all four tests are few: Bordeaux, Burgundy, Champagne, Tuscany and Piedmont, the Rhone, and a handful of names from Spain and California. That geography shapes the list below.

How we built this list

Method beats assertion, so here is ours. We selected the twelve names below on the four tests above, weighting them towards trading liquidity and depth of price history in Wine Track data. We grouped them by region rather than force-ranked, because a Bordeaux first growth and a prestige Champagne play different roles in a portfolio rather than competing for one slot. The wines are selected examples of the investment grade, not a representative sample of it, not a portfolio recommendation, and not a prediction that any of them will rise. Wines that pass every test can still fall in falling markets.

Bordeaux: the liquid core

Bordeaux earns four of the twelve places because liquidity concentrates there: the region accounted for 35.5% of secondary market trade by value in 2025 (Liv-ex data via The Drinks Business, January 2026), and its classed growths carry price histories running back decades. For most portfolios, Bordeaux is where wine investment starts.

  1. Chateau Lafite Rothschild (Pauillac). The most traded of the first growths and often the most demanded fine wine in Asia, Lafite pairs first-growth pedigree with production scale (tens of thousands of cases) that keeps it tradeable in any market. Its price history is among the deepest in the asset class. 
  2. Chateau Mouton Rothschild (Pauillac). First-growth quality with a collector’s edge: artist-designed labels since 1945 that give certain vintages a second, memorabilia-driven demand stream. Our profile of Chateau Mouton Rothschild covers the estate in depth. 
  3. Petrus (Pomerol). The Right Bank’s summit: a tiny Merlot estate whose roughly 2,500-case production meets global demand, producing some of the highest bottle prices in Bordeaux. Liquidity is thinner than the first growths, provenance scrutiny higher, and the entry price steep, which is why Petrus suits established portfolios rather than first purchases. Our guide to what makes Petrus the world’s most valuable Bordeaux wine explains the mechanics. 
  4. Chateau Pichon Longueville Comtesse de Lalande (Pauillac). The value entry: a “super second” trading well below first-growth prices on quality critics repeatedly score alongside them. Super seconds are a common first Bordeaux purchase precisely because the pedigree-to-price ratio is the most favourable on the Left Bank. 

Burgundy: scarcity’s home ground

Burgundy inverts Bordeaux’s proposition: production measured in hundreds of cases rather than tens of thousands, prices that reach the market’s summit, and liquidity that demands more patience at both entry and exit. The region rewards expertise more than any other, and it concentrates authenticity risk for the same reason, since tiny supply and enormous prices are the counterfeiter’s favourite combination. Both names below demand flawless provenance as a condition of purchase, not a preference.

  1. Domaine de la Romanee-Conti (Vosne-Romanee). The reference point for scarcity-driven value: grand cru monopoles measured in hundreds of cases, global demand measured in multiples of supply. DRC sits at the top of the market by price and reputation, with liquidity and authenticity risk to match; buyers should insist on flawless provenance. Our ten facts about Domaine de la Romanee-Conti profiles the estate. 
  2. Domaine Armand Rousseau (Gevrey-Chambertin). Burgundy’s second tier of investment demand belongs to a handful of domaines whose grand crus trade on DRC-like scarcity at lower, though still substantial, prices. Rousseau’s Chambertin is the exemplar: tiny production, decades of acclaim, and a deep collector base. Burgundy rewards expertise, and our guide to Burgundy grand cru for investors is the sensible companion read.

Champagne: consumption does the work

Champagne has the clearest investment logic in fine wine: prestige cuvees are drunk in celebration worldwide, so supply attrition never pauses, while house brands keep demand broad across markets and generations. Krug, Cristal and Taittinger’s Comtes de Champagne all belong in the category’s first rank; the two names below bracket its range, from maximum liquidity to maximum scarcity.

  1. Dom Perignon (Moet & Chandon). The most liquid name in investment Champagne: prestige-cuvee quality at production volumes large enough to trade constantly, with a global brand that keeps consumption, and therefore supply attrition, running in every market. 
  2. Salon Le Mesnil. The scarcity pole of Champagne: a single-vineyard, single-vintage blanc de blancs released only in exceptional years, roughly a decade after harvest. Tiny volumes and long ageing make Salon behave more like grand cru Burgundy than like its Champagne peers. As a selected example of the category’s range rather than a promise, Dom Ruinart Blanc de Blancs shows a rise of 135% over ten years on our price data (Wine Track, August 2026), a period in which the broad market first climbed steeply and then corrected. Our guide to investing in Champagne covers the category’s houses in full.

Italy: the momentum region

  1. Sassicaia (Tenuta San Guido, Bolgheri). The Super Tuscan that created the category, with its own DOC, six decades of vintages and the deepest liquidity in Italian fine wine. Italy’s share of secondary market trade grew through the recent downturn as buyers sought value outside France, and Sassicaia is that trade’s anchor. Our profile of Sassicaia tells the story. 
  2. Tignanello (Antinori, Tuscany). The accessible Super Tuscan: larger production and lower entry prices than Sassicaia with the same six-decade pedigree, making it a common first Italian holding. Piedmont’s Barolo elite (Giacomo Conterno above all) belongs in the same conversation for investors going deeper into Italy; our guide to Barolo covers that ground. 

Beyond France and Italy

  1. Opus One (Napa Valley). The most tradeable American fine wine: a Mondavi-Rothschild joint venture with global distribution, meaningful production volume and a genuine secondary market on both sides of the Atlantic. US demand matters to this name more than most, worth knowing given that American buying fell sharply in 2025 under tariff pressure and recovered to 26.9% of global purchase value by the second quarter of 2026 (Liv-ex data via The Drinks Business, January 2026; WineNews, July 2026). Our guide to Opus One profiles the estate. 
  2. Vega Sicilia Unico (Ribera del Duero). Spain’s flagship and its one reliably investment-grade name: a decade of ageing before release, a century of reputation, and scarcity built into the production model. Unico gives a portfolio Iberian diversification without leaving the investment grade; our guide to investing in Spanish wine sets the wider context.

Picking vintages within the twelve

A name from the list is half a decision; the vintage is the other half, and it moves the price more than newcomers expect. Great vintages (2005, 2009, 2010 and 2016 are the commonly cited Bordeaux examples) carry premiums from release and typically hold demand longest, because their wines age furthest and their reputations compound. The same chateau’s wine from a modest year can trade at a fraction of the price, which cuts both ways: off-vintages of great estates offer lower entry points, but they leave the market’s radar sooner and their exit demand is thinner.

Drinking windows supply the timing logic. A wine approaching maturity sits where consumption accelerates fastest, tightening supply exactly as demand from drinkers peaks; a wine decades from readiness asks for patience the buyer must actually have. Matching vintage maturity to intended holding period is therefore a portfolio decision, not a trivia point. Our guides to the best Bordeaux vintages and the best Burgundy vintages for wine investment map the years that matter for the list’s two biggest regions.

The edge of the list: names knocking on the door

Investment grade is a perimeter that moves slowly, and watching its edge is part of following this market. Piedmont’s elite, led by Giacomo Conterno’s Monfortino, already trades on Burgundian scarcity logic and has been gaining collector attention as Italian trade share grows. Champagne’s top grower producers (Jacques Selosse above all) have built genuine secondary markets from tiny productions, though liquidity remains a fraction of the grandes marques. White Burgundy’s leading domaines pass the pedigree and scarcity tests while asking harder questions on ageing consistency.

The discipline at the edge is the same as inside it: trading data rather than marketing demonstrates demand. A rising name earns its place on this list after years of observable secondary market activity, and an investor who waits for that evidence gives up a little upside for a lot of certainty. New entries to the investment grade arrive over vintages, not headlines.

The 2026 context every buyer should hold in mind

Great names did not escape the recent correction, and pretending otherwise would misdescribe the asset. From its October 2022 peak the broad fine wine market fell roughly 30% over three years, and the Liv-ex 100 declined 2.5% in 2025 . The first half of 2026 brought signs of stabilisation: broadly flat indices in the first quarter and strengthening US participation into the second. Our market coverage of fine wine’s firmer start to 2026 follows the turn as it develops.

For buyers of the wines above, the practical readings are two. Repriced blue chips can be examined against long price histories rather than against peak-era hype, and every purchase should still be benchmarked to current market levels through data such as Wine Track before money moves. Past performance, on this list as everywhere, is not a guide to future returns.

How to buy the wines on this list

Access runs through the routes our guide to how wine investment works explains in full: a managed platform sourcing at documented market prices, en primeur for new Bordeaux releases, auction for mature rarities, or self-directed trade accounts. Two rules travel across all of them. Buy sealed original cases with unbroken bonded provenance, since these names attract counterfeiters in proportion to their fame. And compare every offer against the wine’s observable market level; famous labels are where overpaying hides most easily, because the name reassures while the price misleads.

Storage completes the purchase. Every name on this list belongs in bonded storage in the buyer’s name from day one, both for condition and because an unbroken bonded record is what lets these wines sell at full market level years later. Provenance premiums are largest precisely at the top of the market, where buyers pay for certainty as much as for wine.

Portfolio construction across the list matters more than any single pick. A first portfolio typically anchors on the liquid core names (Bordeaux, Dom Perignon, Sassicaia) before adding the scarcity satellites, a structure our guide to starting a wine investment portfolio in the UK works through with allocations. Budget shapes the sequence too: a £5,000 starting portfolio (WineCap’s minimum, August 2026) reaches the value entries and core names comfortably, while Petrus and DRC typically enter portfolios at larger scale, if at all.

What to avoid: the traps around famous names

The investment grade has a perimeter, and money is lost just outside it. Second wines of great estates, celebrity-branded cuvees, and “limited editions” of mass producers borrow investment language without passing the four tests: their scarcity is manufactured, their secondary demand thin or absent. Old wine is not automatically valuable wine; a fifty-year-old bottle from an unremarkable producer is a curiosity. And wines pitched by cold call at “guaranteed” returns fail the only test that matters before any of the four: legitimate sellers do not need to promise outcomes. Wine investment is unregulated in the UK, with no FCA, FSCS or FOS protection, so the vetting checklist in our guide to how wine investment works stands in for the safety net.

A short list is the strategy, not a limitation

Twelve names from five regions may look narrow against a world of wine, and that narrowness is the entire discipline. The investment grade exists because demand concentrates on producers whose excellence is predictable across decades, and the concentration is what creates the liquidity, the price histories and the exit routes that separate an investment from a cellar of hopes. Investors who stay inside the perimeter, buy at verified prices and hold for years give themselves the version of this market that actually works; the wines above are where that version lives in 2026.

FAQ: The best wines to invest in

What is the best wine to invest in for 2026?

No single wine is “best” for every investor, but secondary market demand in 2026 concentrates on Bordeaux’s first growths (Lafite and Mouton Rothschild), Petrus, Domaine de la Romanee-Conti, prestige Champagne such as Dom Perignon, and the leading Super Tuscans, Sassicaia above all. The right choice depends on budget, existing holdings and horizon, and prices can fall as well as rise.

What makes a wine investment grade?

Four traits together: a producer with decades of critical and market pedigree, ageing capacity of twenty years or more, production scarce enough that drinking steadily reduces supply, and enough trading activity for prices to be observable. Very few wines pass all four; most of the world’s wine never develops secondary market value.

Are famous wine brands always good investments?

No. Fame is necessary but not sufficient: second wines, celebrity labels and manufactured “limited editions” trade on borrowed prestige without real secondary demand. Even genuine investment-grade names fell during the 2022 to 2025 correction, when the broad market dropped roughly 30% from its peak (Liv-ex, 2025). Past performance is not a guide to future returns.

How much do investment-grade wines cost?

Entry points vary widely by name: cases of super seconds like Pichon Comtesse or Super Tuscans like Tignanello cost materially less than first growths, while Petrus and DRC sit at the market’s summit. A diversified WineCap portfolio starts from a £5,000 minimum investment (WineCap, August 2026).

Is Burgundy or Bordeaux better for wine investment?

They do different jobs. Bordeaux offers the deepest liquidity and price histories, making it the usual core holding; Burgundy offers the strongest scarcity dynamics with thinner liquidity and higher entry prices, suiting experienced portfolios. Many investors hold both, weighted towards Bordeaux early on.

Where can I check a wine’s investment performance before buying?

WineCap’s Wine Track follows around 3,750 investment-grade wines daily with price and performance histories. Checking any offer against these observable market levels before purchase is the single most protective habit in wine investment.


Categories
Learn

Barolo wine: a guide to Italy’s most collectible red

  • Barolo, the benchmark for Nebbiolo, sits at the top of Italy’s fine wine hierarchy.
  • Its rarity, long ageing potential and diversity of styles make it highly collectable.
  • In the secondary market, top Barolo producers often outperform all other Italian regions.

Barolo sits at the very top of Italy’s fine wine hierarchy. It’s the benchmark for Nebbiolo, the calling card of Piedmont, and one of the most consistently traded Italian categories on the secondary market. However, it’s also a wine that can feel intimidating: communes, crus, “traditional vs modern”, long ageing, and producer styles vary dramatically even within a few kilometres.

This Barolo wine guide is designed to demystify the region – whether you’re buying your first serious bottle, building a cellar, or thinking about it as part of a diversified fine wine portfolio.

What is Barolo?

Barolo is a DOCG wine from the Langhe hills in Piedmont, made from 100% Nebbiolo. It is known for high acidity and tannin, aromatic complexity (rose, tar, dried cherry, spice), and an ability to improve for decades in bottle – traits that underpin its collector appeal.

Why Barolo is built for cellaring

One reason Barolo has such strong longevity and investment relevance is the mandatory ageing requirement: Barolo must be aged at least 38 months before release, and Barolo Riserva must be aged longer (commonly cited as 62 months), depending on the rules in force and producer practice. This extended maturation helps set expectations in the market: Barolo is supposed to age, and top examples routinely do.

Traditional Barolo

Barolo’s modern identity was forged in a late-20th-century stylistic divide that continues to shape both perception and pricing today.

For much of the 20th century, Barolo was defined by a firmly traditional approach. Long macerations – sometimes stretching to 30 days or more – extracted formidable tannin and structure from Nebbiolo’s thick skins. Ageing took place in large, neutral Slavonian oak casks (botti), which had often already been used multiple times. This practice remains in place today. These vessels allow slow, gradual oxygen exchange without imparting overt oak flavour. The result? Wines that emphasise structure, savoury complexity, and terroir transparency over fruit sweetness or texture. In youth, they can seem austere, even severe. With time, however, they develop the haunting aromatics and layered nuance that define classic Barolo.

Modern Barolo

In the 1980s and 1990s, a new generation of producers – often referred to as the “modernists” – sought a different expression. Shorter macerations reduced harsh tannin extraction, while ageing in smaller French oak barriques, frequently new or partially new, introduced a different dynamic. Smaller barrels increase the ratio of wood surface area to wine, accelerating oxygen exchange and allowing oak compounds like vanillin, toast, spice and subtle sweetness to influence the wine’s profile. The tannins often feel rounder and more polished, the fruit darker and more immediate, and the wines generally more accessible in their youth.

Oak, therefore, became more than just a maturation vessel but a stylistic signature. Large botti tend to preserve Nebbiolo’s natural austerity and aromatic precision, while small barriques can frame the grape in a richer, more textural, internationally recognisable style.  Over time, the binary has softened. Many leading estates now blend elements of both philosophies, moderating extraction, using a mix of large casks and smaller barrels, and aiming for balance rather than dogma. 

Why Barolo style matters

From an investment perspective, style matters because it shapes buyer pools. Some collectors actively seek the slow-burn, classically structured wines that demand patience and reward decades in the cellar. Others prefer a more polished, earlier-drinking profile that broadens appeal across international markets. Crucially, the most successful producers, whether modernists or traditionalists, maintain liquidity because demand rests on reputation, consistency, and ageing track record.

Barolo’s map: communes and how they taste

Barolo is one of the world’s clearest examples of place-defining style. Within the small Barolo DOCG, varied vineyard exposure, altitude, soil type, and producer philosophy can dramatically shift the personality of a wine.

That said, collectors often use the main communes as a shorthand for understanding Barolo style, ageing potential, and overall profile, especially when comparing bottles on the secondary market.

Key Barolo communes 

Below is our Barolo wine guide to the region’s most important communes.

  • La Morra
    • Often the most perfumed and approachable in youth
    • Notes of rose, red cherry, violet, sweet spice
    • Generally softer tannins and earlier-drinking charm
  • Barolo (commune)
    • Can combine perfume with more depth and structure than La Morra
    • Often shows classic tar-and-roses character with firm backbone
    • A strong balance of finesse and ageing ability
  • Monforte d’Alba
    • Typically darker, more muscular, and structured
    • Powerful tannins, earthy tones, black cherry, liquorice
    • Built for long ageing and collector demand
  • Serralunga d’Alba
    • Often the most intense and long-haul expression of Barolo
    • Firm tannic spine, mineral grip, darker fruit, iron-like depth
    • Highly prized for investment-grade longevity
  • Castiglione Falletto
    • Frequently, the “sweet spot” commune: perfume and structure
    • Aromatic lift with serious mid-palate power
    • Often considered one of the most complete all-round expressions
  • Verduno
    • Lighter-framed but highly distinctive: spice, florals, lift
    • Often shows herbal notes, pepper, red fruits, and energy
    • Increasingly sought-after by “insider” collectors

Barolo’s MGA labelling

Barolo’s “MGA” system (translating as “additional geographic mentions”) functions like a cru framework: it gives clearer origin signals and helps buyers compare vineyard-designated bottlings across producers. In practice, that clarity supports collectability because it improves recognition and repeat buying.

What makes Barolo investment-grade?

Not all Barolo is investment-worthy. The bottles that behave best in the secondary market usually share five key traits:

1. Producer reputation and long-term consistency

Investment-grade Barolo almost always begins with the producer.

  • Decades (often generations) of proven quality
  • Strong performance across multiple vintages – not just in “great” years
  • Established global distribution and recognition

Collectors and merchants prioritise names with a track record (to check the performance of your favourite Barolos, visit Wine Track). Consistency reduces risk, supports liquidity, and anchors pricing even during broader market slowdowns.

2. Recognisable vineyards or flagship labels

Single-vineyard (cru) Barolos with strong brand equity tend to trade more reliably.

  • Clearly labelled, prestigious crus
  • Estate flagship bottlings with cult followings
  • Wines that appear regularly in auction results and critic reports

In fine wine investment, recognisability matters. Buyers gravitate toward labels they understand and can benchmark easily.

3. Scarcity and allocation pressure

Supply dynamics play a major role in price behaviour.

  • Limited production volumes
  • Tight allocations to merchants
  • Strong on-trade (restaurant) and private client demand

Scarcity supports pricing power, particularly when global demand widens. Wines that are hard to source tend to maintain tension in the market.

4. Sustained critical attention

While high scores can spark short-term spikes, what truly drives investment performance is consistent quality and repeated coverage.

  • Consistent strong reviews across vintages
  • Ongoing commentary from major critics
  • Inclusion in vintage retrospectives and “top wine” lists

Repeat visibility reinforces confidence. It builds a narrative around the wine, which sustains demand. 

5. Provenance and professional storage

Even the greatest Barolo will struggle in the market without impeccable provenance supported by:

  • Professional bonded storage
  • Clear transfer history
  • Untampered original packaging

In today’s market, institutional and high-net-worth buyers prioritise condition and traceability.

Top Barolo producers for collectors

Below is our quick guide to the best Barolo producers from an investment perspectives – estates that see steady collectors’ demand.

Giacomo Conterno (especially Monfortino)

If you want a single label that globally signals serious Barolo collecting, Conterno is it. Monfortino Riserva is widely treated as a blue-chip Italian collectible, combining rarity, historic reputation, and famously long ageing curves — all traits that tend to underpin long-term demand.

Bartolo Mascarello

Mascarello is emblematic of “traditional Barolo” and has become a cultural symbol as much as a producer, helped by the estate’s uncompromising identity and loyal collector base. Their history (estate roots and a long-standing family narrative) is part of the brand power that keeps demand resilient. The market watches Mascarello releases closely because scarcity and reputation combine into a powerful collector signal.

Giuseppe Rinaldi

Long a cult favourite, Rinaldi is defined by tiny production and obsessive collector loyalty. These are the types of wines that can remain firm even during softer market cycles, simply because bottles become difficult to replace once they disappear into private cellars.

Bruno Giacosa

Bruno Giacosa remains one of Piedmont’s most respected names, often associated with finesse, precision, and classical structure. The estate’s top Barolos carry enduring prestige, particularly among collectors who prioritise elegance over sheer power.

Cappellano

A true “insider” estate, Cappellano is spoken about with reverence among Barolo specialists. Scarcity, a fiercely consistent house style, and limited international supply combine to create long-term collectability.

Luciano Sandrone

Sandrone is a modern-era benchmark and one of the most globally understood names in Barolo. The wines often strike a balance between power, polish, and early approachability, which tends to broaden the buyer pool – helpful for liquidity.

Elio Altare

Altare is closely tied to the modernist chapter of Barolo history, and that narrative itself has become part of the collectable appeal. For many buyers, Altare represents a style shift that shaped modern Barolo’s global reputation.

Roberto Voerzio

Voerzio is associated with intensity, concentration, and limited supply, a combination that can perform well when allocations tighten and demand remains international. The estate’s wines are often bought with long-term collecting in mind.

Vietti

Vietti is extremely collector-friendly: widely recognised, strong branding, and often released across multiple crus, making it easier to build a structured cellar (verticals, commune comparisons, vineyard sets). It also benefits from consistent visibility in the global fine wine conversation.

Best Barolo vintages

Vintage matters in Barolo, but its importance varies depending on your goal.

If you’re buying to drink, you can often win by targeting “less hyped” vintages from elite producers. These years can offer outstanding quality at better pricing, often with earlier accessibility.

If you’re buying for investment, vintage confidence becomes far more important. The best-performing Barolo vintages are the ones the global market broadly agrees on – because shared confidence drives demand, pricing power, and liquidity.

In Barolo, the ideal vintage delivers tannin ripeness, aromatic purity, and acidity in balance. When that happens, the wines don’t just age well – they become long-term reference points for collectors.

Top Barolo vintages 

These are the vintages most widely regarded as benchmark years, with strong consistency across producers and excellent long-term ageing potential:

  • 1988 – classic, structured, long-lived
  • 1989 – richer, generous, highly collectable
  • 1990 – iconic, powerful, long-haul Barolo
  • 1996 – firm, structured, built for decades
  • 1999 – excellent balance, depth, ageing curve
  • 2001 – one of the great modern “complete” vintages
  • 2010 – highly celebrated, textbook balance and longevity
  • 2016 – outstanding across the region; one of the most trusted recent vintages
  • 2019 – emerging as a modern classic with freshness and depth

These years tend to show the qualities collectors love most: structure without harshness, aromatic complexity, and a long runway of development.

How Barolo performs in a portfolio

Barolo demand is producer and site-led

Collectors often buy Barolo because they want a particular estate and, increasingly, a particular cru or commune. This creates a “specialist collector base” dynamic: deep knowledge, high conviction, and strong attention to provenance and bottle condition.

Structure supports long ageing curves

Nebbiolo’s tannin and acidity framework means top wines often need time before they reach peak drinking and peak market maturity. That longer runway can be a feature (rarity over time), but it also means Barolo is rarely a quick-turn category.

Liquidity concentrates at the top

The blue-chip names can be extremely tradeable, but the mid-tier is more style and market-dependent than Tuscany’s global flagships. 

Barolo vs Super Tuscans

In the market, Barolo often behaves differently from the Super Tuscans – the most liquid group of Italian wines:

  • Barolo: site/producers drive demand; tannin structure supports long ageing; strong specialist collector base.
  • Super Tuscans: brand power is more “global luxury”; often broader mainstream liquidity.

Most serious Italian-focused portfolios hold both: Barolo for terroir-driven collectability, Tuscany for brand-driven liquidity.

FAQs

Is Barolo a good investment wine?

Top Barolo can be investment-grade when it combines producer reputation, scarcity, consistent demand, and strong provenance. The category is a core pillar of Italian fine wine collecting, particularly among Piedmont specialists.

What is the best Barolo producer?

There isn’t one “best” producer. That said, blue-chip names that commonly perform well in the secondary market and see sustained demand include Giacomo Conterno, Bartolo Mascarello, Giuseppe Rinaldi, and Bruno Giacosa. Modern benchmarks like Sandrone, Altare, and Voerzio are also top performers.

How long should you age Barolo?

Many quality Barolos benefit from extended ageing; the category is defined by long-term evolution, reinforced by required minimum ageing before release. 

What is the difference between Barolo and Barbaresco?

Both are 100% Nebbiolo from Piedmont, but Barolo is often called the “King” and Barbaresco the “Queen.” Barolo soils (especially in Serralunga) tend to produce more powerful, tannic wines that require longer ageing. Barbaresco generally has slightly sandier soils and a warmer maritime influence, leading to softer tannins and earlier accessibility.

What does “MGA” stand for on a Barolo label?

MGA stands for Menzioni Geografiche Aggiuntive. It is the official classification system that defines specific vineyard boundaries (similar to the “Cru” system in Burgundy). Seeing an MGA name like Cannubi or Vigna Rionda on a label typically indicates a higher level of prestige and terroir specificity than a standard “normale” blend.

Why is Barolo so expensive compared to other Italian wines?

“The Three S’s” drive value: Scarcity (the DOCG is small), Structure (the high tannin/acid required for long-term cellaring), and Slow release (producers must hold stock for years before selling). This makes the cost of production and the “hold value” much higher than high-volume regions.

Do I need to decant Barolo?

Yes, almost always. Younger Barolos (under 15 years) need oxygen to soften their aggressive tannins and “open up” their floral aromatics. Older, sediment-heavy bottles should be decanted carefully just before serving to separate the wine from the solids, though fragile, very old bottles should be monitored closely as they can fade quickly once exposed to air.

Categories
Learn

The best Italian wines: A complete guide

  • This guide breaks down the best Italian wines by region, grape variety, and style, making it easy to understand what matters most.
  • We also highlight the Italian wines with proven investment potential, including the producers most traded on the secondary market.
  • From Barolo and Barbaresco to Brunello and Super Tuscans, Italy produces some of the world’s most collectable wines.

Italian wine is one of the most complex, expressive, and rewarding categories in the world. With hundreds of native grape varieties, deeply-rooted regional identities, and a growing presence in the global fine wine market, Italy offers an unmatched combination of history, diversity, and long-term potential.

For many people, Italian wine starts with familiar names such as Chianti or Prosecco but these only scratch the surface. Beneath them lies a vast and nuanced landscape shaped by geography, tradition, and evolving winemaking philosophies.

Over the past decade, Italian wine has taken on a new role: not just as something to enjoy at the table, but as a serious category within fine wine collecting and investment. Once dominated by Bordeaux and Burgundy, the secondary market has increasingly embraced Italy’s top wines, particularly from Piedmont and Tuscany. Italy’s market share by value has risen from 5.7% to 15.3% since 2016, making it an important addition to investment portfolios, providing stability and potential for high returns.

This guide explores the best Italian wines, explains the regions and grape varieties behind them, and outlines why certain Italian wines have become sought after by collectors worldwide.

Why Italy is one of the most important wine countries

Italy is the world’s largest wine producer by volume and one of the oldest wine cultures in existence. Wine has been produced on the Italian peninsula for more than two millennia, and today it remains deeply intertwined with everyday life, food, and regional identity.

What sets Italy apart from other wine-producing countries is its extraordinary diversity. Officially, Italy recognises more than 500 native grape varieties, far more than France or Spain. These grapes are cultivated across dramatically varied climates – from Alpine vineyards in the north to Mediterranean coastlines in the south.

From a global perspective, Italy combines:

  • Strong domestic consumption
  • Consistent export demand
  • Increasing collector and investor interest

This balance has helped Italian wine remain resilient through changing market conditions and has supported long-term appreciation for the country’s top wines.

Understanding Italian wine classifications

Italian wines are regulated by a classification system designed to protect origin and quality. While not a guarantee of excellence, classification provides important context when navigating Italian wine.

  • DOCG (Denominazione di Origine Controllata e Garantita)
    The highest level, covering iconic wines such as Barolo, Barbaresco, and Brunello di Montalcino.
  • DOC (Denominazione di Origine Controllata)
    A broad category covering many high-quality wines with defined production rules.
  • IGT (Indicazione Geografica Tipica)
    Introduced to allow flexibility and innovation, famously used by Super Tuscan producers.

From a collecting perspective, classification matters because it signals consistency, recognisability, and historical reputation. However, some of Italy’s most valuable wines sit outside the DOCG system, proving that producer reputation often outweighs classification alone.

Italian wine regions explained

Italy’s geography plays a defining role in its wines. Stretching from the Alps in the north to the Mediterranean islands in the south, the country encompasses a wide range of climates, soils, and elevations. Understanding Italian wine regions is the foundation for understanding the best Italian wines.

Piedmont: Home of Barolo and Barbaresco

Piedmont is widely regarded as Italy’s most important fine wine region. Located in the north-west of the country, it is defined by rolling hills, foggy autumns, and a continental climate ideal for slow ripening. It is widely regarded as the most important region for investment-grade Italian red wines.

Its flagship grape, Nebbiolo, produces two of Italy’s most famous wines:

  • Barolo
  • Barbaresco

These wines are known for their structure, complexity, and ability to age for decades. Barolo, often referred to as “the King of Wines,” combines power with finesse, while Barbaresco tends to offer slightly more elegance and earlier approachability.

From an investment perspective, Piedmont wines benefit from:

  • Strict production rules
  • Limited vineyard land
  • Strong international demand

As a result, Barolo and Barbaresco consistently feature among the best Italian wines to collect.

Tuscany: Sangiovese, Brunello and Super Tuscans

Tuscany is perhaps Italy’s most recognisable wine region, producing some of the most famous Italian wines in the world. At the heart of  Tuscan wine is Sangiovese, a grape capable of producing everything from fresh, everyday wines to long-lived icons.

Key Tuscan wines include:

  • Chianti Classico
  • Brunello di Montalcino
  • Vino Nobile di Montepulciano

Brunello di Montalcino, made exclusively from Sangiovese Grosso, is among Italy’s most age-worthy wines, often developing over 20-30 years.

Tuscany is also home to the Super Tuscans – wines like Sassicaia, Tignanello, and Ornellaia. These wines broke traditional rules by incorporating international grapes such as Cabernet Sauvignon and Merlot, and today they rank among the best Italian wines for collectors and investors.

Veneto: Amarone and Valpolicella

Veneto, in north-eastern Italy, produces a broad range of styles, but its most prestigious wine is Amarone della Valpolicella.

Amarone is made using partially dried grapes, resulting in a powerful, concentrated red wine with high ageing potential. While stylistically different from Barolo or Brunello, top Amarone wines can develop beautifully over time and occupy a niche role in Italian wine collections.

Veneto also produces:

  • Valpolicella Classico
  • Valpolicella Ripasso
  • Soave (white)

While not all Veneto wines are investment-grade, Amarone remains one of the best Italian red wines for collectors seeking diversity.

Southern Italy and the islands

Southern regions such as Sicily, Puglia, and Campania have undergone a quality renaissance in recent decades.

Key grapes include:

  • Nero d’Avola (Sicily)
  • Primitivo (Puglia)
  • Aglianico (Campania)

These regions produce expressive and often excellent-value wines, but most are intended for enjoyment rather than long-term investment. That said, select producers – particularly in Sicily – are increasingly attracting collector interest.

The best Italian wines by style

Understanding Italian wine styles helps narrow down what makes certain bottles stand out.

Best Italian red wines

Italy is best known for its red wines, particularly those capable of ageing.

Standout styles include:

  • Nebbiolo-based wines (Barolo, Barbaresco)
  • Sangiovese-based wines (Brunello, Chianti Classico)
  • Amarone della Valpolicella
  • Super Tuscan blends

These wines combine structure, acidity, and tannin, all key elements for longevity.

Best Italian white wines

Italian white wines are often overshadowed by reds, but they play an important role in Italy’s wine identity.

Notable white wines include:

  • Gavi (Cortese)
  • Soave (Garganega)
  • Verdicchio
  • Vermentino

While most Italian white wines are produced for early consumption, a small number – particularly from top producers – can age gracefully. From an investment standpoint, however, Italian whites remain a niche category.

Best Italian wines for ageing

Age-worthy Italian wines typically share:

  • High acidity
  • Firm tannins
  • Structured phenolics

Examples include:

  • Barolo
  • Barbaresco
  • Brunello di Montalcino
  • Super Tuscans

These wines often improve for decades, making them attractive to collectors focused on long-term horizons.

What makes Italian wine investment-grade?

Not all Italian wines are suitable for investment. The best Italian wines for collectors tend to meet several criteria:

  1. Producer reputation
    Iconic estates with long track records perform best.
  2. Regional prestige
    Piedmont and Tuscany dominate secondary market activity.
  3. Scarcity
    Limited production drives long-term demand.
  4. Critical recognition
    Consistent acclaim helps sustain liquidity.
  5. Provenance and storage
    Condition matters as much as the wine itself.

Investment-grade Italian wines to know

While Italy produces an extraordinary range of styles, only a relatively small group of producers have built the kind of global reputation, scarcity, and long-term demand required to be considered truly investment-grade.

The wines below are among the most consistently traded and collected Italian labels, forming the backbone of many high-performing fine wine portfolios.

Top Barolo producers

Barolo remains Italy’s most internationally recognised collectible wine, and several estates have established themselves as long-term benchmarks:

  • Giacomo Conterno
    Widely regarded as one of the most important names in Barolo. Monfortino Riserva is among Italy’s most iconic and investment-relevant wines, consistently commanding premium market pricing.
  • Giuseppe Rinaldi
    A cult producer with extremely limited production. Rinaldi Barolo has long been a collector favourite, with demand far outstripping supply.
  • Bartolo Mascarello
    Famous for its traditional style and unwavering consistency. Mascarello’s Barolo is a staple of serious Italian collections, prized for both provenance and ageing ability.
  • Bruno Giacosa
    Known for producing some of Piedmont’s most elegant and refined wines. Bottlings such as Barolo Falletto and the estate’s Riserva releases remain highly sought after.
  • Vietti
    A collector-friendly producer with broad distribution, consistent critic attention, and strong brand recognition. Vietti’s single-vineyard Barolos are widely followed.
  • Luciano Sandrone
    One of Barolo’s most respected modern-era producers, with a strong track record for quality and international demand.
  • Roberto Voerzio
    Highly allocated and limited in volume, Voerzio’s wines have become increasingly important in collector circles.
  • Elio Altare
    A pioneering modernist producer whose Barolos remain highly regarded for their intensity and style.
  • Cappellano
    A cult name best known for Pie Rupestris, increasingly recognised as a serious collectible Barolo.

In general, the most investment-relevant Barolos are those with a combination of scarcity, critical reputation, and a recognisable brand identity – particularly wines tied to celebrated crus such as Cannubi, Monfortino, Brunate, Bussia, Rocche dell’Annunziata, and Cerequio.

Leading Barbaresco estates

While Barolo tends to dominate headlines, Barbaresco has become one of the strongest growth categories in Italian fine wine, often delivering exceptional quality with slightly earlier drinking windows.

Key investment-grade Barbaresco names include:

  • Gaja
    The global powerhouse of Barbaresco. Single-vineyard wines such as Costa Russi, Sori Tildin, and Sori San Lorenzo remain among the most traded Italian wines worldwide.
  • Roagna
    Roagna is a producer with rising collector demand, known for long macerations, terroir transparency, and extremely age-worthy wines.
  • Bruno Giacosa
    Giacosa’s Barbaresco releases are often considered some of the region’s most refined expressions.
  • Produttori del Barbaresco
    One of the most important cooperative estates in the world. Their single-vineyard Riservas offer strong quality-to-price value and have earned growing collector attention.
  • Ceretto
    A well-known producer with broad recognition and strong positioning in international markets.
  • Sottimano
    Sottimano is increasingly sought after by collectors for its purity and quality.

For many collectors, Barbaresco represents one of the most compelling Italian categories due to its prestige, lower relative pricing (vs Barolo), and strong long-term market momentum.

Other Piedmont wines collectors watch

While Nebbiolo dominates Piedmont’s investment landscape, the region also produces collectible wines outside the Barolo/Barbaresco framework:

  • Barbera d’Alba (top cuvées) from producers such as Giacomo Conterno and Vietti
  • Langhe Nebbiolo from elite estates, increasingly viewed as entry-level collector wines
  • Alto Piemonte Nebbiolo (Gattinara, Boca, Lessona), a category gaining interest among sophisticated collectors

Tuscan benchmarks: Brunello, Chianti Classico and Super Tuscans

If Piedmont is defined by tradition and Nebbiolo, Tuscany is defined by global brand strength and diversity. Tuscany’s finest wines are among the most recognisable Italian labels in the world, making them particularly attractive to collectors seeking liquidity.

Brunello di Montalcino

Brunello is one of Italy’s most age-worthy and internationally respected wines. The most investment-grade producers include:

  • Biondi-Santi
    A historic name often regarded as Brunello’s spiritual home. Rare Riserva bottlings are especially prized by collectors.
  • Gianfranco Soldera (Case Basse)
    A cult-level producer whose wines are among the most sought-after Italian bottlings globally.
  • Salvioni
    Another low-production, high-reputation estate with growing global presence.
  • Casanova di Neri
    A modern benchmark, with wines like Tenuta Nuova and Cerretalto frequently followed by collectors.
  • Valdicava
    A key Brunello name with a strong reputation for power and ageing capacity.
  • Il Poggione
    A historic estate offering strong brand recognition and a consistent track record.

The best Brunello wines combine structure, longevity, and a reputation for consistent quality across vintages, making them increasingly relevant in diversified Italian wine portfolios.

Chianti Classico: Top estates worth watching

Chianti is often seen as a “drinking category,” but at the highest level, Chianti Classico is becoming increasingly collectable – particularly as producers push quality higher and vineyard sites become more clearly defined.

Notable names include:

  • Fontodi
  • Isole e Olena
  • Castello di Ama
  • Fèlsina
  • Ricasoli
  • Antinori (Badia a Passignano/Peppoli)

While Chianti Classico generally trades less than Barolo or Super Tuscans, top bottlings are increasingly viewed as long-term value plays for collectors.

The Super Tuscans: Italy’s most investable wines

If there is one Italian category that rivals Bordeaux in global brand power, it is Super Tuscan wine. These labels dominate auction catalogues, collector wish lists, and international trading platforms.

Sassicaia (Tenuta San Guido)

Arguably Italy’s most famous wine, Sassicaia combines prestige, ageing potential, and consistent global demand. For many collectors, it is the gateway into Italian fine wine investment.

Tignanello (Marchesi Antinori)

One of the original Super Tuscan wines and still one of the most widely recognised. It remains highly liquid in the secondary market and benefits from Antinori’s immense global reach.

Ornellaia

A benchmark Bolgheri estate known for polished, powerful wines and strong vintage consistency. Ornellaia’s limited art releases further elevate its collector status.

Masseto

Often considered Italy’s most coveted modern wine. Masseto is produced in very limited quantities and enjoys significant international demand, particularly in Asia and the US. Its pricing reflects its scarcity and cult reputation.

Solaia (Marchesi Antinori)

Another flagship Antinori wine, often compared to top Left Bank Bordeaux blends. Solaia remains highly collectible and typically outperforms many Italian peers in global visibility.

Guado al Tasso (Antinori)

A Bolgheri classic that has gained momentum among collectors as a slightly more accessible alternative to Sassicaia and Ornellaia.

Bolgheri, in general, has become one of Italy’s most important fine wine sub-regions due to its international style, strong critic scores, and consistent market liquidity.

Premium Amarone della Valpolicella

Amarone is a unique Italian wine style with a global following. While not all Amarone is investment-grade, a handful of producers have established strong reputations and consistent demand.

For collectors, Amarone offers diversification: it is stylistically different from Barolo and Brunello, yet still capable of long ageing and secondary market relevance.

  • Giuseppe Quintarelli
    The most iconic Amarone producer. Quintarelli’s wines are extremely limited, highly allocated, and among the most collectable wines of Veneto.
  • Dal Forno Romano
    A powerful modern benchmark. Dal Forno’s Amarone is often compared to cult Napa Cabernet in intensity and concentration, and it remains highly sought after.

The best Italian wines combine history, craftsmanship, and longevity in a way few other categories can match. For drinkers, they offer endless discovery. For collectors, they offer scarcity, prestige, and long-term relevance.

As global demand continues to grow, Italian wines are no longer the “alternative” to Bordeaux or Burgundy – they are a cornerstone of the fine wine market in their own right.

FAQs about the best Italian wines

What are the best Italian wines for beginners?

Chianti Classico, Barbera d’Alba, and Valpolicella offer approachable introductions to Italian wine styles.

What are the most famous Italian wines?

Barolo, Brunello di Montalcino, Amarone, Chianti Classico, and Super Tuscans are among the most famous Italian wines globally.

Are Italian wines good investments?

Select Italian wines – particularly from Piedmont and Tuscany – have proven to be strong long-term performers in the fine wine market.

Which Italian wines age the longest?

Barolo, Barbaresco, Brunello di Montalcino, and top Super Tuscans are among the most age-worthy Italian wines.


Feature image: Tenuta San Guido

Categories
News

Wine alcohol volume and UK duty explained

  • The wine’s alcohol by volume (ABV) directly determines the UK wine duty rate.
  • Higher wine percent alcohol now means higher duty, directly influencing retail prices.
  • Understanding alcohol content of wine is becoming essential for both consumers and the wine trade.

From 1 February 2026, the UK Government implemented a new alcohol duty increase across all drinks, including wine, beer and spirits, rising with inflationary measures designed to preserve the real-term value of tax receipts. This follows duty reforms initiated in 2023 and cements the strength-based system that taxes wine according to its alcohol by volume (ABV) – essentially the wine alcohol volume or alcohol percentage wine contained in the bottle rather than a simple flat rate per litre.

Crucially for consumers and the wine trade alike, alcohol content of wine – expressed as alcohol by volume wine – directly influences duty bills and therefore retail prices.

Duty by alcohol strength

The updated system calculates duty based on the pure alcohol in the bottle – meaning that wine percent alcohol (e.g., 12% vs 14% ABV) changes how much tax is levied. Wines between 8.5% and 22% ABV now incur a rate of £30.62 per litre of pure alcohol, with still wines between 3.5% and 8.4% ABV taxed at £26.61. Incremental duty rates continue up the strength ladder.

This structure rewards lower-strength styles slightly – a bottle at 11.5% ABV pays less duty than one at 14.5% ABV – and reflects a policy intention to align tax more closely with alcohol per volume wine.

Recent analysis suggests the 2026 rise, based on Retail Price Index inflation, increases the duty on average wines by roughly 3.5-4.3% on top of the tiered rates already in place.

Why ABV in wine matters 

Since duty links to alcohol by volume, producers must account for shifts in average wine alcohol volume when forecasting costs and pricing.

  • A 13% ABV wine now pays about £2.88 in excise tax per bottle, up compared to previous years.
  • A 14.5% ABV wine pays more, thanks to a higher pure alcohol content translating into more duty per bottle.

For everyday drinkers, this means understanding the alcohol percentage in wine isn’t just about taste or body; it also affects the share of duty baked  into your bottle price.

Wine sector reacts

Industry groups have responded with concern:

  • The Wine and Spirit Trade Association (WSTA) has warned repeated duty increases – on top of other business costs – strain margins across the retail and on-trade sectors, potentially dampening investment.
  • With the UK importing more than 1.7 billion bottles of wine annually, alcohol duty remains a significant revenue source – contributing to £8.5 billion of the £12 billion alcohol duty total – but this essential income must balance industry viability.

Wine businesses, especially independent importers and smaller producers, are adjusting pricing strategies to manage tighter margins while educating customers around alcohol content of wine and its implications for duty and price.

UK vs other markets

The UK’s approach to taxing wine based on alcohol by volume (ABV in wine) contrasts with several other major markets:

  • European Union (EU) countries set minimum excise duty standards but can apply national rates above these minima; some member states impose no excise on wine at all, depending on policy direction.
  • In the United States, federal excise duty on still wines is based on volume (per wine gallon) and is structured around alcohol by volume (ABV) bands, with additional excise taxes levied at the state level.
  • Australia taxes wine at a flat 29% Wine Equalisation Tax on wholesale value rather than strength, with rebate schemes for producers.

These differences highlight how alcohol tax policies vary globally – and how the UK’s strength-based model aligns with broader public health goals while complicating pricing strategies for wines with higher wine percent alcohol.

Consumer impact 

The consumer price impact depends on multiple factors beyond duty, including VAT, retailer margin, and distribution costs. But generally:

  • Higher ABV wines will carry higher duty contributions, pushing up shelf prices relative to lower-ABV wines.
  • Lower-strength and lighter styles may become more appealing to price-sensitive shoppers.

Retailers may increasingly highlight the alcohol content of wine alongside tasting notes and provenance to help consumers make informed choices.

Investment-grade wine, duty, and in-bond storage

An important distinction in the discussion around alcohol duty is how it applies to investment-grade wine stored in bond.

By storing wine in a bonded warehouse under HMRC supervision, investors avoid alcohol duty and VAT while the wine remains in storage. In practical terms, changes to UK alcohol duty do not affect the investor while the wine stays in bond.

This structure underpins the fine wine investment market. Investors buy, sell, and trade wine in bond without triggering duty or VAT. HMRC only levies duty if and when you remove the wine from bond for UK consumption; at that point, the authorities calculate tax based on the wine’s alcohol content at the prevailing rates.

For collectors and investors, this offers several advantages:

  • No duty or VAT while trading – allowing capital to be allocated efficiently
  • Liquidity – wines can change ownership without physical movement
  • Flexibility – duty is only paid if the wine is eventually consumed

From an investment perspective, this also means that rising alcohol duty linked to alcohol volume wine primarily affects drinkers, not investors, provided the wine remains in bond. As a result, duty increases tend to have limited impact on the pricing of investment-grade wines, which typically trade on a duty-suspended basis.

However, for those planning to drink their wines in the future, it remains important to factor in potential duty costs – particularly for higher-ABV wines – when deciding whether to withdraw bottles from bond.

WineCap FAQ – Alcohol duty and wine

Q: What is wine alcohol volume and why does it matter?
A: It’s the measure of alcohol content expressed as a percentage (ABV). In the UK’s duty system, higher alcohol by volume wine means more duty per bottle, ultimately affecting pricing.

Q: Has duty increased for all wines in February 2026?
A: Yes – duty on wine rose broadly in line with inflation and remains tied to ABV rather than a single flat rate, meaning stronger wines see proportionally more tax.

Q: Does higher ABV always mean higher duty?
A: Under the current system yes – alcohol per volume wine (i.e., ABV) is directly linked to duty charges.

Q: How do UK duty rates compare with other countries?
A: The UK is among countries that tax wine excise based on alcohol content. Others, like the US and Australia, use different structures; some EU countries apply minimal or no excise on wine.

Q: Will this tax system change again soon?
A: Duty rates are typically reviewed annually in the Budget and Spring Statements. Future reforms could further adjust how wine percent alcohol influences duty.

Categories
Special-reports

Fine Wine Taxation | Guide

Fine wine offers you a sound and lucrative investment. While traditional investors have only fairly recently discovered the tremendous opportunities available with fine wine, collectors have known about its profit-making value for hundreds of years. Through the centuries, shrewd wine lovers have been selling part of their collections as a way of subsidising their consumption, leveraging the gains of a uniquely rarifying asset against their own cellars.

Granting easy access to this highly lucrative asset, WineCap offers extensive advice from a team of seasoned experts who can help with sourcing, storage and other crucial aspects to wine investment. With the benefit of our industry-leading technology, we can help you make the most of a bespoke portfolio and reach your investment goals. 

Acting as agents, we take care of sourcing your wine and organising its storage and insurance while you remain in complete control over your investment. Thanks to our links to the UK, you’ll benefit from the most developed secondary fine wine market there is. You’ll also enjoy access to the worldwide wholesale market via the London International Vintners Exchange known as Liv-ex, allowing you to secure a fast and fruitful sale once you’ve reached your investment goals. Lastly, we feature an unparalleled global reach while being tactically positioned in London, the fine wine market’s premier hub.

Click the button below to download our Fine Wine Taxation Guide and learn more about our proven strategy for investment success. Do not hesitate to get in touch and speak to one of our wine investment advisors for further information and to reserve your allocations.


Fine Wine Taxation Guide
Download
Categories
Learn

White wine types: Grapes, styles and investment-worthy bottles

  • Most white wines are made for freshness and early drinking, limiting long-term investment appeal.
  • A small number of categories – notably white Burgundy and German Riesling – are major exceptions with proven ageing and collector demand.
  • Sweet white wines like Sauternes and Barsac also offer historical prestige and investment potential in top names and vintages.

White wine represents some of the most diverse and widely consumed styles in the world that have been rising in popularity over the last decade. From crisp Sauvignon Blanc to rich Chardonnay, from bone-dry Riesling to the world’s greatest sweet wines, the category spans an extraordinary range of flavours, regions, and winemaking traditions.

Yet despite this breadth and growing consumer interest, white wine remains a smaller part of the fine wine investment market than red wine. While collectors have historically focused on Bordeaux First Growths, Burgundy Grand Crus, and top Italian reds, only a handful of white wine categories consistently attract long-term secondary market demand.

So which white wines are simply made to drink, and which are genuinely investment-worthy?

In this WineCap guide, we explore the major white wine types, the most important white wine grapes, the difference between dry and sweet white wine, and the specific categories where white wine becomes collectible.

What are the main types of white wine?

There are several often overlapping white wine categories:

  • Wines defined by grape variety (Chardonnay, Riesling, Sauvignon Blanc)
  • Wines defined by sweetness (dry white wine vs sweet white wine)
  • Wines defined by region (White Burgundy, Mosel Riesling, Bordeaux Blanc)
  • Wines defined by ageing potential (fresh vs cellar-worthy)

Unlike red wines, where tannin and structure often imply longevity, white wines vary dramatically: from light and aromatic to intensely age-worthy.

For most consumers, white wine is associated with refreshment and immediacy. For collectors, however, the question looks different: which whites have the structure to age and the scarcity and demand required to increase in value?

White wine grapes: the most important varieties

Chardonnay

Chardonnay is the world’s most famous white grape – and the backbone of the most collectible dry white wines.

It is uniquely versatile, capable of producing:

  • Lean, mineral wines (Chablis)
  • Rich, oak-aged wines (Meursault)
  • The world’s greatest dry whites (Montrachet)
  • Sparkling base wines (Champagne Blanc de Blancs)

Investment relevance: Extremely high at the top end of Burgundy.

Sauvignon Blanc

Sauvignon Blanc is defined by freshness, citrus aromatics, and bright acidity.

Key regions include:

  • Loire Valley (Sancerre, Pouilly-Fumé)
  • Bordeaux Blanc blends
  • New Zealand

Most Sauvignon Blanc is produced for early drinking, limiting its collectability.

Investment relevance: Limited, except for rare classified Bordeaux white blends.

Riesling

Riesling is arguably the most age-worthy white grape in the world.

It can produce wines ranging from bone-dry to intensely sweet, with acidity that allows the finest examples to age for decades, sometimes a century.

Key regions:

  • Mosel
  • Rheingau
  • Nahe
  • Alsace

Investment relevance: Very high in top German Riesling.

Pinot Gris / Pinot Grigio

Typically light, approachable, and widely consumed young.

Investment relevance: Minimal.

Chenin Blanc

Chenin Blanc is highly versatile, producing dry, sparkling, and sweet wines.

Key region: Loire Valley (Vouvray, Savennieres).

Investment relevance: Niche, but growing among collectors.

Semillon

Semillon is essential in Bordeaux sweet wines such as Sauternes, and often blended with Sauvignon Blanc in dry Bordeaux whites.

Investment relevance: High in Sauternes’ top names.

Dry white wine vs sweet white wine

Dry white wines

Most global white wines are dry, including:

  • Chardonnay
  • Sauvignon Blanc
  • Dry Riesling
  • White Burgundy
  • Dry Bordeaux Blanc

These dominate restaurant consumption and everyday drinking.

Sweet white wines

Sweet whites include:

  • Sauternes
  • Barsac
  • German Auslese and Trockenbeerenauslese Rieslings
  • Tokaji Aszú

Sweet wines often have extraordinary ageing potential but investment demand is more niche.

Why white wine is a smaller investment market than red wine

White wine makes up a significant share of global production and consumption, but a much smaller share of investment-grade trading.

There are several reasons.

1. Most white wines are made for early drinking

Freshness is often the selling point, not longevity.

2. Lower tannin structure

Tannin helps preserve red wines for decades. Many whites rely on acidity instead, narrowing the range of cellar-worthy examples.

3. Fewer secondary market benchmarks

The fine wine market depends on benchmark regions. For whites, those benchmarks are concentrated in only a few areas.

4. Collector psychology still favours reds

Historically, prestige collecting has been dominated by Bordeaux and Burgundy reds, shaping demand patterns.

The reality is that white wine investment is not a broad market but a selective one. Where scarcity, longevity, and global demand align, white wine becomes truly collectible. Where they do not, it remains primarily a drinking category.

The investment exceptions: white wines that truly matter

Despite these constraints, several categories of white wine are undeniably blue-chip.

1. White Burgundy: the benchmark investment white wine

If there is one region that defines investment-grade white wine, it is Burgundy.

While red Burgundy dominates headlines, the region’s greatest whites – made almost entirely from Chardonnay – represent some of the most sought-after and scarce wines in the world. In many cases, demand for top white Burgundy now rivals (and sometimes exceeds) demand for equivalent reds.

White Burgundy’s investment relevance is concentrated in the Côte de Beaune, where the finest vineyard sites produce wines that combine richness, minerality, and longevity.

Key white Burgundy appellations collectors focus on

Chablis

Located in northern Burgundy, Chablis produces some of the world’s most mineral-driven Chardonnay.

  • Grand Cru vineyards like Les Clos and Vaudésir represent the collectible tier.

Meursault

Perhaps the most famous village for rich, textured white Burgundy.

  • Premier Crus such as Perrières and Genevrières are highly sought-after.

Puligny-Montrachet

Often considered the spiritual heart of Burgundy’s greatest whites.

  • Home to Montrachet and Chevalier-Montrachet.

Chassagne-Montrachet

Puligny’s neighbour, producing whites that can be broader and more opulent, with enormous collector demand.

Corton-Charlemagne Grand Cru

One of Burgundy’s most important Grand Cru whites, prized for structure and long ageing horizons.

The pinnacle: Grand Cru Chardonnay

At the very top sits Montrachet, widely regarded as the greatest dry white wine vineyard on earth.

Key investment producers include:

  • Domaine Leflaive
  • Coche-Dury
  • Domaine Ramonet
  • Domaine Roulot
  • Domaine de la Romanée-Conti (Montrachet)

WineCap view: White Burgundy is the clearest example of white wine functioning as a true blue-chip asset class.

2. German Riesling: the most age-worthy white grape

If Burgundy is the luxury benchmark for Chardonnay, then Germany is the benchmark for Riesling.

German Riesling occupies a unique position: it is intellectually revered among collectors, yet still underappreciated by mainstream consumers, creating an interesting investment dynamic.

What makes Riesling compelling is its combination of:

  • piercing acidity
  • low alcohol
  • extraordinary longevity
  • transparent terroir expression

Key German Riesling regions

Mosel

The most famous Riesling region, defined by steep slate vineyards.

Top producer: JJ Prüm

Rheingau

Historically prestigious, producing structured dry Rieslings.

Top producer: Robert Weil

Nahe

A rising star with increasing collector focus.

Top producer: Dönnhoff

Pfalz

Known for richer, powerful dry Rieslings.

Top producer: Keller

WineCap view: German Riesling is one of the few white wine categories with both heritage and genuine investment upside.

3. Bordeaux white wines: dry blends with prestige

Bordeaux is synonymous with red wine, but its greatest whites are quietly compelling and increasingly collectible.

Dry Bordeaux whites are typically blends of:

  • Sauvignon Blanc
  • Semillon

Key subregions for Bordeaux white wine

Pessac-Léognan

The epicentre of serious dry Bordeaux whites.

Top wines include:

Graves

Historically important for structured dry whites.

Entre-Deux-Mers

Produces lighter early-drinking whites, not typically investment relevant.

WineCap view: Bordeaux whites are niche collectibles, best approached through the top estates.

4. Sweet white wines: Sauternes and Barsac

Sweet wines occupy a fascinating position.

Historically, they were among Europe’s most prestigious wines. Yet modern demand has narrowed, leaving the category highly selective.

The benchmark sweet whites come from Sauternes and Barsac, where noble rot concentrates sugars and flavours into wines of extraordinary richness and longevity.

Key sweet wine appellations

Sauternes

Home to Château d’Yquem – the only Premier Cru Supérieur in 1855.

Barsac

Often producing fresher, more lifted wines.

Key estate: Château Climens

WineCap view: Sauternes is heritage collectible rather than a broad growth market, with Yquem as the clear standout.

White wine ageing ability: what lasts?

Whites that age exceptionally well:

Whites that are usually early-drinking:

  • Pinot Grigio
  • Most Sauvignon Blanc
  • Entry-level Chardonnay
  • Commercial aromatic whites

Ageing ability is one of the strongest dividers between wine to drink and wine to collect.

WineCap view: white wine is selective, not broad

White wine is essential to the global wine conversation but the investment market remains highly concentrated.

Most white wines are:

  • produced for freshness
  • consumed young
  • not traded actively
  • difficult to benchmark

However, at the top tier, white wine becomes truly blue-chip. WineCap considers these categories the most investment-relevant:

FAQ: White wine types 

What are the main types of white wine?

Chardonnay, Sauvignon Blanc, Riesling, Pinot Grigio, Chenin Blanc, and Semillon-based wines.

Is white wine sweet?

Some whites are sweet, but most are dry.

What is the best dry white wine?

White Burgundy and top dry Riesling are among the greatest from a collectors’ perspective.

Can white wine be investment-worthy?

Yes, but only selectively – particularly white Burgundy, German Riesling, and rare Bordeaux whites.

Do white wines age well?

Some do. High-acid, structured whites can age for decades.

Categories
Learn

Orange wine explained: Trends, history and investment reality

  • Orange wine is trending globally, but remains a niche category in the fine wine market.
  • Demand is driven by drinkers, not collectors, limiting investment relevance.
  • Ancient in origin, modern in branding, orange wine sits outside blue-chip benchmarks.

Orange wine has become one of the most visible wine trends of the past decade – a style that dominates progressive restaurant lists, natural wine shelves, and social media feeds. Its amber hue and unconventional structure make it instantly distinctive.

However, from an investment standpoint, orange wine occupies a very different space from the blue-chip categories that define the fine wine market. While Champagne, Burgundy and top Bordeaux continue to attract global collector demand and measurable secondary-market liquidity, orange wine remains largely consumption-driven – fascinating to drink, but rarely traded, benchmarked, or treated as an asset.

That is not because orange wine lacks history. In fact, the techniques behind it may be among the oldest in the world. Instead, it reflects a category where cultural momentum has not translated into investment fundamentals.

Below, we explore what orange wine is, where it comes from, why it has risen in popularity and why it remains, for now, a wine trend rather than a collectible market.

We clarify why its investment potential is limited, highlighting how it compares to portfolio-grade wine segments.

What is orange wine?

Orange wine is best understood as white wine made using red wine production methods.

Instead of pressing white grapes immediately and fermenting only the juice, orange wine is fermented with the grape skins – and sometimes stems – for an extended period. This process, known as skin contact, extracts colour, tannins, texture, and phenolic complexity, producing wines that range from golden amber to deep orange in appearance.

Despite the name, orange wine has nothing to do with oranges or citrus fruit. The colour comes entirely from the grape skins.

Orange wine is also commonly referred to as:

  • Skin-contact white wine
  • Amber wine (particularly in Georgian traditions)

This simple shift in technique creates a style that sits between categories: structurally closer to red wine, yet aromatically rooted in white grapes.

How is orange wine made?

The defining feature of orange wine is maceration: the extended contact between grape juice and skins.

Most conventional white wines are pressed off skins quickly to preserve freshness and minimise tannin. Orange wine does the opposite: it embraces skin contact to build depth and structure.

Key variables include:

Length of skin contact

This can range from a few days to several months. Longer maceration generally increases tannin, grip, and savoury complexity.

Fermentation vessels

Orange wines can be made in:

  • Stainless steel (cleaner, fruit-driven styles)
  • Oak barrels (more oxidative, structured examples)
  • Amphora or clay vessels (traditional, earthy styles)
  • Georgian qvevri (buried clay pots used for millennia)

Winemaking philosophy

Orange wine overlaps heavily with the natural wine movement, though not all orange wines are “natural.” The technique is separate from the ideology. The result is one of the wine world’s most diverse categories – exciting, but also highly variable.

Where did orange wine originate?

Orange wine may feel modern, but its origins are ancient.

The most frequently cited historical anchor is Georgia, where winemakers have produced skin-contact wines for thousands of years using traditional clay vessels called qvevri. This method is so culturally significant that UNESCO has recognised the ancient Georgian qvevri winemaking tradition as part of humanity’s intangible heritage.

What is new is not the practice, but the label. The term “orange wine” itself was coined in 2004 by British importer David A. Harvey as a way to describe this hard-to-classify style in accessible language. The name stuck, helping transform an old technique into a modern global category.

Orange wine vs white wine: what’s the difference?

One of the most common questions is how orange wine differs from traditional white wine. 

White wine vs orange wine

Orange wine occupies a middle ground: it can drink like a white, but behave like a red at the table.

Why has orange wine become so popular?

Orange wine’s rise is best understood as the overlap of three powerful trends.

1. The natural wine movement

Orange wine fits neatly into the minimal-intervention narrative: ancient techniques, lower additives, small producers, authenticity. It became a signature style within the broader natural wine boom.

2. On-trade influence

Sommeliers embraced orange wine because it fills a useful gap. It pairs widely, offers guests something new, and provides a “third lane” between red and white.

3. Social media visibility

Orange wine is visually distinctive. Its colour, story, and identity are easy to communicate in a single image or short video, making it one of the most shareable wine categories of the last decade.

Like many trends, however, enthusiasm can be cyclical. Some markets have already seen drinkers shift toward adjacent styles, such as chilled reds, after peak orange wine experimentation.

Orange wine: Flavour profile

Orange wine reveals a spectrum of flavours. Common tasting characteristics include:

  • Dried apricot and orange peel
  • Herbal tea and chamomile
  • Nuts, spice, and savoury tones
  • Oxidative notes in some traditional styles
  • A firm, tannic grip uncommon in white wine

For adventurous drinkers, this is precisely the appeal. But for investors, it highlights the category’s stylistic inconsistency.

Best orange wine regions to know

Orange wine is now global, but several regions remain reference points:

  • Georgia – the historic home of qvevri wines
  • Friuli-Venezia Giulia (Italy) – a modern epicentre for serious skin-contact whites
  • Slovenia (Brda/Goriška) – cult producers and structured examples
  • Austria and Alsace – aromatic varieties well suited to maceration

These regions help reinforce orange wine’s credibility; however, this growing reputation for quality does not always translate into collectability.

Why orange wine is interesting for drinking

If your goal is pleasure per pound (rather than return per annum), orange wine can be genuinely compelling:

It’s food-friendly in a way most whites aren’t

Tannin and savoury texture means orange wine can handle:

  • Spice and aromatics (think Middle Eastern, North African, Thai-inspired dishes)
  • Umami-heavy plates
  • Rich vegetables and fermented flavours

It offers a “third lane” between white and red

For drinkers interested in exploring styles beyond the obvious categories, orange wine is a legitimate alternative, especially when served slightly cool, like a light red.

It rewards curiosity

Because methods differ wildly, orange wine invites exploration: maceration length, vessel choice, grape variety, oxidative handling, and winemaker intent all show up clearly.

Why isn’t orange wine “investment-grade” in most cases?

Popularity doesn’t automatically create an investment market. Fine wine investment tends to concentrate where the market has deep liquidity, transparent pricing, repeatable demand, and established benchmarks.

1. Liquidity: there isn’t a thick secondary market

Most orange wine is produced in small volumes by small producers and bought to drink, not trade. That typically means:

  • Fewer repeat transactions
  • Wider bid:offer spreads
  • Less reliable exit options

2. Benchmarking: pricing is fragmented

Investment-grade wine categories like Bordeaux, Burgundy, and Champagne benefit from comparable “reference labels” across vintages and formats. Orange wine is too stylistically diverse – and too producer-fragmented – to form a stable, broadly recognised benchmark set in the way Bordeaux’s Growths or top Burgundy domains do.

3. Consistency and quality control can be uneven

Orange wine overlaps heavily with minimal-intervention winemaking. When it’s great, it’s distinctive; when it’s flawed, it’s obvious. Some on-trade commentary has highlighted consumer fatigue with more extreme or inconsistent examples in certain markets. From an investment lens, variability increases risk and reduces broad-based demand on resale.

4. Cultural prestige hasn’t translated into “blue-chip” status

While range wine has history (Georgia) and cult producers (Friuli/Slovenia), the category lacks the long-established global collector infrastructure that underpins investment-grade segments – the kind of ecosystem visible in widely tracked fine wine indices and luxury-asset reporting. 

Can any orange wines be collectible?

Some orange wines may show collectible traits if they combine:

  • Producer cult status and long-term critical attention
  • Provenance-friendly packaging and consistent release patterns
  • Demonstrated longevity (some serious skin-contact whites can age)
  • Repeat demand from a niche but wealthy collector base

Even then, “collectible” is not the same as “investment-grade”.Without a robust resale venue and repeated market clearing prices, the potential remains very low at present.

WineCap view: orange wine is a trend, not an allocation

Orange wine is one of the most interesting modern wine stories because it flips expectations: it looks new, but its roots are ancient; it is fashionable, yet rarely traded; and it is driven more by experience than asset behaviour.

For most collectors, orange wine is best treated as:

  • A consumption-led category (buy to drink, not to flip)
  • A cultural trend worth understanding

Orange wine and blue chip investment summary

For investors seeking long-term appreciation, the market continues to favour regions with established liquidity and repeatable demand, including:

  • Top Champagne (Dom Pérignon, Krug, Salon)
  • Burgundy domaines with constrained supply
  • Classified Bordeaux with global recognition
  • Italian blue chips (Sassicaia, Giacomo Conterno)

Orange wine may be one of the most exciting categories to explore as a drinker but investment-grade wine remains defined by structure, scarcity, and market depth.

FAQ: Orange wine

What is orange wine?

Orange wine is white wine fermented with grape skins, creating an amber colour and tannic structure.

Why is orange wine orange?

Because extended skin contact extracts colour and phenolics from white grape skins.

How is orange wine different from white wine?

Orange wine has more tannin, texture, and savoury complexity due to skin fermentation.

Is orange wine natural wine?

Not necessarily. Orange wine refers to technique, while natural wine refers to philosophy.

Does orange wine age well?

Some structured examples can age, but the category is too broad to generalise.

Is orange wine a good investment?

In most cases, no. Orange wine lacks the liquidity, benchmarking, and collector infrastructure required for investment-grade status.