Categories
Learn

Wine investment: The complete 2026 guide

  • Wine investment means buying investment-grade wine, stored in bond, to sell later at a higher price: a long-term, unregulated alternative asset, not a savings product.
  • The Liv-ex 100 index fell 2.5% in 2025 after a three-year correction, and posted signs of stabilisation through the first half of 2026.
  • Realistic planning assumes a five to ten year hold, annual storage and management costs, and full awareness that prices fall as well as rise.

Wine investment is the purchase of a small, tightly defined group of wines with the aim of selling them later at a higher price. This guide explains the full mechanics for UK investors: what qualifies as investment grade, how buying and ownership work, what it costs, what returns the indices actually show, the risks, the tax position, and how to build and eventually exit a first portfolio. 

What wine investment actually is

Wine investment is narrower than wine collecting. An investor buys specific wines, almost always in sealed original cases, stores them professionally, and sells once age and scarcity have moved the price. The wine itself is the asset: there is no dividend, no coupon and no income along the way. Returns come entirely from the difference between purchase and sale price, minus costs.

The market that makes this possible is the secondary market (the trade in wines after their original release), where merchants, brokers and exchanges match sellers with buyers worldwide. London sits at its centre. Liv-ex, the London-based fine wine exchange, provides the price benchmarks the industry works from, and its indices function much like equity indices do for shares.

Scale matters here. This is a boutique market, not a deep one. Fewer than a few hundred wines trade with genuine regularity, and even the most liquid names change hands in cases, not milliseconds. That structure shapes everything that follows: pricing, holding periods, costs and exit routes.

What makes a wine investment grade

Investment-grade wine is defined by demand that outlives supply. A tiny fraction of global production qualifies, and the tests are consistent across regions. WineCap’s article on which types of wine are considered investment-grade treats this in depth; the short version follows.

  • Producer pedigree. The estate has a long record of critic scores and secondary market demand: Bordeaux classed growths, Burgundy’s top domaines, prestige Champagne houses, Tuscany’s leading estates, and a small group of Rhone, Spanish and Californian names.
  • Ageing capacity. The wine improves, or at least holds, for decades. A wine that must be drunk within ten years rarely builds secondary market value, and ageing capacity also matters for tax treatment, covered later in this guide.
  • Scarcity with consumption. Production is limited and bottles are steadily drunk, so supply of any vintage only falls over time.
  • Provenance and format. Original wooden cases, bonded storage history and clean documentation command the strongest prices. Broken cases and unverifiable storage attract discounts or no bid at all.
  • A liquid market. The wine trades often enough for prices to be observable. WineCap’s Wine Track database follows around 3,750 investment-relevant wines for exactly this reason.

A useful mental model: the market pays for predictable excellence. Petrus, the subject of WineCap’s guide to the world’s most valuable Bordeaux wine, commands its prices because roughly six decades of vintages have taught buyers what a bottle is worth. New names enter the investment grade slowly, over many vintages, not on one good review.

Why investors put money into fine wine

The investment case rests on structural features of the market rather than any promise about returns. Investors typically cite four.

Supply falls while demand can grow. Each investment-grade vintage is fixed at bottling, and consumption removes stock every year. A 2005 Bordeaux First Growth becomes scarcer every time a bottle is opened, and no producer can make more of it. Few asset classes have supply that mechanically shrinks.

Low correlation with financial markets. Fine wine prices respond to their own supply and demand cycle, critic reassessments and collector wealth rather than to quarterly earnings. Wine still fell in the 2022 to 2025 downturn, so low correlation never means immunity, but drivers differ from equities and bonds, which is why some investors use wine as a diversifier within a broader portfolio. WineCap’s overview of the wine investment market covers this dynamic in more detail.

A tangible, insurable asset. Cases in a bonded warehouse are physical property in the investor’s name, insured at replacement value. Tangibility carries its own obligations, storage and insurance among them, but many investors value owning something that cannot be diluted, delisted or rehypothecated.

An enjoyable subject. Wine rewards study in a way few asset classes do. The 70/30 rule applies to portfolios as well as prose: the investment case leads, and the pleasure of following producers, vintages and regions is a genuine, secondary benefit.

None of these features guarantees an outcome. The market’s own recent history, covered in the returns section below, is the clearest evidence of that.

How fine wine prices are set

Price formation in fine wine follows a logic every investor should understand before buying, because it explains both the opportunities and the traps. Three forces do most of the work: critical assessment, vintage quality and the arithmetic of shrinking supply.

Critics move markets. A high score from an influential reviewer at release, or a favourable rescore years later, changes what buyers will pay, sometimes within days. The effect is strongest in Bordeaux and Burgundy, where a wine’s score history is part of its trading identity. Rescoring works in both directions: a downgrade on retasting can mark a wine down as surely as an upgrade lifts it.

Vintage quality sets the starting terms. Growing-season weather determines whether a year produces wines built for decades or for early drinking, and the market prices the difference from the outset. Great vintages (2005, 2009, 2010 and 2016 in Bordeaux are commonly cited examples) carry premiums at release and typically hold demand longest. Lesser vintages from great producers can offer value, but they age out of the market sooner.

Scarcity then does the slow work. Once a vintage is bottled, every case opened anywhere in the world tightens the remaining supply. A wine entering its drinking window sits in a narrowing corridor: consumption accelerates just as the wine becomes most desirable. That corridor is where much of fine wine’s historical appreciation has occurred, and it is why holding periods matter so much.

Observable prices knit these forces together. Databases such as Wine Track track them daily across thousands of wines. An investor no longer needs to take a seller’s word for what a case is worth, which is precisely why any firm reluctant to benchmark its prices deserves suspicion.

How wine investment works in practice

The mechanics are simpler than most newcomers expect, and WineCap’s explainer on how wine investment works walks through them step by step. Money follows this path: an investor funds an account, wines are bought on the secondary market or at release, the cases move into bonded storage in the investor’s name, they rest there for years, and eventually they are sold back into the trade.

Four buying routes dominate the UK market.

  • Through a specialist platform or merchant. The investor sets a budget and criteria; the firm sources, stores and later sells the wine, charging fees for the service. This is WineCap’s model, with portfolios starting at a £5,000 minimum investment.
  • En Primeur. Buying Bordeaux (and increasingly other regions) as futures, one to two years before bottling, at the release price. WineCap’s short guide to En Primeur for wine investors explains the mechanics and the risks: paying early does not always mean paying less. 
  • At auction. Auction houses offer mature and rare bottles, with buyer’s premiums that routinely add 20% or more to the hammer price, and provenance that varies lot by lot.
  • Peer-to-peer and exchange trading. Experienced investors with trade accounts can deal via exchanges, taking on sourcing, verification and settlement themselves.

En Primeur deserves a closer look because its mechanics differ from every other route. The buyer pays for the wine while it is still in barrel, takes delivery into bond one to two years later, and carries counterparty risk on the producer and merchant chain in between. The historical bargain, release prices below eventual market prices, has not held reliably in recent campaigns, and several vintages released in the early 2020s later traded below their release prices on the secondary market. The route still offers first access to scarce wines and pristine provenance from day one; it simply has to be judged release by release, against secondary market prices for comparable back vintages, rather than bought on tradition.

Ownership is the detail to verify before any money moves, whichever route an investor takes. Reputable firms hold wine in the client’s name, segregated from company assets, in a recognised bonded warehouse. If the paperwork shows anything else, walk away. The collapse of poorly run wine firms has historically hurt clients whose wine was never truly theirs.

What it costs: minimums, fees and charges

Costs decide whether a paper gain becomes a real one, so they deserve the same attention as the wines themselves. A wine that rises 30% over five years, sold through a channel that takes 25% in combined charges, has enriched everyone except its owner.

Typical cost lines across the UK industry:

  • Entry minimums. Managed portfolios commonly start between £3,000 and £25,000 across the industry; WineCap’s minimum is £5,000.
  • Purchase spread or sourcing margin. The difference between the price paid and the wine’s prevailing market level. Ask any firm how its buy prices compare with market benchmarks.
  • Annual management and storage. Bonded storage and insurance are usually charged per case per year, with management fees a percentage of portfolio value.
  • Exit costs. Selling through a merchant or broker involves a commission or margin; auctions add seller’s fees. Factor the exit charge in before buying, not when selling.

Transparency is the test that matters. An investor should be able to see, in writing, every charge between deposit and eventual sale proceeds. Full fee details for WineCap portfolios are available on request and through a free consultation.

Storage, insurance and provenance

Professional storage is not optional at investment grade. The market pays for perfect condition, and perfect condition is only believable when a wine’s whole life is documented. UK investors use bonded warehouses (HMRC-approved facilities where duty and VAT are suspended), which solve three problems at once.

Condition is the first. Bonded facilities hold wine at stable temperature and humidity, in darkness, with minimal movement: the conditions critics and buyers assume when they price a mature case. WineCap clients’ wines are held at London City Bond’s Drakelow facility and insured at replacement value through Zurich.

Tax efficiency is the second. Wine held in bond has not cleared UK customs, so no duty or VAT falls due while it stays there, and a case can pass from seller to buyer within the bond without either charge crystallising. Most investment wine spends its entire life in bond for this reason.

Provenance is the third. An unbroken bonded history is the strongest evidence a buyer can ask for, and it feeds directly into resale value. Cases that leave bond for a private cellar can return, but the gap in the record usually costs money at sale.

Insurance completes the arrangement, and the details matter more than the headline. Cover should be at replacement value rather than purchase price, so a case that has appreciated is insured for what it would cost to replace today, and valuations should update as market prices move. Investors should also confirm whose policy applies: a warehouse’s blanket cover, the platform’s client policy, or their own. Photographic condition reports at intake, now standard at serious facilities, settle disputes before they start and add another layer to the provenance file that future buyers will pay for.

Returns: what the data actually shows

Honest data serves investors better than selective success stories, so this section reports the full cycle. Over the 20 years to 2022, the Liv-ex 100 index (the industry’s benchmark for the most traded fine wines) rose just over 300%. The market then corrected hard: from its October 2022 peak, the broad market fell roughly 30% over the following three years.

The recent numbers are sobering and specific. The Liv-ex 100 declined 2.5% in 2025, a year in which the Knight Frank Luxury Investment Index as a whole closed down just 0.4% (Knight Frank Luxury Investment Index, April 2026). Trade patterns shifted sharply too: US purchase value fell 43.6% year on year in 2025 under tariff pressure, while European purchases rose 48.2%.

The first half of 2026 has looked different. Liv-ex reported broadly stable indices in the first quarter, and US buying recovered to 26.9% of global purchase value in the second quarter, up from 23.3% in the first. WineCap’s own market coverage reached a similar reading in fine wine market starts 2026 on firmer footing.

Individual wines can diverge a long way from the index in both directions. Dom Ruinart Blanc de Blancs, a selected example rather than a representative one, shows a rise of 135% over ten years, a period across which the broad market first climbed steeply and then gave back a substantial part of those gains. Selection, in other words, is where managed research earns its keep, and it can subtract value as easily as add it when done badly.

Holding period shapes the outcome as much as selection does. Fine wine’s appreciation, where it occurs, accrues over the years in which scarcity tightens and a wine approaches its drinking window, and the market’s cycles run long: the recent correction alone lasted roughly three years. An investor with a five to ten year horizon can ride a full cycle; one who may need the money in two years is speculating on timing, in an asset that punishes forced sales. The industry convention of quoting five years as a minimum hold reflects this arithmetic rather than any promise about what five years will deliver.

Two disciplines keep return expectations honest. Measure any wine against the index over the same period, so a strong performer is seen in context. And treat every historical figure, including all of the above, as description rather than prediction: past performance is not a guide to future returns. WineCap’s approach to performance measurement is set out on our performance page.

The risks investors must price in

Every genuine investment case survives its risk list. 

  • Prices fall. The 2022 to 2025 drawdown of roughly 30% is the current, lived reminder. 
  • Illiquidity. Selling takes weeks or months, not minutes. In a weak market, bids for even blue-chip wines can be thin, and a forced seller takes whatever the market offers.
  • No regulatory protection. Wine investment is unregulated in the UK. The Financial Conduct Authority does not authorise it, and investors have no access to the Financial Services Compensation Scheme or the Financial Ombudsman Service if a firm fails or a dispute arises.
  • Fraud and mis-selling. The sector has a documented history of scams, from cold-called “guaranteed return” schemes to firms selling wine they never owned. UK Trading Standards has prosecuted wine investment frauds running into tens of millions of pounds.
  • Cost drag. Storage, insurance, management and exit charges accrue every year, in flat and falling markets as well as rising ones.
  • Currency and policy shocks. The 2025 US tariffs moved global demand within months. Sterling investors also carry exchange rate exposure to a market that prices much of its demand in dollars.
  • Condition and provenance failures. A flooded warehouse, a faked case or a broken storage record can impair value regardless of what the index does.

Sizing is the practical defence. Most advisers who cover alternatives suggest they sit as a minority allocation within a diversified portfolio, money whose multi-year absence an investor can tolerate. Fine wine is a long-term investment that rewards patience.

How fine wine is taxed in the UK

Tax treatment is one of fine wine’s most cited attractions and one of its most misunderstood. The rules deserve precision, and WineCap’s detailed guides to the tax benefits of fine wine investment and to whether wine is a wasting asset for capital gains tax cover the full detail, including worked examples against 2026/27 thresholds.

The headline concerns capital gains tax. HMRC treats an asset with a predictable useful life of under 50 years as a “wasting asset”, exempt from CGT, and its Capital Gains Manual (CG76901) discusses how this applies to wine. Many everyday wines clearly qualify. The complication sits exactly where investors operate: investment-grade wines are built for decades of ageing, and HMRC’s guidance contemplates that fine wines capable of lasting beyond 50 years may not qualify for the exemption. The point is judged case by case, on the wine and the facts.

A second relief exists independently. Wine is a chattel (tangible movable property), and disposals of chattels for proceeds of £6,000 or less are exempt from CGT under HMRC’s chattels rules (HMRC, 2026/27), with marginal relief just above that level. Sales structured as separate cases to separate buyers are, however, aggregated where HMRC treats them as a set.

Duty and VAT behave differently again. Wine kept in bond suspends both until the wine clears customs, which is why bonded storage is the default for investment. Inheritance tax offers no special shelter: wine forms part of an estate at market value like any other possession, and estates with significant cellars need valuations and records their executors can rely on.

Pensions close one door investors sometimes ask about. Wine is tangible movable property, which HMRC’s pension rules treat as taxable property inside a SIPP (self-invested personal pension); holding it there triggers tax charges that remove any benefit, so wine investment sits outside pension wrappers in practice. The comparison with regulated, wrapper-eligible investments also restates a point this guide makes elsewhere: wine investment itself is unregulated in the UK, with no FCA authorisation, FSCS cover or FOS recourse.

Every part of this depends on individual circumstances, and the rules can change at any Budget. Treatment that applies to one investor’s cases may not apply to another’s. Independent tax advice, taken before selling rather than after, is the sensible course.

Building a first portfolio: regions and diversification

Diversification works in wine much as it does elsewhere: across regions, producers, vintages and price points, so no single reassessment or regional slump dominates the outcome. The starting map has five main territories, each with a distinct investment character.

Bordeaux remains the market’s backbone and its most liquid region, accounting for 35.5% of secondary market trade by value in 2025. The 1855 classification gives the Left Bank its hierarchy, from the five First Growths (Lafite Rothschild, Latour, Margaux, Mouton Rothschild and Haut-Brion) down through the classed growths, while the Right Bank contributes Petrus, Le Pin and the leading names of Saint-Emilion and Pomerol. Production volumes are large by fine wine standards, often ten to twenty thousand cases per wine per vintage, which is exactly what makes Bordeaux tradeable: price histories run for decades and a seller can usually find a bid. The so-called super seconds (estates such as Pichon Lalande and Lynch-Bages that trade below First Growth prices on comparable quality) are a common first purchase for value-minded investors.

Burgundy sits at the opposite pole. Production at the top domaines of the Cote de Nuits and Cote de Beaune is measured in hundreds of cases, sometimes fewer, and prices reach the market’s summit. Scarcity cuts both ways: it has driven some of the strongest long-run appreciation in the market, and it thins liquidity, widens pricing and raises the stakes on authenticity. Burgundy rewards knowledge and patience more than any other region, which is why most allocators treat it as a later addition rather than a foundation.

Champagne has become a core allocation rather than a satellite, led by prestige cuvees from houses such as Dom Perignon, Krug, Cristal and Salon. Its investment logic is unusually clean: these wines are drunk in celebration around the world, so consumption retires stock quickly, while house branding keeps demand broad. Italy contributes two poles of its own, Piedmont’s Barolo and Tuscany’s Brunello alongside the Super Tuscans (Sassicaia, Tignanello, Ornellaia and peers), and its share of secondary market trade grew through the recent downturn as buyers sought value outside France. The Rhone, Spain’s Vega Sicilia and California’s cult names (Screaming Eagle, Opus One) complete the usual map, adding breadth at various price levels.

Vintage and producer spread complete the diversification picture. Two cases of the same wine from different vintages behave differently: one may sit in its drinking window while the other is still climbing towards it. Producer concentration carries the same lesson. A portfolio built entirely on one estate, however grand, rides every rescore and every release decision that estate makes. Spreading across eight to twelve producers, several vintages and at least three regions gives a first portfolio the shape professionals build towards.

A first portfolio does not need all of them at once. A common approach weights liquid Bordeaux as the foundation, adds Champagne and Italy for balance, and treats Burgundy and cult names as later, selective additions. WineCap’s beginner’s guide to starting a wine investment portfolio in the UK works through allocation examples in detail.

Wine compared with whisky, art and other alternative assets

Fine wine competes for the same allocation as other collectible and passion assets. Structural differences matter more than any one year’s league table. Wine’s advantage over most rivals is market infrastructure: standardised units (the 12x75cl case), published exchange prices, professional bonded storage and a deep merchant network make fine wine unusually easy to value and to sell for a physical asset. Art sits at the opposite extreme, with unique objects, opaque pricing and sale costs that can consume a fifth of proceeds. Cask whisky has boomed on scarcity narratives but lacks wine’s central price benchmarks, which has made it a magnet for mis-selling; its regulatory position, like wine’s, is unregulated in the UK.

Wine’s disadvantages are equally structural. It is consumed rather than displayed, needs specialist storage, and its correction of 2022 to 2025 showed drawdowns can run for years. Watches and art can be enjoyed daily while held; a case in bond cannot, unless its owner is willing to sacrifice provenance. Investors weighing the categories usually conclude they are complements rather than substitutes, and that the honest comparison is less about which asset “wins” than about which risks an investor understands well enough to carry.

Common mistakes first-time wine investors make

Most mistakes in wine investment are avoidable at the point of purchase. Overpaying at entry is the most expensive and least visible mistake. A case bought 15% above its market level starts its life needing years of appreciation just to reach par. This is why correct valuations and price benchmarking against published market data, before every purchase, is the single highest-value habit an investor can build.

Concentration comes next. First-time portfolios built entirely on one region, one famous producer or one celebrated vintage carry risks their owners rarely price: a regional slump, a critical reassessment or a tariff decision lands on the whole portfolio at once. The 2025 trade data showed how quickly regional demand can rotate, with US purchase value down 43.6% while European buying rose 48.2%.

Ignoring costs quietly erodes the rest. Storage, insurance, management and exit charges continue in flat years, and an investor who never totals them can hold a “winning” wine to a losing outcome. Impatience compounds the damage: selling inside two or three years, before scarcity has done any work, frequently returns less than the wine cost once fees are counted.

The final mistake is the oldest: buying from the wrong counterparty. Wine bought from a cold call, at an unverifiable price, held in a warehouse the buyer cannot name, fails every test this guide has set out. 

How to start: a step-by-step path

The process from first research to funded portfolio is short. Care at each step matters more than speed.

  1. Define the budget and the horizon. Decide the sum, confirm it can stay invested for five to ten years, and place it inside a wider plan: fine wine belongs alongside other assets, not instead of them.
  2. Choose the route. Managed platform, self-directed buying through merchants, En Primeur, auction, or a blend. First-time investors usually start managed; the beginner’s guide to fine wine investment compares the options.
  3. Vet the firm. Apply the due-diligence questions in the next section before signing anything or sending money.
  4. Agree the mandate. Budget, regional spread, holding period and fee schedule, all in writing.
  5. Verify ownership and storage. Confirm the wines sit in your name in a recognised bonded warehouse, insured at replacement value, with documentation to prove it.
  6. Monitor without meddling. Track valuations against a benchmark, using tools like Wine Track. Fine wine repays annual reviews, not daily ones.
  7. Plan the exit from day one. Know how sales work, what they cost and how long they take, before the first case is bought.

Questions along the way have a natural home: WineCap’s help and FAQ centre answers the operational ones, from minimums to withdrawals.

How to sell wine and exit an investment

Exits define realised returns, and the secondary market offers several doors out. A managed platform sells on the client’s behalf through its trade network, handling logistics and documentation for its stated commission or margin. Independent owners can consign to a broker or merchant, list on an exchange through an account holder, or enter wines for auction, where seller’s commissions and settlement timescales vary house by house.

Practical selling discipline focuses on what an owner controls: selling from strength rather than necessity, keeping cases in bond with clean records so they are always saleable, spreading disposals rather than dumping a whole portfolio into one market moment, and comparing the net proceeds a route offers after every fee.

Settlement takes patience. From instruction to cash, a typical trade sale runs weeks; auctions can run longer once cataloguing and payment terms are counted. Investors who need money on a fixed date should sell well ahead of it.

Net proceeds are the only number that counts at exit, and they reward a simple habit: before instructing any sale, ask each available route for its all-in figure after commission, storage settlement and delivery charges, then compare that figure with the wine’s current market level. A route offering 95% of market value with two-week settlement often beats one dangling a higher headline through a slower, costlier channel. Sellers who run this comparison once tend to run it every time.

Choosing a wine investment company

The choice of counterparty carries as much risk as the choice of wine, in an industry where anyone can print a brochure. A short interrogation separates serious firms from the rest.

  • Ownership and segregation. Are wines held in the client’s name, segregated from company stock, in a named bonded warehouse? Ask to see a specimen storage account and insurance certificate.
  • Pricing transparency. How do purchase prices compare with market levels, and will the firm show the comparison? Opacity here is where poor outcomes usually begin.
  • The full fee schedule, in writing. Every charge from entry to exit, with nothing “available on request” that never arrives.
  • Track record and people. How long has the firm traded, who runs it, and what does its own published analysis look like? Independent reviews and press coverage add texture.
  • Realism in the sales conversation. A firm that leads with the 2022 to 2025 drawdown as readily as the 20-year rise is describing the same market this guide does. One that promises dependable returns is describing a market that does not exist, and the Advertising Standards Authority has upheld rulings against wine investment firms for exactly such claims (ASA, 2024 to 2025).
  • No pressure. Cold calls, countdown offers and “act now” framing are the classic markers of the sector’s fraud cases. Legitimate wine is still there next week.

WineCap publishes its data, methodology and market analysis precisely so investors can run these checks. A free consultation exists to answer them.

Where fine wine fits in a 2026 portfolio

The fine wine market entering late 2026 is a more honest proposition than the one marketed at the 2022 peak: repriced by a three-year correction, showing measured signs of stabilisation, and stripped of the easy narratives. That honesty suits serious investors. An asset bought with clear eyes, at a £5,000 minimum rather than a fortune, held in bond for years and measured against a public benchmark, can earn a place in a diversified portfolio precisely because its owner knows what it is and what it is not. The investors best positioned for the next cycle are the ones who understand the machinery this guide describes: what qualifies, what it costs, how it is taxed, and how they will one day sell.

FAQ: Wine investment in 2026

Is wine a good investment in 2026?

Fine wine can suit investors seeking a long-term, tangible, diversifying asset, but it is unregulated in the UK and illiquid compared with shares. Suitability depends on an investor’s horizon, existing portfolio and tolerance for drawdowns.

How much money do I need to start investing in wine? 

UK managed wine portfolios commonly start between £3,000 and £25,000; WineCap’s minimum investment is £5,000. Self-directed buying can begin with a single investment-grade case, though diversification across regions and vintages argues for a larger starting sum.

What returns can I expect from wine investment?

No future return can be promised. The Liv-ex 100 rose just over 300% in the 20 years to 2022, then the market fell roughly 30% over the following three years, and the index declined 2.5% in 2025 alone. Past performance is not a guide to future returns.

Is wine investment tax-free in the UK? 

Sometimes, not automatically. HMRC exempts “wasting assets” (predictable life under 50 years) from capital gains tax, and many wines qualify, but investment-grade wines built for long ageing may not; disposals of £6,000 or less may fall under the separate chattels exemption (HMRC, 2026/27). Treatment depends on individual circumstances and may change, so independent tax advice is essential.

How do I sell my wine investment? 

Wine sells through a managed platform’s trade network, via merchants and brokers, on exchanges, or at auction, with commissions and timescales differing by route. A typical trade sale takes weeks from instruction to settlement. Wines kept in bond with unbroken storage records achieve the strongest prices.

How do I avoid wine investment scams? 

Verify that wines are held in your name in a named bonded warehouse, demand the full fee schedule in writing, compare purchase prices with market levels, and treat cold calls, promised returns and pressure tactics as disqualifying. Wine investment is unregulated in the UK, with no FCA, FSCS or FOS protection, so this due diligence replaces the safety net.
Categories
Learn

What is the difference between auction and market prices in fine wine investment

  • Auction prices and market prices for fine wine are intrinsically linked yet understanding the distinction is important for valuations.
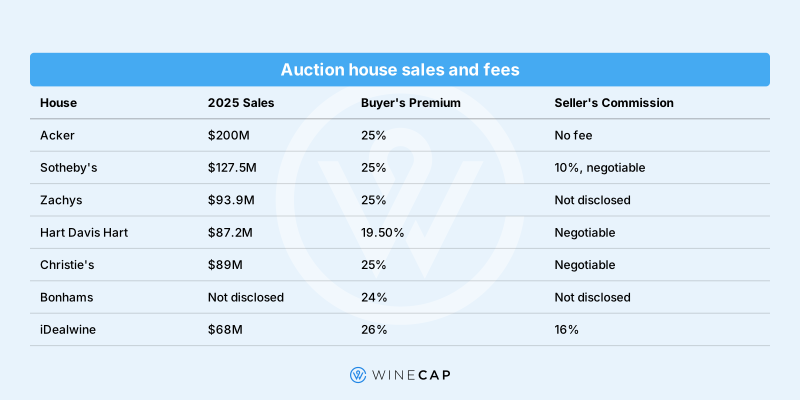
  • Buyer’s premiums of 25% are standard at most major wine auction houses, meaning that  the final price a buyer pays is almost always significantly above the hammer price.
  • For older vintages, auctions dominate fine wine trading.

For fine wine investors, a wine price can mean different things depending on where you look. An auction price records what a buyer was willing to pay for a particular wine at a particular moment, through a competitive bidding process. A market price, by contrast, is typically derived from the prices at which sellers are currently offering comparable wines on the secondary market.

The two are closely related, but they are not interchangeable. Auction results provide evidence of completed transactions, while market prices offer a broader view of current availability and seller expectations. Both are useful, and both have limitations. Understanding the difference – and knowing which measure to use when – is an important part of valuing fine wine.

What auction prices and market prices actually measure

In economic theory, the market price is the equilibrium point at which supply and demand meet. In fine wine, however, the term is used more practically.

A fine wine market price is typically a derived value based on the asking prices of multiple sellers active on the secondary market. It draws on dozens, and sometimes hundreds, of listings to establish the best available price for a comparable case in perfect, or reliably assumed to be perfect, condition.

It is therefore not the price at which one transaction has necessarily taken place. Rather, it is an aggregate view of what sellers are asking for the wine at a particular point in time – and, by extension, what a buyer could reasonably expect to pay to acquire it.

Platforms such as WineCap aggregate these listings into benchmark prices that act as reference points across the secondary market. Market prices simplify price discovery and reduce search friction for buyers and make comparison straightforward, particularly for younger wines in standard formats with clear provenance.

In economic theory auction prices are simply a way to ascertain a market price. A competitive bidding process sets the price in real time. The hammer falls at the highest bid, and that bid becomes the market price for whatever asset is being sold. 

In practice, the two are not synonymous and auction prices can be quite different from market prices. Auctions tend to maximise revenue for rare or scarce assets, because it surfaces the most motivated buyer available on that day. Arguably, that makes auction prices a truer expression of what a specific case of wine is worth at the moment of sale, but is less relevant to the price of another case. 

Auction prices tend to be more volatile, are often higher, and are most commonly seen with a narrower set of wines.

The fine wine auction market: who the players are

Wine auctions operate across a well-established hierarchy of houses. Sotheby’s and Christie’s lead the global auction market broadly, with significant wine departments. For wine specifically, an additional group of specialist auctioneers accounts for the largest share of trading volume. Most auctioneers announce their sales figures in US dollars.

  • Acker Merell and Condit: $200 million (approximately £157 million) in sales in 2025
  • Sotheby’s $127.5 million (approximately £100 million) in sales in 2025
  • Zachys: $93.9 million (approximately £74 million) in sales in 2025
  • Hart Davis Hart: $87.2 million (approximately £69 million), 19.5% buyer’s premium
  • Christie’s: $89 million (approximately £70 million) in sales in 2025

While Bonhams has a wine department, they do not disclose their total wine sales. Online platforms have also expanded the market. iDealwine, a France-based specialist, generated $68 million (approximately £54 million) in 2025 sales. Bid for Wine, owned by Dreweatts, is a regional British auctioneer and operates a comparable digital model in the UK. 

The cost of buying and selling at auction

Auction prices require careful translation before any comparison with market prices. The hammer price (the final bid at which a lot is sold) is not what the buyer pays, and it is not what the seller nets. Both sides face additional costs that can be very significant.

Buyers must add a premium to the hammer price. At most major wine auction houses, this runs at 25%, though Hart Davis Hart charges 19.5% and iDealwine charges 26%. On a case selling for £10,000 at the hammer, a 25% buyer’s premium means a total cost of £12,500 before any delivery or storage charges.

The picture for sellers is more opaque. Houses rarely disclose their commission rates upfront, and rates are almost always negotiable. Acker has set itself apart by charging no seller’s commission, a large part of the reason that they have grown in popularity and revenue. For attractive collections, auction houses compete actively for consignment, with seller’s fees being the major area of negotiation. A seller with a large holding of attractive wines can negotiate seller’s commission to zero. In the most competitive cases, a seller may even secure a proportion of the buyer’s premium, receiving more than 100% of the hammer price as a net return.

Why auction prices are more volatile than market prices

Auction results for the same wine can vary significantly. Condition and provenance (verifiable storage history and ownership chain) drive much of that variability. In the secondary market, younger wines sold in bond carry implied provenance: the storage record is clean by definition. At auction, bottles of varying age and condition compete for buyers who may hold very different views of the same lot.

For instance, in March 2023, three major auction houses sold Domaine de la Romanee-Conti, La Tache 2009. Including buyers’ fees, Acker achieved a case-price equivalent of £70,000, Zachys achieved £62,500, and Sotheby’s achieved £145,000.

At the time, Liv-ex showed a market price of £69,000 per case for the same wine. Wine quality does not explain the spread: the specification across all three lots was identical. The result reflects the specific bidder composition in each room on each day.

Auction prices to ignore: charity sales and distorted results

Not every auction result belongs in a price analysis. Charity auctions regularly produce figures that bear no relationship to market value. Tax treatment creates a real incentive to bid beyond market rates: in the United States, a donor who bids generously at a charity auction may benefit from a tax deduction that reduces their effective net cost. The psychological premium of supporting a high-profile cause adds a further layer. Charity auction results should be stripped from any serious valuation exercise.

The phenomenon extends well beyond wine. In August 2026, “Chassis Zero”, the first production model of Ferrari’s first electric vehicle, the Ferrari Luce, sold at an RM Sotheby’s charity auction during Monterey Car Week in California for $40 million (approximately £32 million). A standard Luce carries a list price of approximately 550,000 euros (roughly £470,000 at launch). No quality or rarity argument explains that gap.

The same distortion appears within wine. In 2026, Chateau Haut-Brion 1961 sold at Sotheby’s in Hong Kong for a case-price equivalent of £17,500, excluding fees. Ten days earlier, a magnum of the same wine sold at Christie’s in London for a case-price equivalent of £65,000, also excluding fees. The Christie’s sale was a charity event. An investor using that result to value their own bottles would overstate the figure by nearly four times.

When auction is the right marketplace

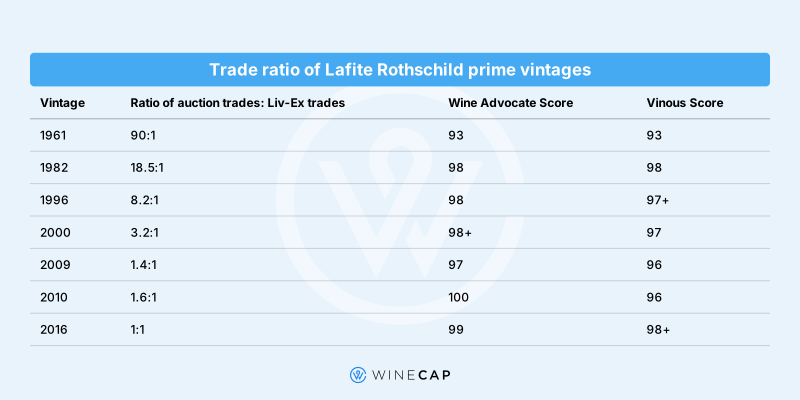
For older wines, auction is the dominant trading mechanism. Analysis of Chateau Lafite Rothschild across seven prime vintages shows how sharply the ratio of auction trades to Liv-ex secondary market trades shifts with age. The older the wine, the more the auction room dominates as the primary marketplace.

The same pattern holds across high-value, long-lived assets generally. Classic cars, watches, and fine art all see the same migration toward auction as the primary trading mechanism as they age and become genuinely rare. Knowing when to use auction prices as a valuation input, when to rely on secondary market benchmarks, and when to discard a result entirely as an outlier or a charity distortion is a genuine source of edge in this market.

FAQ: Auction vs market prices in fine wine investment

How do I know if an auction result is a reliable market reference?

Check three things before using any auction result as a valuation input: whether the sale was a charity event (if so, discard it), the condition and provenance notes on the lot, and whether multiple comparable results support the figure. A single result tells you far less than the range.

Is auction or the secondary market better for selling fine wine?

It depends on the wine and the vintage. Younger wines in bond with clean provenance typically achieve competitive results on the secondary market at lower transaction cost. Older and rarer bottles trade more actively at auction, where specialist buyers concentrate. 

What is the difference between the hammer price and the total cost at auction?

The hammer price is the winning bid, before fees. As a buyer, adding a 25% buyer’s premium to a £10,000 hammer price brings the total to £12,500, before any delivery or storage costs. As a seller, your net return is the hammer price minus any seller’s commission. Sellers of attractive collections can negotiate commissions to zero, or in some cases receive more than the hammer price through a share of buyer fees.

Why are older wines more likely to sell at auction?

As a wine ages, listed secondary market activity falls and auction becomes the primary venue where motivated buyers for rare, old bottles congregate. As our data above shows, that shift is measurable: the 2016 vintage trades equally between auction and Liv-ex, while the 1961 vintage trades at auction 90 times more frequently. Auction provides price discovery for assets with limited comparable transactions, which is precisely what very old fine wine becomes over time.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.

Categories
Learn

Can you invest in fortified wine? Port, Sherry and Madeira explained

  • Fortified wine covers Port, Sherry and Madeira, three categories that share one technique but create scarcity in entirely different ways.
  • You can invest in fortified wine, though only Port has a published index, which keeps most holdings small and slow to sell.
  • Collectable value rests on bottles that cannot be remade: fixed vintage declarations, drawn-down soleras and aged Madeira that is still drinkable.

Fortified wine produces the longest-lived bottles in the wine trade and the least understood by investors. Port, Sherry and Madeira share one technique, the addition of grape spirit, but they are made differently, age differently and trade differently. This guide explains how each one works, sets out the differences that matter, and shows why fortified wine tends to occupy a small corner of a portfolio while producing some of the most collectable bottles in existence.

What fortified wine is, and why three names dominate

Fortified wine is wine with grape spirit added to it. The addition raises alcohol content, usually to somewhere between 15% and 22%, and it transforms how long the wine survives. That longevity is what makes the category interesting to a collector, because it is the reason genuinely old bottles are available to buy at all.

The practice began as preservation. Wine shipped from Portugal and Spain to northern Europe spoiled on the voyage, and added spirit kept it drinkable. Producers then found the additions improved the wine rather than merely protecting it, and three regions built distinct traditions around the technique.

  • Port comes from the Douro valley in northern Portugal. Producers add spirit part-way through fermentation, which stops the yeast and leaves natural grape sugar in the wine.
  • Sherry comes from Jerez in southern Spain. Producers ferment the wine dry first and fortify it afterwards, so the base wine is nothing like Port.
  • Madeira comes from the Atlantic island of the same name. Producers heat the wine deliberately, which sounds destructive and is the reason Madeira outlives everything else.

Those three account for almost all collector interest. Marsala, Vermouth and Commandaria use the same technique, but they trade in negligible volumes and have no established secondary market.

Port depends on the vintage a house chooses to declare

Port has the simplest structure of the three, and that simplicity is why it dominates trading. In years a house judges exceptional, it declares a vintage, meaning it bottles that year on its own rather than blending it away. Declarations happen roughly three times a decade.

The decision fixes supply permanently. Once a house has declared and bottled, no more of that vintage can ever exist, and every bottle opened reduces what remains. Producers declared 2016 and 2017 back to back, an unusual sequence, then declared nothing generally until 2024.

Five houses carry most of the trade: Dow, Fonseca, Graham, Taylor and Warre. Below declared vintages sit Single Quinta Ports, made from one estate in undeclared years and priced lower, and Late Bottled Vintage Port, made in commercial volumes for early drinking. Only the first two have collector relevance.

Aged tawny and colheita Ports sit outside that hierarchy. Producers mature them in cask until they are ready to drink, so they arrive at maturity on release and appeal to drinkers rather than to collectors.

Sherry is aged in a solera, so it has no vintage

Sherry uses a system that makes vintage dating impossible, and that single fact explains most of its market behaviour. A solera is a stack of barrels holding wine of different ages. Producers draw a portion from the oldest barrels, top those up from the next oldest, and repeat down the chain, so every bottle blends many years together.

The result is an average age rather than a date. Two certifications mark the oldest stock: VOS (Vinum Optimum Signatum) for an average age of at least 20 years, and VORS (Vinum Optimum Rare Signatum) for at least 30 (Consejo Regulador). The Consejo verifies both through laboratory analysis and tasting assessment.

Styles vary more widely than in Port or Madeira. Fino and Manzanilla age beneath a film of yeast called flor, which keeps them pale and dry. Amontillado, Oloroso and Palo Cortado age in contact with air and darken as they do. Pedro Ximenez is sweet and intensely concentrated. Only the oxidative styles and Pedro Ximenez carry VOS or VORS certification, which is where collector attention sits.

For a buyer, this creates a comparison problem. A collector can compare two bottles of 1994 Taylor directly. Comparing two VORS Olorosos means comparing two blends nobody can decompose, from bodegas whose reputations differ. Old solera stock is scarce since producers cannot replace what they draw down, but scarcity without comparability makes pricing difficult.

Madeira is heated on purpose and survives almost indefinitely

Madeira’s production would ruin any other wine. Producers either warm it in heated tanks for months, a process called estufagem, or leave it in casks in warm lofts for years or decades, known as canteiro. Both methods expose the wine to heat and oxygen.

Oxidation is what normally kills wine. Madeira has already been through it, so little remains for time to damage. Bottles from the eighteenth century still open sound, which is true of no other wine category.

Grape variety signals style, and older bottles are usually labelled by grape rather than by house style. Sercial is the driest, followed by Verdelho, Bual and Malmsey, which is the sweetest. Tinta Negra accounts for most volume production. Collector attention concentrates on the four noble varieties.

That produces an unusual market. Antique Madeira exists in drinkable condition in a way old Bordeaux does not, so a collector buying a very old bottle can expect it to be alive. Colheita Madeira, from a single year and aged at least five, and vintage Madeira, aged at least twenty, offer the same durability at far lower prices.

How long can fortified wine age

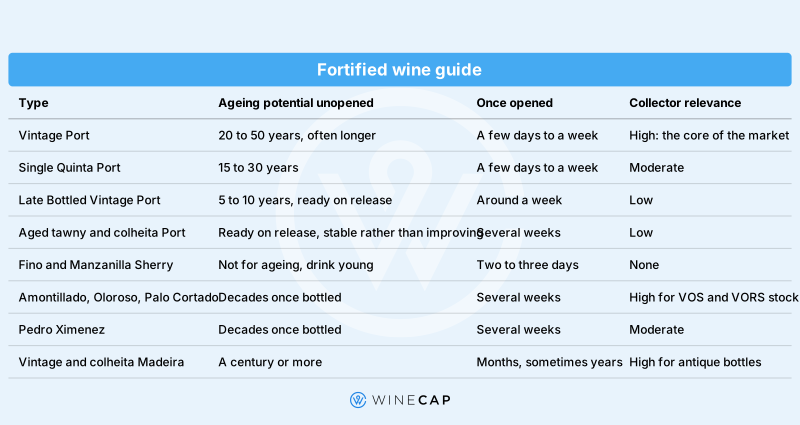
Ageing potential varies more across these three categories than anywhere else in wine. The spans below matter to a buyer for two reasons: they determine how long a bottle can be held before selling, and how quickly it has to be drunk once the cork comes out.

Fortified wine

How fortified wines create scarcity

Scarcity is the common thread, and each category manufactures it differently. Knowing which mechanism applies tells a buyer more than any general view on fortified wine does.

  • Port restricts supply by decision. A house declares or it does not, and once bottled the quantity is fixed. Scarcity is set at the outset and erodes as bottles are drunk.
  • Sherry restricts supply by consumption of the solera. Old stock disappears into bottles and cannot be recreated, because recreating it would require the decades to run again.
  • Madeira restricts supply by survival. Antique bottles are scarce because few were kept rather than because few were made, and the wine’s durability means the survivors remain viable.

Those mechanisms produce different market behaviour. Port has dates, named houses and comparable sales, which supports a functioning secondary market. Sherry has certified ages and reputations, which supports specialist trading. Madeira’s antique tier behaves like an antiques market, moving when a cellar comes to auction rather than with wine prices generally.

Why fortified wine stays a small part of a portfolio

Liquidity is the binding constraint across all three categories. Selling fine wine requires a buyer who wants that specific bottle, and fortified wine has far fewer of them than Bordeaux or Burgundy. Port is the only category with a published index. Liv-ex launched the Port 50 in October 2018, tracking the ten most recent vintages from the five main houses. 

Moreover, HMRC’s Capital Gains Manual states that the wasting-asset exemption, which covers assets with a predictable life of 50 years or less, would not apply to Port and other fortified wines given their long storage life (HMRC, CG76901). The longevity that makes these wines collectable is the reason they fall outside a treatment some still wines can rely on. Treatment depends on individual circumstances and may change, so take independent tax advice.

The collectable case rests on bottles that cannot be remade

Collector demand is where fortified wine looks strongest, and it comes from rarity rather than from market momentum. 

Results at the top of the Madeira market show what that rarity attracts. A bottle dated to around 1715 sold for roughly $39,000 in 2016, and a nineteenth-century Liberty Hall bottling reached close to $16,000 at Christie’s in 2018. These are selected examples from the very top of the market rather than representative Madeira prices.

Condition determines much of what a buyer will pay. Vintage Port is bottled unfiltered and throws heavy sediment, so undisturbed storage matters more here than in most categories. Original cases, intact capsules, legible labels and an unbroken bonded storage record all feed into price, and a bottle without documentation sells at a discount whatever the vintage.

How to buy fortified wine for the long term

Buying well matters more than timing here, because the exit can be slower than more liquid fine wines across all three categories. 

A sensible approach would be:

  • Start with declared vintage Port from one of the five main houses.
  • Treat Single Quinta Port and VORS Sherry as smaller positions.
  • Buy aged Madeira only where provenance and condition are documented.
  • Store everything in bond, with condition records and an unbroken storage history.
  • Take independent tax advice before assuming any particular treatment applies.

Fortified wine complements a core holding in Bordeaux, Burgundy or Champagne rather than substituting for any part of it.

What fortified wine offers

Fortified wine gives a collector access to something the rest of the wine world cannot supply: bottles that are genuinely old and genuinely drinkable. A nineteenth-century Madeira is not a curiosity kept for display. It works, which is why a small group of buyers pursues it regardless of what fine wine indices are doing.

What it asks in return is patience and effort. The research burden falls on the buyer, published pricing barely exists outside Port, tax treatment is less favourable than for some still wines, and selling takes time. Those costs are why fortified wine belongs at the edge of a portfolio rather than the centre, and also why its rarest bottles keep finding buyers.

FAQ: Fortified wine investment

What counts as fortified wine? 

Fortified wine is wine with grape spirit added, which raises alcohol to roughly 15% to 22% and greatly extends how long the bottle lasts. Port, Sherry and Madeira account for almost all collector interest, though Marsala, Vermouth and Commandaria use the same technique. Only the first three have a meaningful secondary market.

Can you invest in fortified wine? 

You can, though the market is small. Most buyers treat fortified wine as a collectable with a modest investment market attached rather than as a core holding. 

Which fortified wine is easiest to sell? 

Declared vintage Port from Dow, Fonseca, Graham, Taylor or Warre is the easiest, because those five houses carry most of the category’s secondary market activity and have comparable sales going back decades. Sherry and Madeira usually require a specialist merchant or an auction consignment, which can take months. Liquidity should shape position size before price does.

Do you pay capital gains tax on Port? 

HMRC’s Capital Gains Manual states that the wasting-asset exemption, which applies to assets with a predictable life of 50 years or less, would certainly not apply to Port and other fortified wines because of their long storage life. Gains may therefore fall within capital gains tax where some still wines would not. Treatment depends on your individual circumstances and may change, so take independent tax advice.

How long can fortified wine be kept? 

Vintage Port typically improves for several decades and lasts far longer in good storage. Madeira outlasts everything, with eighteenth-century bottles still opening sound, because its production already exposes the wine to heat and oxygen. Old Sherry drawn from a solera is similarly durable once bottled, though the bottling date matters rather than a vintage.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.

Categories
Learn

Sancerre and Loire Valley wine guide: Soils, top producers and vintages to know

  • Sancerre and Loire Valley wine quality is more dependent on the producer and soil than the vintage so site knowledge is essential.
  • Three soils divide the appellation: terres blanches gives the longest-lived wines, silex – the smoky character, caillottes – the light bottles meant for drinking young.
  • Most Sancerre is made to drink young: only a narrow group of Loire names, Clos Rougeard, Dagueneau, Edmond Vatan and Huet among them, trade actively.

Sancerre is the Loire Valley’s best-known wine, and also its most misunderstood. The name covers around 3,000 hectares of genuinely different soils, producing everything from simple bistro Sauvignon Blanc to wines that hold and improve for twenty or more years. This guide sets out what separates the two: how Sancerre tastes and why, the three soil types that drive quality, the producers who define the top tier, the vintages worth prioritising, and the neighbouring appellations that share the same limestone at a lower price. 

What is the Loire Valley known for, and what are its main wine regions?

The Loire is France’s longest river and its most stylistically varied wine region. It runs roughly 1,000 kilometres from the Massif Central to the Atlantic, and the vineyards along its final 400 kilometres produce dry white, sweet white, sparkling, rose and red wine in commercial quantity. No other French region covers that range. Around 70,000 hectares are under vine, which makes the Loire France’s third-largest appellation area and its largest producer of white wine.

Four broad zones divide it, and the grape changes as the river runs west:

  • Centre-Loire, the eastern end. Sancerre, Pouilly-Fume, Menetou-Salon, Quincy and Reuilly, all built on Sauvignon Blanc with a minority of Pinot Noir. This is where the region’s best-known wines come from.
  • Touraine, the middle. Vouvray and Montlouis for Chenin Blanc, Chinon and Bourgueil for Cabernet Franc, on tuffeau limestone.
  • Anjou-Saumur, further west. Savennieres for dry Chenin, Coteaux du Layon and Quarts de Chaume for sweet Chenin, Saumur-Champigny for Cabernet Franc, and the bulk of Cremant de Loire.
  • Pays Nantais, at the Atlantic mouth. Muscadet, made from Melon de Bourgogne on gneiss and schist.

That geographic spread matters practically. A buyer who searches on the region name alone will be shown wines with almost nothing in common beyond the river, which is the first reason Loire wine confuses newcomers.

What is Sancerre, and why does the name alone tell you so little?

Sancerre is a place, not a grape. The appellation sits at the eastern end of the Loire Valley, around 200 kilometres south of Paris and closer to Burgundy’s Chablis than to the Atlantic. It covers roughly 3,000 hectares across fourteen communes. White Sancerre comes from Sauvignon Blanc. Red and rose Sancerre come from Pinot Noir.

A buyer who knows only the name knows very little, because the appellation spans three distinct soil types that produce genuinely different wines. Those three soils explain most of the quality variation inside a single AOC:

  • Terres blanches, a Kimmeridgian clay-limestone marl found on the steepest western slopes. The same formation underlies Chablis. It ripens slowly, gives the fullest and most structured wines, and produces the appellation’s longest-lived bottles.
  • Caillottes, shallow limestone gravel over hard rock. It drains fast and warms early, giving lighter, more aromatic, fruit-forward wines that drink best within two or three years of release.
  • Silex, flint, concentrated around the eastern edge near the river. It gives the smoky, struck-match character many drinkers associate with the name, along with real cellaring capacity.

Village names carry the same information in shorthand. Chavignol, Bue, Verdigny, Menetreol and Sancerre town each have their own reputations. Chavignol holds the steepest slopes and the most sought-after sites, Les Monts Damnes and Cul de Beaujeu chief among them. Entry-level Sancerre from a negociant label, blended across communes and soils, rarely repeats what those sites deliver.

How to read a Sancerre label

A Sancerre label carries more information than most buyers use. French appellation law requires only the AOC name, the producer and the vintage, so everything beyond that is a voluntary signal, and voluntary signals cost the producer something to make.

Look first for a soil or site name. Words such as Silex, Les Monts Damnes, Cul de Beaujeu, Le Chene Marchand or Les Romains indicate a single vineyard or a specific soil type, and a producer only prints them when the wine justifies the narrower claim. A cuvee name without a place attached carries less weight.

Check next for the producer category. “Mis en bouteille au domaine” means estate-bottled from the grower’s own fruit. A negociant label, which buys grapes or finished wine from others, may still be good, but it blends across sites and loses the soil signal entirely. Organic and biodynamic certification marks, AB and Demeter, appear increasingly often and correlate with the appellation’s more ambitious growers.

Sancerre rouge and rose: The Pinot Noir side of the appellation

Sancerre made its reputation on red wine, not white. Pinot Noir dominated the slopes until phylloxera destroyed the vineyards in the late nineteenth century, and growers replanted largely to Sauvignon Blanc because it recovered faster on the limestone. Red and rose now account for a minority of production, but the best examples repay attention precisely because so few buyers look for them.

Sancerre rouge is light, high-toned Pinot Noir with red-fruit aromatics and firm acidity, closer in weight to a village-level Burgundy than to anything from the Cote de Nuits. Vacheron’s reds are the appellation’s benchmark and command prices well above the white wines from many of its neighbours. Pinard and Delaporte also make serious reds.

Sancerre rose, made by direct press or short maceration, is a small category and mostly drinks young. It rarely leaves France in volume.

What does Sancerre taste like, and how does it differ from other Sauvignon Blanc?

Sancerre tastes drier, tighter and less overtly fruity than most New World Sauvignon Blanc. The reference points are citrus, white flowers, wet stone, grapefruit pith and a faint smokiness on flinty sites. Cool-climate ripening keeps acidity high, and most producers avoid malolactic fermentation (a secondary conversion that softens acidity into a rounder texture), which preserves that tension. Very few use new oak.

The comparison buyers ask about most often is Marlborough. Three differences matter:

  • Aromatics: New Zealand Sauvignon Blanc leads with passion fruit, gooseberry and cut grass, driven by warmer sites and thiol-forward winemaking. Sancerre leads with citrus and mineral character.
  • Sweetness: Many commercial Marlborough wines carry a few grams of residual sugar. Sancerre is almost always bone dry.
  • Structure: Sancerre rests on acidity and texture rather than aroma, which is why it ages and most Marlborough does not.

Chablis is the other frequent comparison, and the confusion is understandable. Both sit on Kimmeridgian limestone, and both give lean, mineral, unoaked whites with high acidity. The difference is the grape: Chablis is Chardonnay, Sancerre is Sauvignon Blanc. Chablis tends to show citrus and oyster shell, Sancerre a sharper, more herbal edge.

What food goes with Sancerre, and how should you serve it?

Sancerre has one classic pairing above all others, and it comes from inside the appellation. Crottin de Chavignol, the small aged goat cheese made in the Chavignol commune, is a protected AOP product in its own right, and the match with a flinty Sancerre from the same slopes is the reference example of local pairing logic. Goat cheese in general works for the same reason: high acidity cuts through lactic richness.

Beyond that, the wine suits oysters, shellfish, crab, ceviche and sushi, where its salinity and acid do the same job as a squeeze of lemon. It handles asparagus and artichoke, both of which defeat most wines. Herb-driven dishes, particularly anything with dill, chervil, tarragon or sorrel, echo the wine’s own aromatics. Sancerre rouge suits charcuterie, roast poultry and river fish.

Serve white Sancerre at 8 to 10 degrees Celsius. Straight from a fridge is too cold and mutes the aromatics. Older single-vineyard bottlings from terres blanches or silex benefit from a little more warmth, and some reward decanting for twenty minutes. Serve Sancerre rouge at cellar temperature, around 14 to 16 degrees.

Why is Sancerre becoming more expensive?

Sancerre’s pricing reflects a fixed supply meeting global brand recognition. The appellation cannot expand. The INAO fixed its boundaries decades ago, growers identified the best slopes long before that, and vineyard land inside them changes hands rarely and expensively. Demand, meanwhile, comes from restaurant wine lists worldwide, where Sancerre functions as a default by-the-glass white in a way few French appellations manage.

Weather has tightened supply further. Frost and mildew have cut Centre-Loire yields repeatedly over the past decade, with 2021 particularly severe. Trade reporting has put wholesale prices for the appellation on a steep upward path, citing one producer’s case price rising from around 144 to 240 US dollars over roughly a decade, and some sommeliers dropping the AOC from lists over price-to-quality concerns (PUNCH, 2023).

That criticism deserves to be taken seriously, and it points at the real problem. The price rise applies across the appellation, including to wines from flat, warm sites that never justified it. A buyer paying a premium for the name alone gets nothing for the premium.

The practical answer is to buy by producer and site. Two bottles at the same price can differ enormously in structure and ageing potential, and the label tells you which is which if you know what to look for. It also pays to look one appellation sideways, where the same limestone sells for materially less under a name the export market has not yet bid up.

The producers that define Sancerre today

Producer selection matters more in Sancerre than in almost any comparable French appellation. A short list of estates consistently makes wine that critics and the secondary market treat differently from the rest. These are selected examples rather than a complete or representative list.

  • Domaine Vacheron, based in Sancerre town and farmed biodynamically (a method using organic practices plus lunar-cycle timing and preparations, without synthetic chemicals), sets the appellation’s quality benchmark across both colours.
  • Francois Cotat and the related Cotat family estates in Chavignol make small volumes of intensely mineral, age-worthy Sancerre that sells well above standard appellation pricing.
  • Domaine Edmond Vatan, whose Clos la Neore is the single most collected white Sancerre, and Domaine Gerard Boulay, also in Chavignol, both attract buyers who cellar rather than drink on release.
  • Alphonse Mellot and Lucien Crochet are the larger, longer-established houses that built Sancerre’s export reputation and still set the standard for quality at volume.
  • Domaine Vincent Pinard, Claude Riffault, Delaporte and Henri Bourgeois combine consistency with genuine site expression, and are the most straightforward names to buy without chasing allocations.

Henri Bourgeois deserves a specific mention for scale and continuity. The family has made wine across ten generations and remains one of the appellation’s largest quality-focused producers, which gives buyers a dependable route into serious Sancerre. Smaller organically and biodynamically farmed estates, Domaine Fouassier in Bue among them, have built strong critical followings over the past decade. The quality base is widening rather than sitting still around the same half-dozen names.

How long does Sancerre age?

Serious Sancerre ages far longer than most drinkers expect. The common assumption is two to three years, and for caillottes-driven wines from warm, low-lying plots that is accurate. Wines from terres blanches or silex sites, made by the producers named above, routinely improve for eight to ten years. The best go well beyond that.

Three factors drive it. Low pH gives the acid backbone. Kimmeridgian marl slows ripening and builds structure. The widespread avoidance of malolactic fermentation preserves both. Jamie Goode’s tasting of Henri Bourgeois Les Monts Damnes across the 1996, 2006 and 2015 vintages remains the most-cited technical demonstration that top Sancerre can hold for twenty years or more.

Mature Sancerre changes character rather than simply softening. The primary citrus and herb notes recede, and honey, beeswax, dried orchard fruit and a distinct smokiness come forward. The wine surprises anyone who expects an older version of what they tasted on release.

Red Sancerre and the Loire’s Cabernet Franc appellations age on a different and often longer curve. Top Chinon, Bourgueil and Saumur-Champigny from a strong vintage can develop for fifteen years or more under proper cellaring conditions.

Sancerre vs Pouilly-Fume vs Menetou-Salon: The satellite appellations

Across the Loire river from Sancerre sits Pouilly-Fume, a Sauvignon Blanc appellation on comparable Kimmeridgian and flint soils. The wines are equally serious, and tasters typically describe them as smokier and broader than Sancerre, though producer style matters more than the appellation line. The late Didier Dagueneau built the modern reputation for concentration and ageing potential. The domaine, now run by his son Louis-Benjamin, commands prices well above typical Pouilly-Fume for its Silex and Pur Sang cuvees. Baron Patrick de Ladoucette’s Chateau du Nozet is the appellation’s other widely recognised name and a more accessible route into the same soils.

Further east, several smaller appellations sit on the same limestone band without carrying the Sancerre name premium:

  • Menetou-Salon, immediately south-west of Sancerre, produces Sauvignon Blanc from near-identical Kimmeridgian soils and sells at a consistent discount for comparable quality. A minority of the appellation is planted to Pinot Noir. 
  • Quincy, planted on sand and gravel rather than limestone, gives a rounder, softer style and remains among the least expensive routes into Centre-Loire Sauvignon Blanc.
  • Reuilly produces white, red and a distinctive Pinot Gris rose, and sits further from the main export routes. Sommeliers increasingly list both Quincy and Reuilly as genuine substitutes.

For a buyer rather than a collector, the appeal of these appellations is straightforward: exposure to the same terroir at a lower entry price, without concentrating an entire allocation in one increasingly expensive name.

One caution applies. These appellations trade thinly even by Loire standards, and a discount that exists because a name is unfashionable stays a discount for as long as the name stays unfashionable. Menetou-Salon has been described as the next Sancerre for two decades without becoming it. The case for buying these wines rests on what they deliver in the glass against what they cost, not on an expectation that the market will eventually reprice them.

Vouvray, Savennieres and Muscadet extend the Loire well beyond Sauvignon Blanc

The Loire has the widest stylistic range of any French wine region, and Sancerre represents only its eastern edge. Follow the river west and the grape changes twice.

The middle Loire belongs to Chenin Blanc, a white grape capable of dry, off-dry, sparkling and sweet botrytis-affected styles from the same vineyard depending on the vintage. Vouvray grows it on tuffeau, the soft limestone that also gives the region its cave dwellings. Savennieres, further west on schist, makes only dry Chenin, and makes it in a firm, structured style that often needs five years before it opens.

At the Loire’s Atlantic end sits Muscadet. The trade long dismissed it as a simple seafood wine made from Melon de Bourgogne, and that reputation has shifted genuinely over the past fifteen years.

  • Domaine Huet defines Vouvray. Biodynamically farmed since the 1980s, it sets the benchmark for age-worthy Chenin, with bottles from strong vintages drinking well after twenty or thirty years. Domaine du Clos Naudin and Francois Pinon sit alongside it.
  • Nicolas Joly’s Coulee de Serrant is Savennieres’ most famous holding, a monopole and one of very few single-estate appellations in France. Domaine des Baumard offers a more conventional route in.
  • Domaine de la Pepiere and Domaine Luneau-Papin lead Muscadet, where the best wines now come from named crus such as Clisson, Gorges and Le Pallet and spend extended time sur lie (on the spent yeast lees, a technique that adds texture and complexity before bottling). Recent La Place releases have brought Luneau-Papin to a wider international market.

All three categories remain priced well below Sancerre and Pouilly-Fume, despite comparable critical recognition among specialists.

Sweet and sparkling Loire wines are the region’s most overlooked categories

The Loire makes two categories that almost no buyer outside France thinks of first, and both offer better value than the dry whites that carry the region’s name.

Sweet Chenin Blanc from Anjou is the more serious of the two. Botrytis (noble rot, a fungus that dehydrates ripe grapes and concentrates sugar and acid) develops reliably in the Layon valley, and the resulting wines balance high sugar against Chenin’s naturally piercing acidity. That balance is what lets them last. Bottles from strong vintages drink well at fifty years and beyond, which few sweet wines outside Sauternes and Tokaji manage.

Sparkling wine is the volume category. Cremant de Loire and sparkling Vouvray are made by the traditional method, the same second-fermentation-in-bottle process used in Champagne, and sell for a fraction of Champagne prices.

  • Quarts de Chaume holds the Loire’s only Grand Cru status, awarded in 2011, and covers barely 30 hectares. Bonnezeaux and the broader Coteaux du Layon sit alongside it.
  • Domaine des Baumard and Chateau Pierre-Bise are the reference names for sweet Anjou, with Domaine Huet producing outstanding moelleux Vouvray in botrytis-friendly years.

The Loire’s red wines built a collector following around Cabernet Franc

The middle stretch of the valley produces some of France’s most distinctive Cabernet Franc, around Chinon, Bourgueil, Saint-Nicolas-de-Bourgueil and Saumur-Champigny. These wines sit on the same clay-limestone slopes that define quality on Bordeaux’s Right Bank, where Cabernet Franc plays a supporting role. In the Loire it stands alone, giving graphite, red fruit, crushed herb and a distinct pencil-shaving character, with firm tannin and moderate alcohol.

  • Domaine Bernard Baudry in Chinon ranks among the variety’s masters, alongside Charles Joguet, Couly-Dutheil, Olga Raffault and Philippe Alliet.
  • Domaine Catherine and Pierre Breton in Bourgueil helped drive the region’s move toward biodynamic and low-intervention winemaking. Yannick Amirault in neighbouring Saint-Nicolas-de-Bourgueil makes some of its most structured wines.
  • Clos Rougeard in Saumur-Champigny is the cult estate that put the appellation on the collector’s map, alongside Thierry Germain’s biodynamic Domaine des Roches Neuves and the more widely available Domaine Filliatreau.

Clos Rougeard illustrates what happens when a Loire red reaches genuine cult status. Production is small, demand runs ahead of supply, and secondary market prices reflect a scarcity dynamic more often associated with top Burgundy than with the Loire.

Is Sancerre a good investment? What the auction record shows

Sancerre as an appellation is not an investment category, and buyers should be clear about that before anything else. Drinkers consume the overwhelming majority within three years of release. It sells through retail rather than the secondary market, and it has no meaningful resale route.

A narrow tier does trades mostly at auction. In 2025, 58.5% of Loire wine traded by volume was under ten years old (iDealwine, reported June 2026), which indicates a young secondary market rather than an established one with vintage depth. Moreover, a rising Loire auction line reflects a small category growing from a small base.

Anyone weighing the Loire against a regulated asset should also note that wine investment is not regulated in the UK. There is no Financial Conduct Authority oversight, and no recourse to the Financial Services Compensation Scheme or the Financial Ombudsman Service. Liquidity is the practical constraint. Loire trades happen through specialist merchants, auction and direct allocation rather than a continuously quoted market, which means longer holding periods and wider spreads than Bordeaux or Champagne. That is also why barely two dozen Loire wines appear in WineCap’s Wine Track database.

The gap between reputation and market recognition is the Loire’s defining feature

The Loire’s position is unusual among French regions. Its best producers make wine that specialists rate alongside far more expensive bottles from Burgundy and the Rhone, and yet the region has no benchmark index, thin auction depth and a secondary market dominated by wines under ten years old. 

What follows is a straightforward discipline. Buy the producer and the site, not the appellation. Treat Sancerre as a drinking category with a handful of exceptions rather than an asset class with a broad base. Look one appellation beyond the famous name, where Menetou-Salon, Quincy and Saumur offer the same soils at a fraction of the price. Expect to hold anything bought with resale in mind for longer than an equivalent Bordeaux or Champagne, and to sell it through a merchant relationship rather than a screen.

FAQ: Sancerre and Loire Valley wine

What does Sancerre taste like?

Dry, high-acid and mineral, with citrus, white flowers, grapefruit pith and wet stone rather than the tropical fruit of New World Sauvignon Blanc. Wines from flinty silex soils show a smoky, struck-match character. Almost all Sancerre is bone dry and unoaked. Serve it at 8 to 10 degrees Celsius, not straight from the fridge.

How long does Sancerre age?

Sancerre from terres blanches or silex soils, made by a top producer, improves for eight to ten years and sometimes considerably longer. Wines from lighter caillottes soils are built for two to three years. Entry-level negociant Sancerre rarely rewards cellaring.

What is the difference between Sancerre and Pouilly-Fume?

Both are Sauvignon Blanc from Kimmeridgian and flint soils on opposite banks of the Loire, and the quality ceiling is comparable. Tasters typically describe Pouilly-Fume as smokier and broader, Sancerre as tighter and more citrus-driven, though producer style matters more than the appellation line. Pouilly-Fume’s most collected wines come from Domaine Didier Dagueneau.

Is bonded storage necessary for Loire wine bought for resale?

Yes, for any bottle bought with resale in mind. A bonded warehouse holds wine without UK duty and VAT having been paid, provided it stays in bond, which preserves provenance and avoids upfront tax charges. Both matter to a future buyer assessing condition and history. Tax treatment depends on individual circumstances and may change, so take independent tax advice.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.

Categories
Learn

The 2000 vintage in Bordeaux, Burgundy and beyond

  • Left Bank Bordeaux is the standout fine wine region of the 2000 vintage and one of the finest of the modern era, with wines that are only now reaching their drinking peak.
  • Bordeaux 2000 consistently trades above comparable quality years, driven by the date as much as the wine.
  • 2000 was not a universal success, with Burgundy reds, California Cabernet, and Germany all falling short.

In 2026, the 2000 vintage is three stories in one. The first is a quality story: Left Bank Bordeaux, Piedmont, and Port all delivered wines of genuine distinction. The second is a marketing story: the cultural significance of the number on the label attracted buyers motivated by the date as much as by the wine. Third is the question “is this vintage still investable” to which the answer is yes, but with some caveats. Twenty-five years on, the millennium premium remains embedded in prices, particularly in Bordeaux. Separating genuine quality from commercial cachet is the starting point for any investor approaching this vintage today.

How good was the 2000 vintage?

Vintages give investors a probability framework, not a guarantee. A strong growing season raises the quality floor across a region and improves the odds of success for individual wines. 2000 produced some of the finest Left Bank Bordeaux of the modern era while delivering disappointing Burgundy reds, weak German Riesling, and compromised California Cabernet. That spread is wider than most celebrated years. The aggregate score for a vintage still matters; individual wine selection always matters more.

What made 2000 a great growing season and where

The late oenologist Denis Dubourdieu identified four conditions that reliably produce a great Bordeaux vintage. The same criteria, adapted for local conditions, apply across virtually every fine wine region in the world.

  • Early and rapid flowering, producing even berry development across the crop
  • Gradual water stress in July, slowing vine growth and concentrating the fruit
  • Warm, dry conditions through August and September, building phenolic (flavour and tannin) ripeness without heat damage
  • A dry harvest period, giving producers the flexibility to pick at optimal maturity

Bordeaux broadly satisfied all four criteria in 2000. The season was warm and gradual, building concentration without the heat extremes that damaged 2003.

Two regions illustrate what happens when the criteria are not met. California’s North Coast failed criterion four: a cold, rainy October disrupted harvest and prevented full phenolic ripeness for late-ripening red varieties. Robert Parker scored North Coast Cabernet just 78 points for 2000, the lowest of any major region in his vintage chart.

Burgundy failed criteria three and four. Prolonged rain and rot during August and the harvest period produced a large, dilute crop across the Cote de Nuits. The conditions that generate precision and concentration in Pinot Noir were simply not present.

Bordeaux 2000: A Left Bank classic

Bordeaux 2000 is, above all, a red wine story. The Left Bank appellations (Pauillac, Saint-Julien, Saint-Estephe, Margaux, and Pessac-Leognan) produced wines of exceptional concentration and structural precision, although they have been eclipsed in terms of outright quality since, at the time they were a very real highpoint. Contemporary critics such as Robert Parker and Wine Enthusiast magazine scored the principal Medoc appellations between 96 and 97 points, with Wine Enthusiast also awarding Pomerol 97 points. 

2000 bordeaux table

Pavie is perhaps the most debated wine of the vintage. Under Gerard Perse, who acquired the property in 1998, the 2000 was made in a highly extracted style that divided critics. However, even critics like Neal Martin, who question how it interprets the terroir of Saint-Emilion have been fairly uniform in their praise. For investors, that score is the relevant input, whatever view one takes on the stylistic question.

Chateau Mouton Rothschild 2000 occupies a special position in the vintage, as its scores didn’t quite meet up to the level of its First Growth peers but it was the first classified growth Bordeaux to use a fully gold-embossed bottle, marking the millennium. That presentation set a template for others and transformed the bottle into a collector object in its own right. Mouton 2000 prices, around £15,000 a case today, have risen 800% since release with large formats doing even better, often trading at a 20-30% premium over cases.

Other examples of similar bottlings include Angelus 2012, Margaux 2015, Cos d’Estournel 2020, Leoville Poyferre 2020 and Gruaud Larose 2025. None have done so with quite the same panache as Mouton Rothschild and only Angelus has seen similar performance.

The most important point for investors is timing. These wines are only now entering the best part of their drinking windows. For the finest Left Bank examples, that window extends comfortably to 2035 and beyond. Owning them at this stage means genuine pleasure ahead as well as potential value.

The millennium premium: Bordeaux 2000 vs 2005

In this instance in particular the vintage on the label carries price weight that quality metrics alone do not explain. Bordeaux 2000 consistently trades above comparable quality years. The clearest example is when comparing 2000 to the 2005 vintage. 

Both are outstanding vintages, yet across a basket of Bordeaux First Growth, Second Growths, St Emilion Grand Cru Classe A’s and top Pomerol 2000 trades at nearly 15% higher prices, and across 25 wines in only 3 cases is 2005 more costly (Haut Brion, Ducru Beaucaillou and Lascombes). 

Burgundy 2000: a vintage to approach with caution

Burgundy’s red 2000s are not a collector vintage at the broad level. Rain and rot during August and the harvest period produced a dilute crop across the Cote de Nuits. Parker scored Cote de Nuits reds at 87 points; Wine Enthusiast rated them 84. In a region where the finest years set the benchmark, 2000 falls well short.

White Burgundy fared somewhat better. The complicating factor is what is now recognised as the pre-mox era: a period from roughly the mid-1990s to the mid-2000s during which premature oxidation (a fault caused by insufficient oxygen protection, often linked to poor-quality cork) affected a significant proportion of white Burgundy production, turning wines brown and flat well before their intended drinking windows. At 25 years old, a meaningful number of white Burgundy 2000s will have oxidised. 

Italy 2000 and Vintage Port 2000

Piedmont 2000 was another strong year in a consecutive run of excellent vintages. The finest examples are in a sweet spot now: complex and evolved, with years of life remaining. Some late October rains affected producers who left Nebbiolo hanging longest, so producer selection matters. These wines, unlike their Bordeaux equivalents, carry no Millennial price premium, which makes the relative value case compelling.

Tuscany in 2000 was more variable. An extremely hot August raised concerns about overripeness, and not every producer navigated the conditions well. Top producers made good to very good wines, but the vintage does not offer the broad quality floor that justifies buying across the appellation.

Port 2000 was exceptional and widely declared. Yields fell by as much as 40%, concentrating the remaining fruit. Port remains a niche investment category relative to Italy, but collectors with an interest in the style have a strong reference point in this vintage.

Champagne 2000: Cristal, Dom Perignon and Krug

Unsettled growing conditions led many major houses to decide against a wine for the 2000 vintage. Yet a significant number of prestigious producers did release their tetes de cuvee (prestige flagship cuvees), signalling genuine confidence in their individual harvest results. These included:

  • Dom Perignon (and Dom Perignon Rose)
  • Louis Roederer Cristal (and Cristal Rose)
  • Krug
  • Taittinger Comtes de Champagne
  • Bollinger Vieilles Vignes Francaises and Grande Annee
  • Pol Roger Sir Winston Churchill
  • Billecart-Salmon Nicolas Francois Billecart
  • Philipponnat Clos des Goisses
  • Lanson Noble Cuvee

Many of these have been considerable investment successes with the Millennial date amplifying demand for wines that stood on its own quality merits. For instance, Dom Perignon 2000 has risen 200% since release. Cristal has been the greatest success with prices up 430% since release in 2007.

2000 at 25: Rarity, drinking windows, and what to buy now

Twenty-five years after the harvest, the finest 2000 wines are only now finding their stride. Left Bank Bordeaux at this age is not in comfortable decline. For the greatest examples, the drinking window runs from now to 2035 and well beyond. These bottles carry genuine pleasure ahead of them, which adds secondary market support as serious collectors seek access to mature, well-stored examples.

The Millennial premium is not fading. Bordeaux 2000 continues to trade above comparable quality years, sustained by collector demand the label independently generates. For those considering entry, careful comparison against adjacent vintages remains prudent.

Age creates its own requirements. At 25 years, provenance and condition are paramount. Capsule integrity, label condition, and documented storage history all matter: buyers discount heavily at auction for anything unverifiable. Large formats (magnums and double magnums) merit attention here. They age more slowly, remain at peak condition for longer, and command a growing premium as they become increasingly scarce.

The investment case for 2000 now concentrates at the very top. These are wines where provenance, critical track record, and structural integrity give genuine confidence in another two decades of development. Liquidity will diminish as bottles are consumed. The counterweight is rarity: a case of Left Bank Bordeaux 2000 in 2035 or 2045 will be a fundamentally different object from what it is today.

FAQ: 2000 vintage wine investment

Is 2000 Bordeaux still worth buying at current prices?

The quality case for 2000 Left Bank Bordeaux remains intact: these are outstanding wines now entering their drinking peaks, with a long window ahead. The price question is more nuanced: Bordeaux 2000 trades at a premium to comparable quality years but that premium appears durable.

Which wines from the 2000 vintage have the strongest investment case?

Within Bordeaux, the strongest case is for the great Left Bank estates where critical scores are unambiguous and drinking windows remain long. In Italy, the finest Barolos represent genuine quality without the Millennial price premium. In Champagne the prestige cuvees are the core investable wines, although their drinking windows will not be as long as Bordeaux.

How important is provenance when buying 2000 wines?

Provenance is critical at this age. Twenty-five years of storage create risk: heat damage, inconsistent cellaring, and poor handling all affect quality significantly. A verifiable storage record in bond reduces that risk substantially.

Are large formats worth the premium for 2000 wines?

Yes, for long-term holders. Magnums and double magnums age more slowly than standard bottles, meaning the wine remains at peak condition for longer. At auction, magnum premiums for great vintages tend to expand as rarity increases.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.

Categories
Learn

What does Grand Cru mean? A guide to Europe’s top wine classification

  • Grand Cru does not have one universal meaning: in Burgundy and Alsace it identifies a vineyard, in Champagne a village, and in Bordeaux and Saint-Emilion a classified estate.
  • Burgundy’s 33 Grand Cru vineyards have remained unchanged for more than a century, while classifications such as Saint-Emilion are reviewed approximately every decade.
  • Understanding what has been classified – the land, the village or the producer – is the key to understanding quality, scarcity and long-term collectability.

Grand Cru is the most overused term in fine wine and the least understood. Five separate European systems use it to mean five different things: a plot of land, a village, or a producer’s estate. This guide explains what the label actually certifies in each major region, how permanent that status is, and what the underlying mechanism means for an investor deciding where scarcity is real and where it might be redrawn at the next review.

Grand Cru means five different things, not one

Grand Cru is not a single European standard. It refers to five separate classification mechanisms, each built around a different unit, a plot of land, a village boundary, or a producer’s estate, and each carrying a different risk profile. Burgundy and Alsace rank the vineyard itself, a classification that rarely moves once drawn. Champagne rates the village where the grapes are grown. Bordeaux and its satellite appellation Saint-Emilion classify the producer, a decision that can be revisited and, in Saint-Emilion’s case, contested loudly enough to make industry headlines.

The distinction shapes three things an investor should price before buying: how much competition exists at the top of the pyramid, how permanent that scarcity actually is, and how much authority sits with an independent geological record versus a producers’ committee. This guide works through each system region by region, then closes with what the mechanism itself signals about portfolio risk.

Burgundy ranks the vineyard, and the ranking rarely changes

Burgundy’s classification grades a specific plot of ground, not a producer or a brand. Only 33 vineyards across the Cote d’Or and Chablis carry Grand Cru status, a group representing roughly 1.5% of the region’s total vineyard area. Below Grand Cru sit Premier Cru vineyards, then village appellations, then regional Bourgogne wines, each tier commanding a different price for grapes grown metres apart.

However, while these tiers create a clear hierarchy, the pricing order is not necessarily rigid. Grand Cru wines generally command the highest prices, yet producer reputation can outweigh classification: the most sought-after Premier Crus, such as Cros Parantoux, and wines from producers including Domaine Leroy can cost more than Grand Crus from less celebrated growers. There is also considerable variation within large, fragmented Grand Crus such as Clos de Vougeot and Clos de la Roche, where numerous producers farm different parcels.

For investors, Burgundy’s system has three important implications:

  • Fixed geography: The 33 Grand Cru appellations are not subject to periodic committee review, making their status considerably more durable than classifications that are regularly revised.
  • Producer remains decisive: Because the system classifies land rather than winemaking, wines from the same Grand Cru can differ sharply in quality, reputation, availability and price.
  • Classification tiers overlap: Grand Cru establishes the highest level of the appellation hierarchy, but it does not guarantee that every Grand Cru will be more valuable or collectible than every Premier Cru. Producer selection and parcel quality can matter more than the words on the label.

Champagne’s Grand Cru system ranks the village

Champagne’s Cru system operates one level up from Burgundy’s, rating entire communes rather than individual plots. That distinction matters because a Grand Cru Champagne is typically a blend sourced from growers across a village rather than fruit from a single walled parcel, which changes how scarcity gets manufactured in the first place.

The echelle des crus (scale of growths), formalised in 1919, scores every one of Champagne’s 321 producing villages on an 80 to 100 percent scale. Only 17 villages reach the full 100 percent and may use the term Grand Cru: nine in the Montagne de Reims, six in the Cote des Blancs, and two in the Vallee de la Marne. Villages such as Cramant, Avize, and Oger anchor the Chardonnay end of that list, while Ambonnay, Bouzy, and Verzenay anchor the Pinot Noir end, a split that shapes which houses source from which commune. A further 44 villages fall into the 90 to 99 percent Premier Cru band.

The scale originally set the price growers were paid per kilogram of grapes, with Grand Cru growers receiving the full regional benchmark and lower-rated villages receiving a discounted percentage. EU competition rules forced the fixed-pricing mechanism to be abandoned in 2004, but the village rankings survived and still carry weight with buyers and houses alike.

Because Grand Cru status sits at village level, prestige cuvees narrow the funnel further. Houses such as Krug, Salon, and Louis Roederer draw fruit from specific parcels within Grand Cru villages like Ambonnay, Bouzy, and Le Mesnil-sur-Oger, and it is that narrower sourcing, not the village label alone, that underpins secondary market demand for named cuvees.

Bordeaux and Saint-Emilion classify the producer

Bordeaux took a different approach entirely: it ranked estates, not land. The 1855 Classification, commissioned by Napoleon III for the Paris Exposition Universelle, grouped Medoc and Sauternes chateaux into five tiers under the umbrella term Grand Cru Classe, with the top tier known as Premier Cru, or First Growth. This ranking has barely moved in 170 years, which is both its strength and its constraint.

Only five estates hold First Growth status: Lafite Rothschild, Margaux, Haut-Brion, Latour, and Mouton Rothschild. Mouton’s 1973 promotion from second growth remains the classification’s only amendment since 1855. That permanence gives First Growth pricing a stability few other assets can match, but it also means a chateau’s improvement in quality since 1855 has no formal mechanism for recognition.

Sauternes, classified in the same 1855 exercise, follows its own smaller hierarchy topped by Chateau d’Yquem, the only estate awarded Premier Cru Superieur, a rank held alone since 1855 and never extended to a second property. Saint-Emilion, a satellite appellation outside the 1855 system, built the opposite model. Its own Grand Cru Classe hierarchy is reviewed roughly every ten years by a dedicated committee, with the 2022 revision, the seventh since 1955, ranking 85 chateaux: two Premiers Grands Crus Classes A, 12 Premiers Grands Crus Classes, and 71 Grands Crus Classes.

The 2022 revision illustrates the volatility that periodic reclassification can introduce:

  • Chateau Figeac was promoted to the top tier, Premier Grand Cru Classe A, alongside Chateau Pavie, a move that materially reset market expectations for its pricing.
  • Three previous top-tier estates, Ausone, Cheval Blanc, and Angelus, withdrew from the process altogether, arguing the criteria had shifted toward marketing and tourism metrics rather than terroir and wine quality.
  • The dispute means Saint-Emilion’s most recognised names currently sit outside any classification at all, a status investors need to track independently rather than assume from the label.

Alsace Grand Cru: 51 sites still pricing below Burgundy’s whites

Alsace applies Burgundy’s vineyard model to an entirely different price bracket. Fifty-one named Grand Cru sites, recognised progressively since the appellation began in 1975 with 25 plots and expanded in 1983, 1992, and 2007 before formal codification in 2011, cover roughly 8 percent of Alsace’s vineyard area and 3 to 4 percent of its total production. For an investor, that scarcity ratio looks structurally similar to Burgundy, yet the category trades at a fraction of the price.

Only four grape varieties are permitted on Grand Cru sites: Riesling, Gewurztraminer, Pinot Gris, and Muscat, a restriction designed to protect the classification’s reputation by limiting it to varieties considered capable of expressing the underlying terroir. Producers such as Trimbach, Zind-Humbrecht, and Weinbach have built international followings from single Grand Cru sites like Schlossberg and Rangen, though secondary market volume remains thin compared with Burgundy or Champagne, and for some producers the late harvest designation “Venadage Tardive” is more significant than Grand Cru status.

The gap between Alsace Grand Cru pricing and comparable Burgundy white wine has drawn more collector attention in recent years, though it stays wide enough that the category reads as a long-horizon value position rather than a liquid trading instrument.

Germany’s Grosses Gewachs is the newest name to earn Grand Cru status

Germany has no legally protected Grand Cru term, so its top producers built one through a private association instead. The VDP, a growers’ body rather than a government authority, classifies vineyards into Grosse Lage and Erste Lage tiers, broadly equivalent to Grand Cru and Premier Cru. A dry wine from a Grosse Lage site, labelled Grosses Gewachs or GG, is the closest German equivalent to a French Grand Cru bottling. For an investor, the key difference is that VDP status rests on a producers’ association rather than state law, so its authority depends on continued industry buy-in rather than a fixed legal designation. Donnhoff and Egon Muller are the best known and most investable wines with this classification.

The criteria behind a GG label are stricter than most Grand Cru rules elsewhere in Europe:

  • Yields capped at 50 hectolitres per hectare, well below many French Grand Cru limits.
  • Hand harvesting required, with grapes assessed by a regional tasting panel before release is approved.
  • Minimum alcohol and maximum residual sugar thresholds, 11.5% in the Mosel and 12% elsewhere, with residual sugar capped below 9 grams per litre, designed to enforce a dry style consistent with the classification’s intent.

VDP member estates collectively sell around 39 million bottles a year, generating roughly 489 million euros in revenue. The modern four-tier system was formalised in 2012, following the association’s first classification attempt in 2002. Secondary market liquidity for GG wines still trails Burgundy and Bordeaux, but recognition has grown enough that specialist merchants now list GG bottlings as a distinct, trackable category rather than a curiosity.

What the classification mechanism means for investors

Understanding what a classification actually recognises – whether a vineyard, a village or a producer – helps explain where scarcity comes from and how stable that designation is likely to be over time.

Vineyard-based systems, such as Burgundy and Alsace, are rooted in geography. Because they classify the land itself, they have changed little over time and offer a relatively fixed framework for assessing scarcity.

Champagne’s village-based system is broader. Grand Cru status applies to entire communes rather than individual vineyards, giving producers greater flexibility in sourcing fruit while still limiting production to a small number of highly regarded villages.

Producer-based systems tell a different story. Bordeaux’s 1855 Classification has remained almost unchanged for more than 170 years, making it one of the most enduring hierachies in fine wine. Saint-Emilion, by contrast, is reviewed approximately every decade, meaning estates can be promoted, demoted or choose to withdraw from the process altogether. While these revisions do not automatically change a wine’s market value, they can influence collector perception and reinforce – or challenge – an estate’s position over the long term.

Germany’s VDP framework sits somewhere between the two. Its top vineyards are defined geographically, much like Burgundy’s Grand Crus, but the system is administered by a private growers’ association rather than enshrined in law.

For collectors and investors, these different approaches lead to three practical considerations:

  • Permanence supports confidence: Vineyard classifications in Burgundy and Alsace, along with Bordeaux’s 1855 Classification, have remained remarkably stable for generations, providing a consistent framework for assessing long-term scarcity.
  • Revisions deserve attention: Saint-Emilion’s periodic reclassification can alter the competitive landscape, particularly for estates seeking promotion or responding to changing criteria, even if market prices do not move immediately.
  • Recognition influences liquidity: Some of Europe’s most rigorous classification systems, such as Alsace Grand Cru and Germany’s Grosses Gewächs, remain less familiar to international buyers. That lower recognition can limit secondary market activity while also creating opportunities for collectors willing to look beyond the best-known regions.

Looking beyond the label

Grand Cru is one of the most recognisable terms in fine wine, but its meaning depends entirely on where the wine comes from. In Burgundy and Alsace, it identifies an exceptional vineyard. In Champagne, it refers to a village. In Bordeaux and Saint-Emilion, it recognises the estate.

For collectors and investors, understanding that distinction is more valuable than simply recognising the words on the label. A Grand Cru designation tells you what has been classified, but not necessarily why a wine commands its price, how scarce it is, or how it is likely to perform on the secondary market. Those questions depend on the producer, the vintage, market demand and, in some regions, the stability of the classification itself.

The best approach is to treat Grand Cru as a starting point rather than a conclusion. Once you understand what the classification represents, you can better judge the factors that ultimately determine a wine’s quality, collectability and long-term value.

FAQ: Grand Cru wine classifications

Is Grand Cru Burgundy a better investment than Bordeaux First Growth?

Neither category is straightforwardly better; they carry different risk profiles. Burgundy Grand Cru offers extreme scarcity, only 33 vineyards exist, but concentrated exposure to a handful of top producers, while Bordeaux First Growth status has remained fixed since 1855, with one exception in 1973, and offers deeper trading liquidity. The Liv-ex Burgundy 150 fell 4.8% in 2025 before recovering 2.2% from its low, showing that even the most prestigious vineyard classification does not eliminate price volatility.

How much capital does it take to start investing in Grand Cru wine?

Entry points vary enormously by region and producer. Alsace Grand Cru and German Grosses Gewachs bottlings can be accessed for a fraction of comparable Burgundy or Bordeaux pricing, often in the low hundreds of pounds per bottle, while top Burgundy Grand Cru labels such as Domaine de la Romanee-Conti trade in the tens of thousands of pounds per case. Most investors build exposure across tiers rather than concentrating capital in the most expensive names.

Can a Grand Cru classification be taken away?

It depends on the region. Burgundy and Alsace’s vineyard-based rankings have proven effectively permanent, while Saint-Emilion’s producer-based classification is reviewed roughly every ten years and can promote or demote estates, as happened when Ausone, Cheval Blanc, and Angelus withdrew from the 2022 process rather than accept the committee’s new criteria. Bordeaux’s 1855 list has changed only once, in 1973.

Does Grand Cru status guarantee secondary market liquidity?

No. Village-level Champagne Grand Cru and vineyard-level Burgundy Grand Cru both trade actively on the secondary market, but categories such as Alsace Grand Cru and German Grosses Gewachs remain comparatively thin, with fewer specialist merchants and less consistent auction volume. Liquidity tends to track how long a category has held international recognition, not just its classification tier.

What is the typical holding period for Grand Cru wine investments?

Most advisers frame Grand Cru positions as five to ten year holds, in line with fine wine’s broader investment horizon, though vineyard-based classifications like Burgundy and Bordeaux First Growth support longer horizons given their century-long stability. Saint-Emilion positions carry additional timing risk around each decennial classification review, which can accelerate or interrupt a planned holding period.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.

Categories
Learn

Investing in Spanish wine: Rioja vs Ribera del Duero

  • Spain’s investment market is built on two complementary regions: Ribera del Duero’s scarcity and Rioja’s value.
  • Vega Sicilia and Pingus dominate Ribera del Duero, while Rioja offers a broader range of highly traded producers.
  • Rioja’s evolving vineyard classification could further differentiate its top wines over the coming years.

Spain has quietly become one of the fine wine market’s most compelling investment regions. Once regarded primarily as a source of value, it now offers investors two distinct opportunities built on very different foundations. Ribera del Duero revolves around scarcity, led by Vega Sicilia’s Unico and the cult wines of Pingus. Rioja offers a broader market of highly rated wines, competitive pricing and an evolving vineyard hierarchy that places greater emphasis on origin. Understanding how those two markets differ is the key to understanding Spain as an investment.

Spain has built a durable secondary market

Spain’s rise has been gradual rather than dramatic. The number of distinct Spanish wines traded on Liv-ex increased thirteenfold in the decade to 2022, reflecting a market that has expanded well beyond a handful of flagship labels. That breadth, with more producers changing hands regularly, is what transforms a regional trend into a durable investment category.

The buyer base has broadened too. Spain’s share of Liv-ex trade value roughly doubled between 2023 and 2024, with demand increasingly spread across Europe, the United States and Asia rather than concentrated in a single market. For investors, that wider and more geographically diverse pool of buyers supports liquidity over the long term.

Price remains another important advantage. Spanish fine wine typically trades well below comparable wines from Bordeaux or Burgundy despite often receiving similarly strong critical acclaim. That allows investors to access highly rated, limited-production wines without paying the premiums associated with the market’s most established regions.

Ribera del Duero and Rioja offer different investment profiles

Although Ribera del Duero remains Spain’s largest fine wine region by trade, its market is unusually concentrated around Vega Sicilia. Rioja, by contrast, is supported by a broader group of established producers, giving it a different balance of concentration, liquidity and opportunity.

Vega Sicilia alone accounts for around half of Spain’s secondary-market trade, meaning the fortunes of a single estate continue to shape Ribera del Duero’s investment profile. Rioja’s activity is distributed more evenly across producers such as La Rioja Alta, Marqués de Murrieta and Muga, while smaller regions including Priorat, Toro and Méntrida contribute a modest but persistent share of trading.

The difference reflects the regions’ histories. Vega Sicilia spent much of the twentieth century establishing Ribera del Duero’s international reputation almost single-handedly, whereas Rioja developed through several long-established houses growing alongside one another. Today, investors are effectively choosing between two complementary markets rather than a single Spanish category.

Vega Sicilia’s Unico remains Spain’s benchmark

Founded in 1864, Vega Sicilia remains the benchmark against which every other Ribera del Duero producer is measured. Its flagship Unico is released only in vintages the estate considers worthy, while prolonged ageing before release and consistently low production keep demand structurally ahead of supply. For investors, that combination of scarcity and reputation is the foundation of the wine’s long-term appeal.

Vintage selection still matters. The 2004 and 2014 releases are the highest-rated physical vintages of the past two decades, both awarded 98 points by The Wine Advocate (the 2004 was upgraded from 97 points in 2023).

Performance has reflected those differences. The 2004 was first released in the UK at £1,920 per 12x75cl case and has since traded around £3,300. Meanwhile, the 2013 vintage, despite earning a strong 97-point score, continues to trade below the similarly rated 2009 and 2010, offering relative value for investors entering the label today.

Pingus offers three routes into a cult producer

Unlike Vega Sicilia, whose reputation developed over more than a century, Pingus became a cult wine almost overnight. Danish winemaker Peter Sisseck established the estate in 1995 after acquiring tiny parcels of old-vine Tinto Fino near La Horra. Near-perfect reviews from Robert Parker before the wine’s first commercial release propelled Pingus to international prominence, and it has remained one of Spain’s most sought-after wines ever since.

The estate has a three-tier portfolio:

  • Psi – the most accessible (but not investment-grade) label, sourced from old-vine growers across Ribera del Duero.
  • Flor de Pingus – the second wine, produced from younger estate vines.
  • Pingus – the flagship wine, produced in tiny quantities, regularly awarded high critic scores and commanding four-figure prices per bottle.

Across all three wines, Peter Sisseck follows the same philosophy of low yields, hand harvesting and minimal intervention. The consistency of that approach has helped sustain collectors’ demand across both the second and first label.

Rioja’s vineyard hierarchy is evolving

Rioja now offers investors another dimension to assess beyond the traditional Crianza, Reserva and Gran Reserva categories. Since 2017, DOCa Rioja has introduced geographical designations that recognise wines at increasingly specific levels of origin: sub-region (Vino de Zona), village (Vino de Pueblo) and, at the highest level, single vineyard (Vinedo Singular). The latter is reserved for estate-managed vineyards that satisfy strict requirements, including minimum vine age, lower yields and hand harvesting.

The reforms reflect a growing emphasis on terroir rather than ageing alone. Although Rioja’s hierarchy is not directly comparable to Burgundy’s classification system, it moves in a similar direction by recognising increasingly specific vineyard origins. Over time, that could create greater differentiation between the region’s finest wines and the wider market.

Rioja’s value proposition remains one of the strongest in fine wine

Rioja’s appeal has long rested on its exceptional quality-to-price ratio, and that advantage has remained intact as the secondary market has matured. La Rioja Alta’s Gran Reserva 890 sits at the top of the estate’s range and is produced only in selected vintages after extensive ageing. Despite its scarcity and flagship status, it remains considerably more accessible than comparably acclaimed wines from Bordeaux, Burgundy or California.

That value has not come at the expense of secondary-market demand. La Rioja Alta is one of Rioja’s most established names, supported by an increasingly international buyer base that now extends well beyond the UK’s traditional dominance.

Marqués de Murrieta’s Castillo Ygay Gran Reserva Especial demonstrates the same principle. Produced only in exceptional vintages and matured for more than a decade before release, the 2012 received 97 points from The Wine Advocate and 100 points from James Suckling. Despite those credentials, it continues to trade at a substantial discount to Vega Sicilia’s Unico, giving investors access to two of Rioja’s most acclaimed and selectively produced wines without entering Spain’s highest price tier.

Spain has earned a strategic place in fine wine portfolios

Spain’s investment case rests on long-term structural trends rather than short-term market cycles. The secondary market has become broader, deeper and increasingly international, while investors today can choose from a far wider range of producers than ever before.

The country’s two leading regions complement rather than compete with one another. Ribera del Duero offers scarcity through Vega Sicilia and Pingus. Rioja provides breadth, liquidity and some of the strongest quality-to-price opportunities in the fine wine market, reinforced by a vineyard classification system that increasingly rewards origin.

Taken together, they have transformed Spain from a niche allocation into one of the fine wine market’s most compelling long-term investment opportunities. Whether investors prioritise Ribera del Duero’s limited-production cult wines or Rioja’s broader value proposition, both regions now deserve consideration alongside the market’s more established investment destinations.

FAQ: Investing in Spanish fine wine

Is Spanish fine wine a good investment?

Spanish fine wine can offer a combination of established producer reputations, limited production and lower entry prices than comparable wines from Bordeaux or Burgundy. However, performance varies considerably by producer and vintage. Wines with strong critical reviews, international demand and a consistent secondary market record generally present the clearest investment case.

Which Spanish wines are considered investment grade?

The most established investment-grade names include Vega Sicilia, Dominio de Pingus, La Rioja Alta and Marques de Murrieta and a case can be made for investment in the likes of Alvaro Palacios, Artadi and Bodegas Contador. Vega Sicilia Unico and Pingus dominate the upper end of the market, while La Rioja Alta Gran Reserva 890 and Marqués de Murrieta Castillo Ygay offer access to highly regarded Rioja at comparatively lower prices.

Is Rioja or Ribera del Duero better for investment?

Neither region is inherently better, but they offer different investment characteristics. Ribera del Duero is more concentrated, with Vega Sicilia and Pingus accounting for much of its international demand. Rioja has a broader producer base and generally lower entry prices, making it more accessible to investors seeking value and diversification.

How much does it cost to invest in Spanish fine wine?

Entry prices vary widely. Leading Rioja can cost substantially less than the flagship wines of Ribera del Duero, while Pingus and mature vintages of Vega Sicilia Unico can command four-figure prices per bottle. Investors should compare the price of a full case, storage costs and likely resale demand rather than judging affordability by the bottle price alone.

How liquid is the secondary market for Rioja and Ribera del Duero?

Liquidity has improved markedly but remains narrower than Bordeaux. The number of distinct Spanish wines trading on Liv-ex rose thirteenfold over the decade to 2022, and wines like La Rioja Alta’s 904 Gran Reserva have become some of the more consistently traded labels on the exchange by volume.

Is Pingus a riskier buy than Vega Sicilia?

Pingus carries more concentration risk given its small production and single-estate focus, while Vega Sicilia’s longer trading history and larger share of Spain’s total Liv-ex value give it deeper price discovery. Newer cult labels like Pingus have historically shown sharper swings in secondary market standing than established houses.

Why is Pingus so expensive?

Pingus is produced in very small quantities from old Tempranillo vines in Ribera del Duero. Its scarcity, high critical scores and cult reputation have placed it among Spain’s most expensive wines. Its price reflects both the quality of the wine and the limited number of bottles available to collectors.

What does Gran Reserva mean in Rioja?

Gran Reserva is an official ageing category rather than a direct guarantee of investment quality. Rioja red wines must satisfy minimum ageing requirements before they can carry the designation, but producer reputation, vintage quality, production volumes and secondary-market demand remain more important to investors.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.

Categories
Learn

How to develop a taste for fine wine and know what’s actually worth investing in

  • The most effective way to develop a taste for fine wine is exposure: drinking widely, tasting deliberately, and building a personal reference library of what you notice.
  • A wine being exceptional to drink does not make it investable; brand power, secondary market liquidity, and trading data are better indicators than personal preference.
  • Formal wine education and a developed palette are by no means necessary to be a successful wine investor, although each complements the other.

A developed palate and an investment-ready portfolio have commonalities and start from the same place: time spent studying wine. There is no shortcut. Reading, studying tasting frameworks, and visiting wine regions all accelerate the process, but they cannot replace the simple pleasure of tasting and the knowledge that helps accumulate about what quality looks and tastes like. This article covers how to build that knowledge, what resources and education are worth pursuing, and why a wine that tastes exceptional is not necessarily a wine worth buying as an asset.

How do you develop a taste for fine wine?

Exposure is the answer, and it is the only one that works. A trained palate is the foundation on which judgment is built: tasting widely, tasting deliberately, and paying attention to each glass builds an internal reference library. Reading about wine is useful; books, frameworks, and expert notes all provide context but it cannot substitute for the physical experience of comparison.

The practical question is where to point that attention. Two approaches work, and both are equally valid. The first is the deep dive: choosing a producer or region that already appeals and working through their range, back vintages, and sub-appellations. This builds depth quickly. An investor who has tasted several vintages of the same wine across different years develops an understanding of how the wine ages and how the style holds across seasons of varying quality. 

The second approach is the wide circle: drinking across as many regions, grapes, and styles as possible to accumulate comparison points. Both are legitimate and the choice often reflects learning style more than anything else.

The strongest argument for breadth is what unfamiliar wines reveal and the simple pleasure of being surprised. A palate trained only on a single region can of course recognise quality but will miss context, encountering something genuinely strange also forces a more conscious response. Drinking a Savagnin from Jura, or a Txakoli from the Bsaque region will expose you to an experience you could never have elsewhere.

These are not investment categories but they are exercises in calibration. The contrast they provide makes the reference points of Burgundy, Bordeaux, and Champagne easier to understand and easier to articulate with precision.

Keeping records: tasting notes and apps

Writing things down is not mandatory, but a personal record of what has been tasted quickly becomes a reference tool that informal memory cannot replicate. A written tasting note forces a decision: recording observations requires a choice of words, and choosing words demands conscious attention rather than the passive experience of enjoying a glass. Even occasional notes build an archive that, over time, reveals patterns in preference, signals in structure, and gaps in knowledge that informal tasting alone rarely exposes.

The format does not need to be elaborate. A few sentences on what the wine looked like, how it smelled, what it tasted like, and what comparison it triggered is sufficient to start building a record. The physical act of writing also helps to retain memory. Those who prefer a digital home for those records over a fountain pen and a notebook have two particularly strong options. 

  • Vivino is the most widely used wine app: scan a label, rate the wine, and build a personal log with minimal friction. It suits beginners well. 
  • CellarTracker is more sophisticated: it allows detailed tasting note records, full cellar management, and access to a large community database of notes from serious collectors and experienced enthusiasts. 

For an investor managing a portfolio without access to a portal like WineCap’s, CellarTracker also offers a level of organisation that informal note-keeping cannot match.

Using a structured tasting framework

Tasting is ultimately a personal experience, and everyone’s sense of taste and personal preferences are different. However, structured tasting with a shared vocabulary has significant value and turns personal impressions about wine into transferable language. A note that records “nice red, quite tannic” is better than nothing, but it does not build a vocabulary or allow meaningful comparison over time.

The best known and most widely agreed upon structured tasting is the WSET’s Systematic Approach to Tasting (SAT), used across all four levels of their qualification framework. It provides a consistent method for assessing a wine’s appearance, nose, palate, and overall quality, and for recording those observations in terms that other tasters can understand and compare. The full level two framework is available here

Below is an example of the SAT applied to Chateau Montrose 2016, a Saint-Estephe Second Growth with significant investment credentials and a structure that rewards close attention:

  • Appearance: deep ruby-red with a dark, almost inky core; narrow garnet rim indicating youth; clear and bright
  • Nose: pronounced intensity; blackcurrant, blackberry, cedar, cigar box, graphite, dark chocolate, iron
  • Palate: dry; medium-high acidity; high, firm, grippy tannins; medium alcohol; full body; pronounced flavour intensity; black cherry, cassis, tobacco, pencil shavings; very long finish.
  • Conclusions: high quality; emphatically youthful; suitable for bottle ageing.

The structural observations, particularly the tannin level, acidity, and length of finish, carry investment relevance too: High tannin and good acidity are structural indicators of a wine’s capacity to age and, by extension, the point in the future at which it will reach peak value on the secondary market. A wine that drinks beautifully young but lacks structure rarely achieves the same price trajectory.

Formal wine education

Formal qualifications are not a prerequisite for either a good palate or sound investment judgment. What they provide is something that tasting alone does not easily deliver: a shared vocabulary and a consistent analytical framework that makes it possible to communicate precisely about what a wine is doing and why it matters. The Wine and Spirit Education Trust (WSET) is the most widely recognised and accessible provider, offering courses at four levels suited to almost any level of interest or commitment.

Level 1 covers the basics in a single day, providing enough structure and vocabulary to drink more consciously and to begin taking useful notes. Level 2 and 3 develop understanding of grape varieties, key regions, and the fundamentals of winemaking. The Level 4 Diploma, WSET’s highest qualification, typically takes two or more years to complete and covers everything from viticulture and production to regional wine law, the structure of the global wine trade, and contemporary market questions. 

The Master of Wine (MW) represents the highest formal attainment in the wine world. The qualification requires years of dedicated study, passing theory papers, submitting original research, and a notoriously demanding blind tasting examination. The pass rate for the tasting section is often as low as 10 to 15 per cent. 521 people have passed the exam since 1953. It is not a realistic pursuit for most wine enthusiasts, but it provides a useful reference point for what the summit of formal wine expertise looks like.

The Court of Master Sommeliers offers a parallel route, though it is primarily weighted toward wine service and the restaurant trade.

Wine travel and investment regions

Visiting a wine region is one of the best ways to transform abstract knowledge into physical understanding. For an investor or a collector, that understanding clarifies why certain producers command the prices they do and provides a frame of reference for interpreting the secondary market data and trading records that underpin investment decisions. The landscape, the soil types, the proximity of parcels to each other, and the scale at which different estates operate all become legible in a way that reading cannot fully replicate.

Bordeaux and Champagne are the natural starting points. Both regions offer highly developed wine tourism infrastructure, with cellar visits and formal tasting experiences widely available. As two of the most invested in regions, both are also directly relevant to wine investors: the wines encountered on a visit are the same wines measured by WineTrack and priced daily across global exchanges.

The case for local exploration is equally strong. Wine tourism does not require a transatlantic journey or even going to an airport. Readers in the UK will find that the South East of England has developed a serious and well-organised wine tourism scene, with several English sparkling wine producers now attracting strong international critical attention and offering estate visits and tastings. Every state in the USA has wineries from New York in the east, Minnesota in the north, Louisiana in the South and of course California in the west. For visitors to South Africa, the Cape Winelands, particularly Stellenbosch and Franschhoek, offer some of the most visitor-friendly wine tourism anywhere in the world alongside a diverse range of wine styles and price points.  

In almost every country in the world there will be wineries to visit, and a visit to any winery will have a huge amount of practical value to someone interested in growing their knowledge and their palate.  Understanding wine in its place of origin is more efficient than encountering it only at the point of sale.

Essential reading

While no book can replace practical knowledge, there are a number that are of enormous value to wine lovers, and the right books provide context that accelerates tasting rather than replacing it. 

A reader who understands the geography, climate, and classification systems of Bordeaux before opening a bottle of Pauillac will notice more in the glass and ask more useful questions. Four titles stand out as worthy additions to any wine lovers library:

  • The World Atlas of Wine (Hugh Johnson and Jancis Robinson, 8th edition, 2019): The definitive geographical reference, covering every major wine region with detailed maps and producer notes; 
  • Wine Folly: The Master Guide (Madeline Puckette and Justin Hammack, 2018): Visually driven and accessible; the most useful starting point for beginners who absorb information through image and diagram rather than dense text;
  • The Oxford Companion to Wine (edited by Jancis Robinson and Julia Harding, 4th edition, 2015): Encyclopaedic and authoritative; not a book to read cover to cover, but an essential reference when a term, region, or grape variety requires proper investigation;
  • The Wine Bible (Karen MacNeil, 3rd edition, 2023): Comprehensive regional coverage written in a narrative style that makes it considerably more readable than most reference books of comparable scope.

None of these titles provides up to date market data and while the Oxford Companion to wine does include information about wine investing, it is not its focus. For current price performance and secondary market activity, dedicated platforms and trading databases are required alongside them. WineCap’s editorial section covers the investment and market context behind specific wines and regions, making it a useful complement to personal tasting records. A note on what a wine tastes like gains more meaning alongside an understanding of where that wine sits in the secondary market hierarchy. 

Does liking a wine mean it’s a good investment?

Emphatically not. These are two separate questions, and conflating them is one of the most consistent errors that new wine investors make. A wine that tastes exceptional is evidence of quality, and quality matters. But quality alone is not sufficient for investment potential, and the distinction between the two is commercial rather than aesthetic.

The wines that sustain consistent secondary market activity are almost universally those that carry global name recognition built over decades: the Bordeaux first growths, Domaine de la Romanee-Conti (DRC), Petrus, Screaming Eagle. A superb wine from a little-known producer may be fantastic in the glass, but without an active secondary market to sell into, it cannot be exited at a fair price. Without buyers, there is no return.

What drives investability is a convergence of factors that go well beyond what any tasting note captures:

  • Brand power: Name recognition and heritage that generates demand from buyers worldwide, independently of what a specific vintage scores or how it drinks at a given moment.
  • Secondary market liquidity: An active, global pool of buyers at any given point; this is what allows a position to be exited without accepting a distressed price.
  • Critic scores: A useful signal of quality and capable of driving short-term market interest, but insufficient as a standalone indicator; a 100-point score from Robert Parker or a top recommendation from Jancis Robinson can move prices, but it does not guarantee sustained secondary market activity over a decade.
  • Demand: How frequently a wine is searched for and how many merchants list it globally provides a useful proxy for commercial footprint and consumer awareness; wines with thin search presence are harder to sell regardless of quality.
  • Performance history and trading data: While data from Liv-ex is available only to trade members WineTrack, WineCap’s proprietary tracking tool shows the aggregate price performance of an individual wine across multiple vintages and average prices across multiple vintages. This information provides a fuller picture of how it has behaved as an asset over time rather than isolating any single vintage or release.

The investment decision is about convergence across all of these dimensions. A wine that scores on quality, carries genuine brand recognition, shows consistent secondary market liquidity, and demonstrates a sustained price trajectory across vintages is a fundamentally different proposition from one that simply tastes exceptional.

The palate and the portfolio

A developed palate and a clear understanding of what the secondary market rewards are not the same education, but they are not in conflict. Wine investors are often wine lovers: the affinity drives the attention, and the attention builds the reference library that makes better decisions possible. What separates investors from passionate drinkers is that they have learned to hold that love alongside a clear-eyed view of what the market will and will not reward.

Neither education finishes. Every new wine encountered shifts the frame of reference slightly. Every vintage that ages reveals something about what the wine was doing in youth that real-time tasting notes can only partially capture. Market knowledge develops in exactly the same way. The goal is not to arrive at a fixed expertise. It is to keep both processes running in parallel, and to remain clear on which one informs which.

FAQ: Developing a taste for fine wine

How long does it take to develop a palate for fine wine?

A palate is never finished developing. Every new wine encountered shifts the reference point; every return to a wine tasted years earlier reveals how both the wine and the drinker have changed. A useful working vocabulary can we learned in a weekend with the WSET’s frameworks but experienced tasters with decades of exposure still encounter new reference points regularly. The palate that stops developing is one that has stopped encountering new things, not one that has arrived at a plateau.

Do I need a WSET qualification to invest fine wine?

No. WSET qualifications are valuable for building vocabulary, but they are not a prerequisite for investment. Many serious wine investors and wine lovers hold no formal qualification. What matters is an understanding of how the secondary market works, what drives price performance, and how to read trading data rather than relying solely on critical scores. WineCap’s editorial section and tools like WineTrack provide that market context without requiring any qualification.

What makes a wine investment-grade rather than just high quality?

Investment-grade wine combines quality with commercial infrastructure: brand recognition, secondary market liquidity, and a documented price trajectory across vintages. Quality earns critical attention; brand power and liquidity determine whether it can generate a financial return.

Does a high critic score guarantee a good investment?

No, though it can be a short-term market driver. A 100-point score from a notable critic can drive immediate interest and lift prices but sustained secondary market performance depends on brand power and global liquidity, not on any single critical verdict. None of the  most traded wines hold their position on the strength of a single exceptional score alone.

How do I start tracking the wines I have tried?

Tracking the wines you have tried can be as simple as a notebook and a fountain pen and as complicated as a database as you could possibly imagine. Vivino is a good starting point: scan a label, rate the wine, and build a personal log with minimal friction. CellarTracker is a more sophisticated option for anyone who wants to record detailed tasting notes, manage a cellar, and access a community database of notes from serious collectors. WineTrack shows aggregate price performance across vintages, providing market context alongside personal tasting records and helping investors understand how a wine has moved as an asset rather than simply how it has tasted.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.

Categories
Learn

Ten things about Chateau d’Yquem: Inside Sauternes’ greatest estate

  • Chateau d’Yquem is the sole Premier Cru Superieur in the 1855 classification, a category it occupies alone, above all other Sauternes estates.
  • WineCap’s Yquem index peaked at exactly 50% growth in early 2023, holding its gains, while wider Bordeaux declined sharply after the 2022 market correction.
  • Each vine at Yquem produces roughly one glass of wine per year, making it one of the most labour-intensive fine wines produced anywhere in the world.

Chateau d’Yquem occupies a unique position in the world of fine wine. The only estate awarded Premier Cru Superieur in Bordeaux’s 1855 Classification, it has long been regarded as the benchmark for Sauternes. That exceptional status has translated into enduring collector demand, one of the strongest long-term investment records in the region, and auction prices that have set records for sweet and white wines alike. These ten facts explain what makes Château d’Yquem one of fine wine’s most distinctive investment assets.

1. The most expensive wine in the world to make

Sauternes is the most labour-intensive wine classification in France. Producing it requires botrytis cinerea (noble rot), a fungus that infects and shrivels grapes on the vine, concentrating sugar and flavour into small, wizened berries. At Yquem, that process is pursued with greater intensity than anywhere else in the world. Each vine produces roughly one glass of wine per year. Pickers make multiple passes through the vineyard, called tries, selecting only berries at the precise stage of botrytization. Three passes is now the norm, but in 1997, the harvest required seven separate tries over 32 days.

That selectivity has structural consequences for supply. Around 90 experienced pickers return to Yquem each harvest, and approximately half the fruit they deliver is rejected daily. Cellarmaster Sandrine Garbay assesses each batch at reception, sending pickers back if the fruit falls short. No other estate in Bordeaux maintains this level of selectivity.

2. Noble rot and the wine that never dies

Botrytis cinerea transforms a grape rather than simply concentrating it, and that transformation is the reason Yquem can outlive every other unfortified wine in the world. The fungus penetrates the skin of grapes, extracting water and leaving behind a richer, more complex liquid. Yquem’s microclimate makes this possible: morning mist from the Ciron, a tributary of the Garonne river, coats the vines with moisture that encourages the infection. Afternoon wind and sunshine then dry the grapes, halting the process at precisely the right moment.

The same chemistry that creates the wine also preserves it. Residual sugar, glycerol, and natural acidity produced by botrytis combine as natural preservatives, without any added spirit. Port survives centuries because grape spirit stops fermentation, leaving behind unfermented sugars; Yquem needs no such intervention and is so long lived that the 1811 and the 1847 are still discussed as living wines.

Sauternes sits within a broader family of great sweet wines, but its method is distinct.

  • Port: Fortified by adding raw grape spirit, this kills the yeast and stops fermentation, which preserves sweetness and boosts alcohol.
  • Trockenbeerenauslese: Germany’s most concentrated category, made from individually selected, often botrytis-affected, desiccated berries from cooler terroir. Superb longevity, but a different flavour profile.
  • Ice wine: Made from grapes frozen on the vine, concentrating sugar through freezing rather than fungal dehydration. No botrytis character.

All three can age for decades.

3. What makes Chateau d’Yquem so valuable?

Yquem’s investment case rests on four foundations that few wines in the world share: singular classification status, proven secondary market depth, structural scarcity, and age-worthiness measured in centuries rather than decades. No other Sauternes holds Premier Cru Superieur status. No other Sauternes commands comparable global demand. No other Sauternes enjoys the same reputation, and no other Sauternes is subject to such strict selection standards by the producer.

WineCap’s Yquem index peaked at exactly 50% growth in early 2023, driven by collector demand during a period of sustained interest in fine wine as an asset class. Since then, there has been relatively little drop-off, particularly when compared with the broader Bordeaux market, which fell sharply after the correction that began in 2022. Some falls occurred in the 2011 to 2014 period, but the long-term trend has been consistently upward. That resilience matters to investors who have watched comparable positions in Bordeaux red wine decline.

Yquem is by some distance the leading Sauternes estate on the secondary market: the strongest long-term performer and most liquid Sauternes. Other notable producers include:

  • Climens: Notable recent price rises have been driven by a series of missing vintages in the late 2010s, which reduced available stock. Strong short-term performance, but thin trading depth makes positions harder to exit reliably.
  • Rieussec: Rising release prices from the estate have gradually lifted back-vintage values, creating positive momentum. Secondary market depth still lags behind Yquem.

4. The vintages that never were

Quality is not an aspiration at Yquem. It is a standard with consequences. Ten times across more than a century, the team decided the wine simply was not good enough to release. No second label absorbed the declassified fruit. No portion of the harvest reached the market. The wine sold in bulk, and the vintage disappeared from the Yquem record.

No Yquem was released in: 1910, 1915, 1930, 1951, 1952, 1964, 1972, 1974, 1992 or 2012.

Cellarmaster Sandrine Garbay commented regarding the 2012 vintage: “The 2012 season was dramatic. I really saw what gray rot is. We threw everything away.”

The counterpoint is equally revealing. Yquem produced wine in 1931, 1965, and 1977, years so difficult that most of Bordeaux wished it had not tried. The ability to extract something creditable from the worst conditions is the test of a great terroir. Every time Yquem releases in a difficult vintage, it reinforces the gap between itself and the rest of the appellation.

5. The most critically acclaimed wine ever made

The Yquem 2001 is, by consensus, the most lauded wine in the history of professional criticism. Multiple leading critics awarded it perfect scores. Cellarmaster Sandrine Garbay said: “I thought I would never see that kind of growing season again in terms of the purity and intensity of flavour.” The season delivered exactly what botrytis demands: morning mist, afternoon wind, and a pace of infection that allowed extraordinary complexity to build slowly across every parcel.

Yquem Scores

The question now occupying serious collectors is whether the Yquem 2009 will ultimately rival it. Critic Neal Martin raised this directly: “My only question pertaining to the 2001 is whether the 2009 might ultimately surpass it; time will tell.”

For investors, both vintages represent the same fundamental opportunity: a wine at the peak of its critical reputation, in finite and diminishing supply. The 2001’s excellence is better established and more complete, but the 2009 is more affordable and may in due course represent the better opportunity.

6. The comet vintage and the world’s most expensive bottle

In 1811, a great comet blazed across the European sky for 260 days, the longest recorded period of visibility until Hale-Bopp in 1997. The summer was extraordinary: warm, dry, and long, producing wines across France and Germany that bore its name for generations. Yquem 1811 became the most celebrated of the comet vintages and, on two separate occasions, the most expensive white wine ever sold. No other white wine has approached either threshold.

In July 2011, a 75cl bottle of Yquem 1811 sold at London’s Ritz Hotel, offered by rare wine specialists The Antique Wine Company, for HK$904,000 (approximately £72,000 / $116,000 at the time). The buyer was French private collector Christian Vanneque. The previous world record for the most expensive white wine sold at auction was also held by Yquem: the 1787 vintage at HK$468,000. That both world records belong to the same estate makes a point no marketing can replicate.

The 1847 Yquem is the other great 19th-century reference. That year, a 900-litre tun sold to Grand Duke Constantine, brother of the Russian Czar, for 20,000 gold francs in 1859. The sale announced Yquem’s reputation across European courts and established the template for the extraordinary prices its historic bottles still command today.

7. Y d’Yquem and the quiet revolution in Sauternes

Y d’Yquem (pronounced “ee-grek”) is the estate’s dry white wine, and its existence signals something investors should note: Yquem is actively working to broaden the appeal of Sauternes to new audiences.

Produced since 1959 but made every year only since 2004, it is limited to under 10,000 bottles annually. Estate manager Lorenzo Pasquini describes it as “dry but not completely, a nice encounter between the freshness of a great white wine and the voluptuousness of what reminds us of a Sauternes.”

Yquem is not alone in this direction. Several leading Sauternes estates now produce dry whites alongside their sweet wines:

  • Guiraud, one of the appellation’s consistently high-quality First Growths.
  • Clos de Lunes, made by the Lurton family, who also produce highly regarded whites at Domaine de Chevalier in Pessac-Leognan. 
  • Suduiraut, one of the best-value estates in the Sauternes appellation, offering an accessible price point in the dry category.
  • Climens, the leading estate in Barsac (the Sauternes sub-appellation), has also committed to the category.

Climate change is a part of this as warmer vintages push sugar levels higher and compress the window for selective picking, but this is largely an issue of commercial necessity. Dry whites are both cheaper to make and easier to sell.

8. Yquem and the art of disappearing: a castle hoard and a restaurant heist

Yquem inspires a level of obsession that extends beyond the dining room, and bottles carrying dependable provenance histories command premiums that transcend vintage quality. Two stories, separated by decades, illustrate what that obsession looks like in practice.

In 1945, the aristocratic Beaufort-Spontin family fled Czechoslovakia as the war ended. Before leaving their home at Becov Castle, they hid 136 bottles of wine beneath the chapel floor alongside the Reliquary of St Maurus. Eight of those bottles were Yquem, from the 1892 and 1896 vintages. The collection lay concealed until 1985, when police discovered it following attempts by an American businessman, acting on the family’s behalf, to retrieve it.

In 2016, Yquem’s team used a Coravin device (a needle that extracts a sample through the cork without opening the bottle) to test the wine. It was alive. Cellar master Toni El Khawand led the reconditioning. Only five full original bottles survived intact. They are now on display at Becov Castle. El Khawand described the wine as “a liquid memory.”

The second story moves to October 2021 and the Michelin-starred Atrio restaurant in Caceres, western Spain. Constantin Gabriel Dumitru, a Romanian-Dutch thief, and his partner Priscila Lara Guevara checked in, completed a 14-course tasting menu, and in the small hours stole 45 bottles from the cellar. Among their haul was a bottle of Yquem 1806.  That bottle had already lived several lives: bought at Christie’s London in December 2000 for £6,380, its neck broke during storage in 2001, and the estate reconditioned and re-corked it under a new label signed by Sandrine Garbay. Both thieves were caught and convicted; so far, the bottles have never been found.

9. Beyond the cheese board: Yquem and the art of food matching

Sauternes has spent decades relegated to the dessert course. Repositioning it as a versatile food wine is the estate’s most significant commercial effort and, for investors holding Yquem over the long term, the size of the future collector market depends in part on how successfully that repositioning lands. The most visible expression is the Lighthouse project that began in 2019: a curated network of restaurants worldwide that serve Yquem by the glass alongside specific dishes, reaching drinkers who would never encounter it through a traditional wine list.

The pairings that work best, traditional roast chicken and spiced dishes from India, Mexico, and South-East Asia, challenge expectations and the belief that sweet wines sit at the end of a meal. As the Lighthouse programme introduces Yquem to younger drinkers, it also builds the collector base of the future.

10. From Thomas Jefferson to LVMH: 250 years of ownership

Thomas Jefferson brought Yquem to global attention in May 1787, during his tour of French wine regions as US minister to France. In December of that year, he wrote to the estate requesting 250 bottles of the 1784 vintage and later ordered 30 dozen on behalf of President George Washington, with each president’s initials embossed on the glass. His letter, addressed to “the Lady of Yquem,” acknowledged who was actually running the estate.

That woman was Josephine de Sauvage, orphaned at 17 and widowed at 20, who oversaw Yquem’s transformation into the world’s most revered sweet wine. Arrested three times during the French Revolution, she escaped the guillotine by proving the estate had been purchased rather than granted as a feudal privilege. She pioneered the system of tries (selective passes through the vines) now mandatory for all Sauternes producers. When the 1855 classification named Yquem the sole Premier Cru Superieur, it confirmed what she had built.

The Lur-Saluces family held the estate for more than two centuries before Bernard Arnault of LVMH began acquiring shares in 1996. Alexandre de Lur Saluces fought the sale through the courts before accepting the inevitable. LVMH gained a controlling stake by 2000, and Pierre Lurton was appointed director in 2005, simultaneously overseeing Cheval Blanc. Yquem’s acquisition sat alongside Cheval Blanc and Domaine des Lambrays in LVMH’s first wave of serious fine wine investment, a statement that the world’s leading luxury group and the world’s greatest sweet wine belong in the same portfolio.

Where Yquem fits in a serious wine portfolio

Yquem belongs in a different category from every other sweet wine. Its singular classification, 250-year track record, proven secondary market depth, and resilience through the 2022 Bordeaux correction make it the only Sauternes that sits alongside Bordeaux and Burgundy in an investment portfolio without qualification. 

FAQ: Chateau d’Yquem as an investment

Is Chateau d’Yquem a good wine investment?
Yquem is the most liquid Sauternes on the secondary market and the only sweet wine with the trading depth that allows investors to enter and exit positions reliably. WineCap’s index held its gains better than the wider Bordeaux market through the subsequent correction. For investors seeking exposure to Sauternes, it is the strongest and most consistent option available.

How much does Chateau d’Yquem cost?
Recent vintages trade from around £200 per bottle on the secondary market. The most sought-after releases, including the 2001 and 2009 are closer to £400. Historic bottles can be much more costly, with 20th century bottles often above £3,000 and 19th century bottles regularly trading above £20,000.

How long does Chateau d’Yquem last?
Properly stored Yquem can last centuries. The residual sugar, glycerol, and natural acidity created by botrytis cinerea act as natural preservatives without any added spirit. With correct storage conditions, modern vintages should comfortably exceed 50 years in bottle and very likely much longer.

What is the best Yquem vintage to buy?
The 2001 is the most critically acclaimed sweet wine ever produced and probably the most consistently scored wine of any description with perfect scores from multiple leading critics. The 2009 is the vintage most likely to challenge it for quality. For investors seeking a more accessible entry point younger vintages may be more attractive.

How does Yquem compare to other Sauternes as an investment?
Yquem is the strongest performer and most liquid Sauternes on the secondary market by a considerable margin. No other producer offers the same consistent quality, trading depth or performance.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.

Categories
Learn

Best UK wine clubs compared: Subscription clubs vs fine wine investment

  • UK wine subscription clubs start from around £20 per month, offering curated, duty-paid bottles for drinking and discovery rather than investment.
  • Several of the UK’s best-known branded wine clubs, including the Sunday Times, BBC Good Food and Daily Mail Wine Clubs, are supplied by the same buying team and fulfilment network.
  • Fine wine investment platforms differ fundamentally from subscription clubs, focusing on investment-grade wines held in bond for long-term ownership and potential resale.

Wine subscription clubs have become one of the UK’s most popular ways to discover new bottles, with memberships ranging from around £20 per month to specialist schemes with one-off joining fees. Most are built around curated deliveries selected by an expert buying team, making them ideal for regular drinking and exploration.

Fine wine investment platforms operate differently. Rather than delivering wine for immediate consumption, they focus on professionally stored, investment-grade wines that remain in bond and can later be sold on the secondary market. This guide compares the leading UK wine clubs, explains how they work, and outlines how they differ from fine wine investment.

What wine subscription clubs offer

A wine subscription club is a curated retail service rather than an investment vehicle. Members receive regular deliveries chosen by a buying team, usually organised by region, style or producer.

The wine is delivered duty paid to a home address and is intended to be enjoyed. Unlike investment-grade wine held in bond, there is generally no established mechanism for storing the bottles professionally or selling them later through the secondary market.

A wine subscription club usually provides:

  • Curated discovery, with a buying team selecting wines the member would not necessarily choose themselves
  • Regular delivery on a monthly or quarterly schedule, or on a flexible credit-accumulation model
  • VAT and duty paid at purchase, the standard UK retail transaction
  • No storage obligations: the wine is intended for drinking, not for holding
  • No secondary market liquidity: there is no infrastructure for selling subscribed bottles on

The main UK wine clubs

The UK wine club market is more varied than it first appears. Membership models range from monthly subscriptions starting at around £20 to one-off lifetime fees, while providers include member-owned cooperatives, specialist wine merchants and publicly listed retailers. Understanding how each club operates can help buyers choose the model that best suits their drinking habits and budget.

The Wine Society is one of the UK’s oldest and most respected wine organisations. Founded in 1874 using surplus wines from the International Exhibition, it remains a member-owned, not-for-profit cooperative. Members pay a one-off £40 joining fee, with profits reinvested into the business rather than distributed to shareholders. The Society is particularly well regarded for its own-label wines, broad regional range and transparent allocation of limited releases.

Laithwaites operates the Four Seasons Club, which delivers 12 bottles every quarter. It also supplies three of the UK’s best-known media-branded wine clubs: the Sunday Times Wine Club, BBC Good Food Wine Club and Daily Mail Wine Club. Although each has different branding and marketing, they share the same buying team and fulfilment network.

Wine52 focuses on discovery, delivering three bottles each month from smaller producers alongside tasting notes, food-pairing suggestions and a magazine. The emphasis is on introducing members to wines they are unlikely to encounter in supermarkets.

Virgin Wines takes a different approach through WineBank, where members pay a monthly amount into an account and decide when to spend their credit, rather than receiving a fixed monthly case.

Naked Wines operates its Angels model, with members contributing monthly credit that helps fund independent winemakers in return for access to exclusive wines. Because many of these wines are produced specifically for the platform, direct price comparisons with other retailers are often difficult.

Many wine clubs also sell own-label or exclusive-label wines. This can offer good value and access to unique bottlings, but it also makes comparing prices across different retailers more challenging.

Wine clubs

How wine investment platforms differ from subscription clubs

Wine investment platforms and wine subscription clubs both involve buying wine, but they are designed for different purposes. Subscription clubs focus on discovery and enjoyment, while investment platforms are built around long-term ownership, professional storage and access to the secondary market.

When investment-grade wine is purchased through a wine investment platform or specialist merchant, it is typically stored in an HMRC-recognised bonded warehouse. The wine remains in bond, meaning VAT and excise duty are suspended until it is withdrawn for drinking or exported. For collectors holding wine over many years, this can significantly reduce the overall cost of ownership.

In the UK, fine wine is also generally treated as a wasting chattel, meaning gains from its sale are typically exempt from Capital Gains Tax. While wine does not lose this status if it is delivered to a home address, removing it from bond breaks the documented chain of provenance that secondary market buyers rely on when assessing authenticity, storage conditions and value.

Unlike a subscription service, a wine investment platform does not send pre-selected cases each month. Instead, purchases are based on the buyer’s objectives, whether building an investment portfolio, assembling a long-term collection or acquiring wines to enjoy at maturity. The wine remains professionally stored until the owner chooses to sell it or take delivery, making long-term ownership rather than regular consumption the primary focus.

Why provenance and in-bond storage determine value

Provenance is not a minor technical detail in the fine wine market. It is a key pricing input.

A wine held in professional bonded storage from its release carries a documented custody record: the warehouse, the owner, the dates of transfer. Professional bonded warehouses also maintain constant temperature and humidity at the levels fine wine requires for long-term ageing. Home environments rarely match those conditions consistently. Secondary market buyers can assume that they are buying a wine in optimum condition. 

A wine held at home for the same period, even under careful conditions, cannot offer the same confidence in its conditioning. Buyers discount accordingly, and the discount can be significant.

Who should choose a wine club, an investment platform, or both

Wine buying sits on a spectrum, and the choice between a subscription club and an investment platform is not always binary. The question is not whether to drink or to invest. It is what structure serves what purpose.

A wine subscription club suits the buyer who wants regular discovery at a defined monthly cost, with no obligation around storage or resale. The pleasure is immediate. The financial commitment is modest. Laithwaites, wine52, and Naked Wines are all well-suited to this profile, each with a different approach to curation and pricing.

A wine investment platform suits the buyer with a longer horizon: someone building a portfolio of fine wine over five to ten years and seeking the tax efficiency and secondary market access that in-bond ownership provides. That buyer is not choosing against wine enjoyment. They are choosing a different purchasing model and probably greater involvement in the structuring of their collection.

Many collectors run both approaches in parallel. A subscription delivers curated discovery for the table each month. An investment portfolio builds in bonded storage. These are complementary, not competing.

Buyers can help clarify the decision by answering the following questions:

  • Is this wine intended for drinking in the near term, or for holding over five or more years?
  • Does home storage meet the temperature and humidity conditions fine wine requires?
  • Is secondary market access important, or is the enjoyment of drinking the primary goal?
  • What is the monthly or annual budget, and how does that map to investment minimums?

In-person wine clubs

Not all wine clubs deliver bottles to your door. Some focus instead on providing access to exceptional wine lists, tastings and events through a membership model.

The best-known example in the UK is 67 Pall Mall in St James’s, London. Founded in 2015, the private members’ club offers one of the world’s largest wine lists by the glass, alongside dining, educational events and sommelier expertise. Membership is based on an annual fee rather than a subscription for wine deliveries, making it a different proposition from a traditional wine club.

Wine clubs vs wine investment: choosing the right option

Wine subscription clubs and fine wine investment platforms are designed for different goals. Subscription clubs offer convenience, discovery and regular enjoyment, while investment platforms focus on long-term ownership, professional in-bond storage and access to the secondary market.

For many wine enthusiasts, the two models work well together. A subscription club provides a steady stream of wines to enjoy today, while an investment portfolio preserves investment-grade bottles for future drinking or potential resale. Rather than choosing one over the other, the key is understanding what each offers and selecting the approach that best matches your objectives.

FAQ: Wine clubs

Is a wine subscription club the same as wine investment?

No. A wine subscription club is a retail product: a buying team selects bottles and delivers them to a home address, VAT and duty paid. A wine investment platform purchases bottles on a client’s behalf and holds them in a bonded warehouse in duty-suspended status, with secondary market access when the client chooses to sell. The two serve different financial and practical purposes and operate under entirely different structures.

Which wine clubs are available in the UK?

The main services include Laithwaites, wine52, Naked Wines, Virgin Wines, and The Wine Society. Three of the most prominent media-branded clubs, the Sunday Times Wine Club, BBC Good Food Wine Club, and Daily Mail Wine Club, all operate through the Laithwaites supply chain. Choice depends on budget, preferred delivery frequency, and whether the focus is discovery, specific regions, or supporting independent winemakers directly.

What is the difference between the Sunday Times Wine Club and Laithwaites?

In practice, very little. The Sunday Times Wine Club, BBC Good Food Wine Club, and Daily Mail Wine Club are all operated through Laithwaites’ buying team and supply chain. The branding and media partnerships differ, but the wines, selection process, and fulfilment infrastructure are the same across all three.

What does wine held in bond mean?

Wine held in bond is stored in an HMRC-recognised bonded warehouse in duty-suspended status. Excise duty and VAT are not paid until the wine leaves bond, either for delivery or for sale. Professional bonded storage provides controlled temperature and humidity, insurance, and a documented ownership record that supports secondary market pricing. Home storage does not provide equivalent conditions or the same provenance chain.

Can you make money from a wine subscription club?

Not in any structured sense. Once wine has been delivered to a home address, there is no established infrastructure for selling it on the secondary market. Individual bottles can theoretically be sold privately, but without a verified storage record or professional provenance chain, buyers discount heavily. Wine subscription clubs are designed for drinking, not for generating a financial return.

WineCap’s independent market analysis helps investors build diversified fine wine portfolios with full ownership and transparent pricing. Speak to one of our wine investment experts and start building your portfolio. Schedule your free consultation today.