- Investment-grade wine is characterised by exceptional quality, rarity, and a proven track record of price appreciation.
- Most investment-grade wines come from regions like Bordeaux, Burgundy, Champagne, Tuscany, Barolo, Napa Valley and the Rhône.
- Successful wine investing requires a long-term perspective, professional storage and a keen understanding of market trends.
Investment-grade wine is a short list, and knowing it changes how every other wine investment decision gets made. This guide sets out the four tests a wine must pass, then profiles the twelve producers and cuvees that anchor secondary market demand in 2026, region by region, with the data points investors should check before buying any of them. It closes with the honest market context, how to buy each name, and the traps that catch buyers of famous labels. The list is selective by design: in fine wine, what you exclude protects you as much as what you include.
The four tests of an investment-grade wine
Investment quality is observable, not mystical, and every name on this list passes the same four tests. WineCap applies them through Wine Track, our database following around 3,750 investment-relevant wines daily (WineCap, August 2026), and any investor can apply them in principle to any wine they are offered.
- Producer pedigree. Decades of consistent critical acclaim and, crucially, decades of secondary market demand. Buyers pay for predictable excellence; a single celebrated vintage does not create an investment wine.
- Ageing capacity. The wine improves or holds for twenty years or more. Ageing is what lets scarcity build before the wine must be drunk, and it also bears on UK tax treatment, covered in our guide to whether wine is a wasting asset for capital gains tax.
- Scarcity with consumption. Limited production that is steadily drunk, so every vintage’s supply only falls. Volume matters in both directions: too plentiful and prices stay anchored; too scarce and the wine barely trades.
- Liquidity. Regular trading and observable prices, so the wine can be valued honestly today and sold without heroics later. A wine with no market price is a collectible, not an investment.
The tests also explain what the list excludes, which is most of the fine wine world. Excellent wines fail on liquidity because they trade too rarely to value; celebrated producers fail on scarcity because volumes anchor prices; fashionable names fail on pedigree because their demand has never been tested across a downturn. Exclusion is not a quality judgement. It is the difference between a wine worth drinking and a wine that can do a job in a portfolio.
The regions that reliably produce wines passing all four tests are few: Bordeaux, Burgundy, Champagne, Tuscany and Piedmont, the Rhone, and a handful of names from Spain and California. That geography shapes the list below.
How we built this list
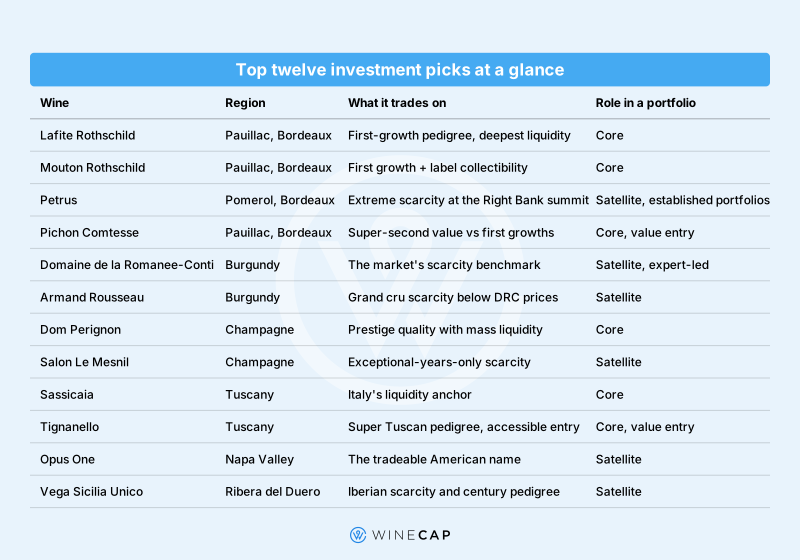
Method beats assertion, so here is ours. We selected the twelve names below on the four tests above, weighting them towards trading liquidity and depth of price history in Wine Track data. We grouped them by region rather than force-ranked, because a Bordeaux first growth and a prestige Champagne play different roles in a portfolio rather than competing for one slot. The wines are selected examples of the investment grade, not a representative sample of it, not a portfolio recommendation, and not a prediction that any of them will rise. Wines that pass every test can still fall in falling markets.
Bordeaux: the liquid core
Bordeaux earns four of the twelve places because liquidity concentrates there: the region accounted for 35.5% of secondary market trade by value in 2025 (Liv-ex data via The Drinks Business, January 2026), and its classed growths carry price histories running back decades. For most portfolios, Bordeaux is where wine investment starts.
- Chateau Lafite Rothschild (Pauillac). The most traded of the first growths and often the most demanded fine wine in Asia, Lafite pairs first-growth pedigree with production scale (tens of thousands of cases) that keeps it tradeable in any market. Its price history is among the deepest in the asset class.
- Chateau Mouton Rothschild (Pauillac). First-growth quality with a collector’s edge: artist-designed labels since 1945 that give certain vintages a second, memorabilia-driven demand stream. Our profile of Chateau Mouton Rothschild covers the estate in depth.
- Petrus (Pomerol). The Right Bank’s summit: a tiny Merlot estate whose roughly 2,500-case production meets global demand, producing some of the highest bottle prices in Bordeaux. Liquidity is thinner than the first growths, provenance scrutiny higher, and the entry price steep, which is why Petrus suits established portfolios rather than first purchases. Our guide to what makes Petrus the world’s most valuable Bordeaux wine explains the mechanics.
- Chateau Pichon Longueville Comtesse de Lalande (Pauillac). The value entry: a “super second” trading well below first-growth prices on quality critics repeatedly score alongside them. Super seconds are a common first Bordeaux purchase precisely because the pedigree-to-price ratio is the most favourable on the Left Bank.
Burgundy: scarcity’s home ground
Burgundy inverts Bordeaux’s proposition: production measured in hundreds of cases rather than tens of thousands, prices that reach the market’s summit, and liquidity that demands more patience at both entry and exit. The region rewards expertise more than any other, and it concentrates authenticity risk for the same reason, since tiny supply and enormous prices are the counterfeiter’s favourite combination. Both names below demand flawless provenance as a condition of purchase, not a preference.
- Domaine de la Romanee-Conti (Vosne-Romanee). The reference point for scarcity-driven value: grand cru monopoles measured in hundreds of cases, global demand measured in multiples of supply. DRC sits at the top of the market by price and reputation, with liquidity and authenticity risk to match; buyers should insist on flawless provenance. Our ten facts about Domaine de la Romanee-Conti profiles the estate.
- Domaine Armand Rousseau (Gevrey-Chambertin). Burgundy’s second tier of investment demand belongs to a handful of domaines whose grand crus trade on DRC-like scarcity at lower, though still substantial, prices. Rousseau’s Chambertin is the exemplar: tiny production, decades of acclaim, and a deep collector base. Burgundy rewards expertise, and our guide to Burgundy grand cru for investors is the sensible companion read.
Champagne: consumption does the work
Champagne has the clearest investment logic in fine wine: prestige cuvees are drunk in celebration worldwide, so supply attrition never pauses, while house brands keep demand broad across markets and generations. Krug, Cristal and Taittinger’s Comtes de Champagne all belong in the category’s first rank; the two names below bracket its range, from maximum liquidity to maximum scarcity.
- Dom Perignon (Moet & Chandon). The most liquid name in investment Champagne: prestige-cuvee quality at production volumes large enough to trade constantly, with a global brand that keeps consumption, and therefore supply attrition, running in every market.
- Salon Le Mesnil. The scarcity pole of Champagne: a single-vineyard, single-vintage blanc de blancs released only in exceptional years, roughly a decade after harvest. Tiny volumes and long ageing make Salon behave more like grand cru Burgundy than like its Champagne peers. As a selected example of the category’s range rather than a promise, Dom Ruinart Blanc de Blancs shows a rise of 135% over ten years on our price data (Wine Track, August 2026), a period in which the broad market first climbed steeply and then corrected. Our guide to investing in Champagne covers the category’s houses in full.
Italy: the momentum region
- Sassicaia (Tenuta San Guido, Bolgheri). The Super Tuscan that created the category, with its own DOC, six decades of vintages and the deepest liquidity in Italian fine wine. Italy’s share of secondary market trade grew through the recent downturn as buyers sought value outside France, and Sassicaia is that trade’s anchor. Our profile of Sassicaia tells the story.
- Tignanello (Antinori, Tuscany). The accessible Super Tuscan: larger production and lower entry prices than Sassicaia with the same six-decade pedigree, making it a common first Italian holding. Piedmont’s Barolo elite (Giacomo Conterno above all) belongs in the same conversation for investors going deeper into Italy; our guide to Barolo covers that ground.
Beyond France and Italy
- Opus One (Napa Valley). The most tradeable American fine wine: a Mondavi-Rothschild joint venture with global distribution, meaningful production volume and a genuine secondary market on both sides of the Atlantic. US demand matters to this name more than most, worth knowing given that American buying fell sharply in 2025 under tariff pressure and recovered to 26.9% of global purchase value by the second quarter of 2026 (Liv-ex data via The Drinks Business, January 2026; WineNews, July 2026). Our guide to Opus One profiles the estate.
- Vega Sicilia Unico (Ribera del Duero). Spain’s flagship and its one reliably investment-grade name: a decade of ageing before release, a century of reputation, and scarcity built into the production model. Unico gives a portfolio Iberian diversification without leaving the investment grade; our guide to investing in Spanish wine sets the wider context.
Picking vintages within the twelve
A name from the list is half a decision; the vintage is the other half, and it moves the price more than newcomers expect. Great vintages (2005, 2009, 2010 and 2016 are the commonly cited Bordeaux examples) carry premiums from release and typically hold demand longest, because their wines age furthest and their reputations compound. The same chateau’s wine from a modest year can trade at a fraction of the price, which cuts both ways: off-vintages of great estates offer lower entry points, but they leave the market’s radar sooner and their exit demand is thinner.
Drinking windows supply the timing logic. A wine approaching maturity sits where consumption accelerates fastest, tightening supply exactly as demand from drinkers peaks; a wine decades from readiness asks for patience the buyer must actually have. Matching vintage maturity to intended holding period is therefore a portfolio decision, not a trivia point. Our guides to the best Bordeaux vintages and the best Burgundy vintages for wine investment map the years that matter for the list’s two biggest regions.
The edge of the list: names knocking on the door
Investment grade is a perimeter that moves slowly, and watching its edge is part of following this market. Piedmont’s elite, led by Giacomo Conterno’s Monfortino, already trades on Burgundian scarcity logic and has been gaining collector attention as Italian trade share grows. Champagne’s top grower producers (Jacques Selosse above all) have built genuine secondary markets from tiny productions, though liquidity remains a fraction of the grandes marques. White Burgundy’s leading domaines pass the pedigree and scarcity tests while asking harder questions on ageing consistency.
The discipline at the edge is the same as inside it: trading data rather than marketing demonstrates demand. A rising name earns its place on this list after years of observable secondary market activity, and an investor who waits for that evidence gives up a little upside for a lot of certainty. New entries to the investment grade arrive over vintages, not headlines.
The 2026 context every buyer should hold in mind
Great names did not escape the recent correction, and pretending otherwise would misdescribe the asset. From its October 2022 peak the broad fine wine market fell roughly 30% over three years, and the Liv-ex 100 declined 2.5% in 2025 . The first half of 2026 brought signs of stabilisation: broadly flat indices in the first quarter and strengthening US participation into the second. Our market coverage of fine wine’s firmer start to 2026 follows the turn as it develops.
For buyers of the wines above, the practical readings are two. Repriced blue chips can be examined against long price histories rather than against peak-era hype, and every purchase should still be benchmarked to current market levels through data such as Wine Track before money moves. Past performance, on this list as everywhere, is not a guide to future returns.
How to buy the wines on this list
Access runs through the routes our guide to how wine investment works explains in full: a managed platform sourcing at documented market prices, en primeur for new Bordeaux releases, auction for mature rarities, or self-directed trade accounts. Two rules travel across all of them. Buy sealed original cases with unbroken bonded provenance, since these names attract counterfeiters in proportion to their fame. And compare every offer against the wine’s observable market level; famous labels are where overpaying hides most easily, because the name reassures while the price misleads.
Storage completes the purchase. Every name on this list belongs in bonded storage in the buyer’s name from day one, both for condition and because an unbroken bonded record is what lets these wines sell at full market level years later. Provenance premiums are largest precisely at the top of the market, where buyers pay for certainty as much as for wine.
Portfolio construction across the list matters more than any single pick. A first portfolio typically anchors on the liquid core names (Bordeaux, Dom Perignon, Sassicaia) before adding the scarcity satellites, a structure our guide to starting a wine investment portfolio in the UK works through with allocations. Budget shapes the sequence too: a £5,000 starting portfolio (WineCap’s minimum, August 2026) reaches the value entries and core names comfortably, while Petrus and DRC typically enter portfolios at larger scale, if at all.
What to avoid: the traps around famous names
The investment grade has a perimeter, and money is lost just outside it. Second wines of great estates, celebrity-branded cuvees, and “limited editions” of mass producers borrow investment language without passing the four tests: their scarcity is manufactured, their secondary demand thin or absent. Old wine is not automatically valuable wine; a fifty-year-old bottle from an unremarkable producer is a curiosity. And wines pitched by cold call at “guaranteed” returns fail the only test that matters before any of the four: legitimate sellers do not need to promise outcomes. Wine investment is unregulated in the UK, with no FCA, FSCS or FOS protection, so the vetting checklist in our guide to how wine investment works stands in for the safety net.
A short list is the strategy, not a limitation
Twelve names from five regions may look narrow against a world of wine, and that narrowness is the entire discipline. The investment grade exists because demand concentrates on producers whose excellence is predictable across decades, and the concentration is what creates the liquidity, the price histories and the exit routes that separate an investment from a cellar of hopes. Investors who stay inside the perimeter, buy at verified prices and hold for years give themselves the version of this market that actually works; the wines above are where that version lives in 2026.
FAQ: The best wines to invest in
What is the best wine to invest in for 2026?
No single wine is “best” for every investor, but secondary market demand in 2026 concentrates on Bordeaux’s first growths (Lafite and Mouton Rothschild), Petrus, Domaine de la Romanee-Conti, prestige Champagne such as Dom Perignon, and the leading Super Tuscans, Sassicaia above all. The right choice depends on budget, existing holdings and horizon, and prices can fall as well as rise.
What makes a wine investment grade?
Four traits together: a producer with decades of critical and market pedigree, ageing capacity of twenty years or more, production scarce enough that drinking steadily reduces supply, and enough trading activity for prices to be observable. Very few wines pass all four; most of the world’s wine never develops secondary market value.
Are famous wine brands always good investments?
No. Fame is necessary but not sufficient: second wines, celebrity labels and manufactured “limited editions” trade on borrowed prestige without real secondary demand. Even genuine investment-grade names fell during the 2022 to 2025 correction, when the broad market dropped roughly 30% from its peak (Liv-ex, 2025). Past performance is not a guide to future returns.
How much do investment-grade wines cost?
Entry points vary widely by name: cases of super seconds like Pichon Comtesse or Super Tuscans like Tignanello cost materially less than first growths, while Petrus and DRC sit at the market’s summit. A diversified WineCap portfolio starts from a £5,000 minimum investment (WineCap, August 2026).
Is Burgundy or Bordeaux better for wine investment?
They do different jobs. Bordeaux offers the deepest liquidity and price histories, making it the usual core holding; Burgundy offers the strongest scarcity dynamics with thinner liquidity and higher entry prices, suiting experienced portfolios. Many investors hold both, weighted towards Bordeaux early on.
Where can I check a wine’s investment performance before buying?
WineCap’s Wine Track follows around 3,750 investment-grade wines daily with price and performance histories. Checking any offer against these observable market levels before purchase is the single most protective habit in wine investment.